Strategy vault / Mean reversion
RSI Oversold Periodic Investment Strategy with Cooldown Optimization
The RSI Oversold Periodic Investment Strategy with Cooldown Optimization is a quantitative trading strategy based on the Relative Strength Index (RSI). This strategy primarily uses the RSI indicator to identify…
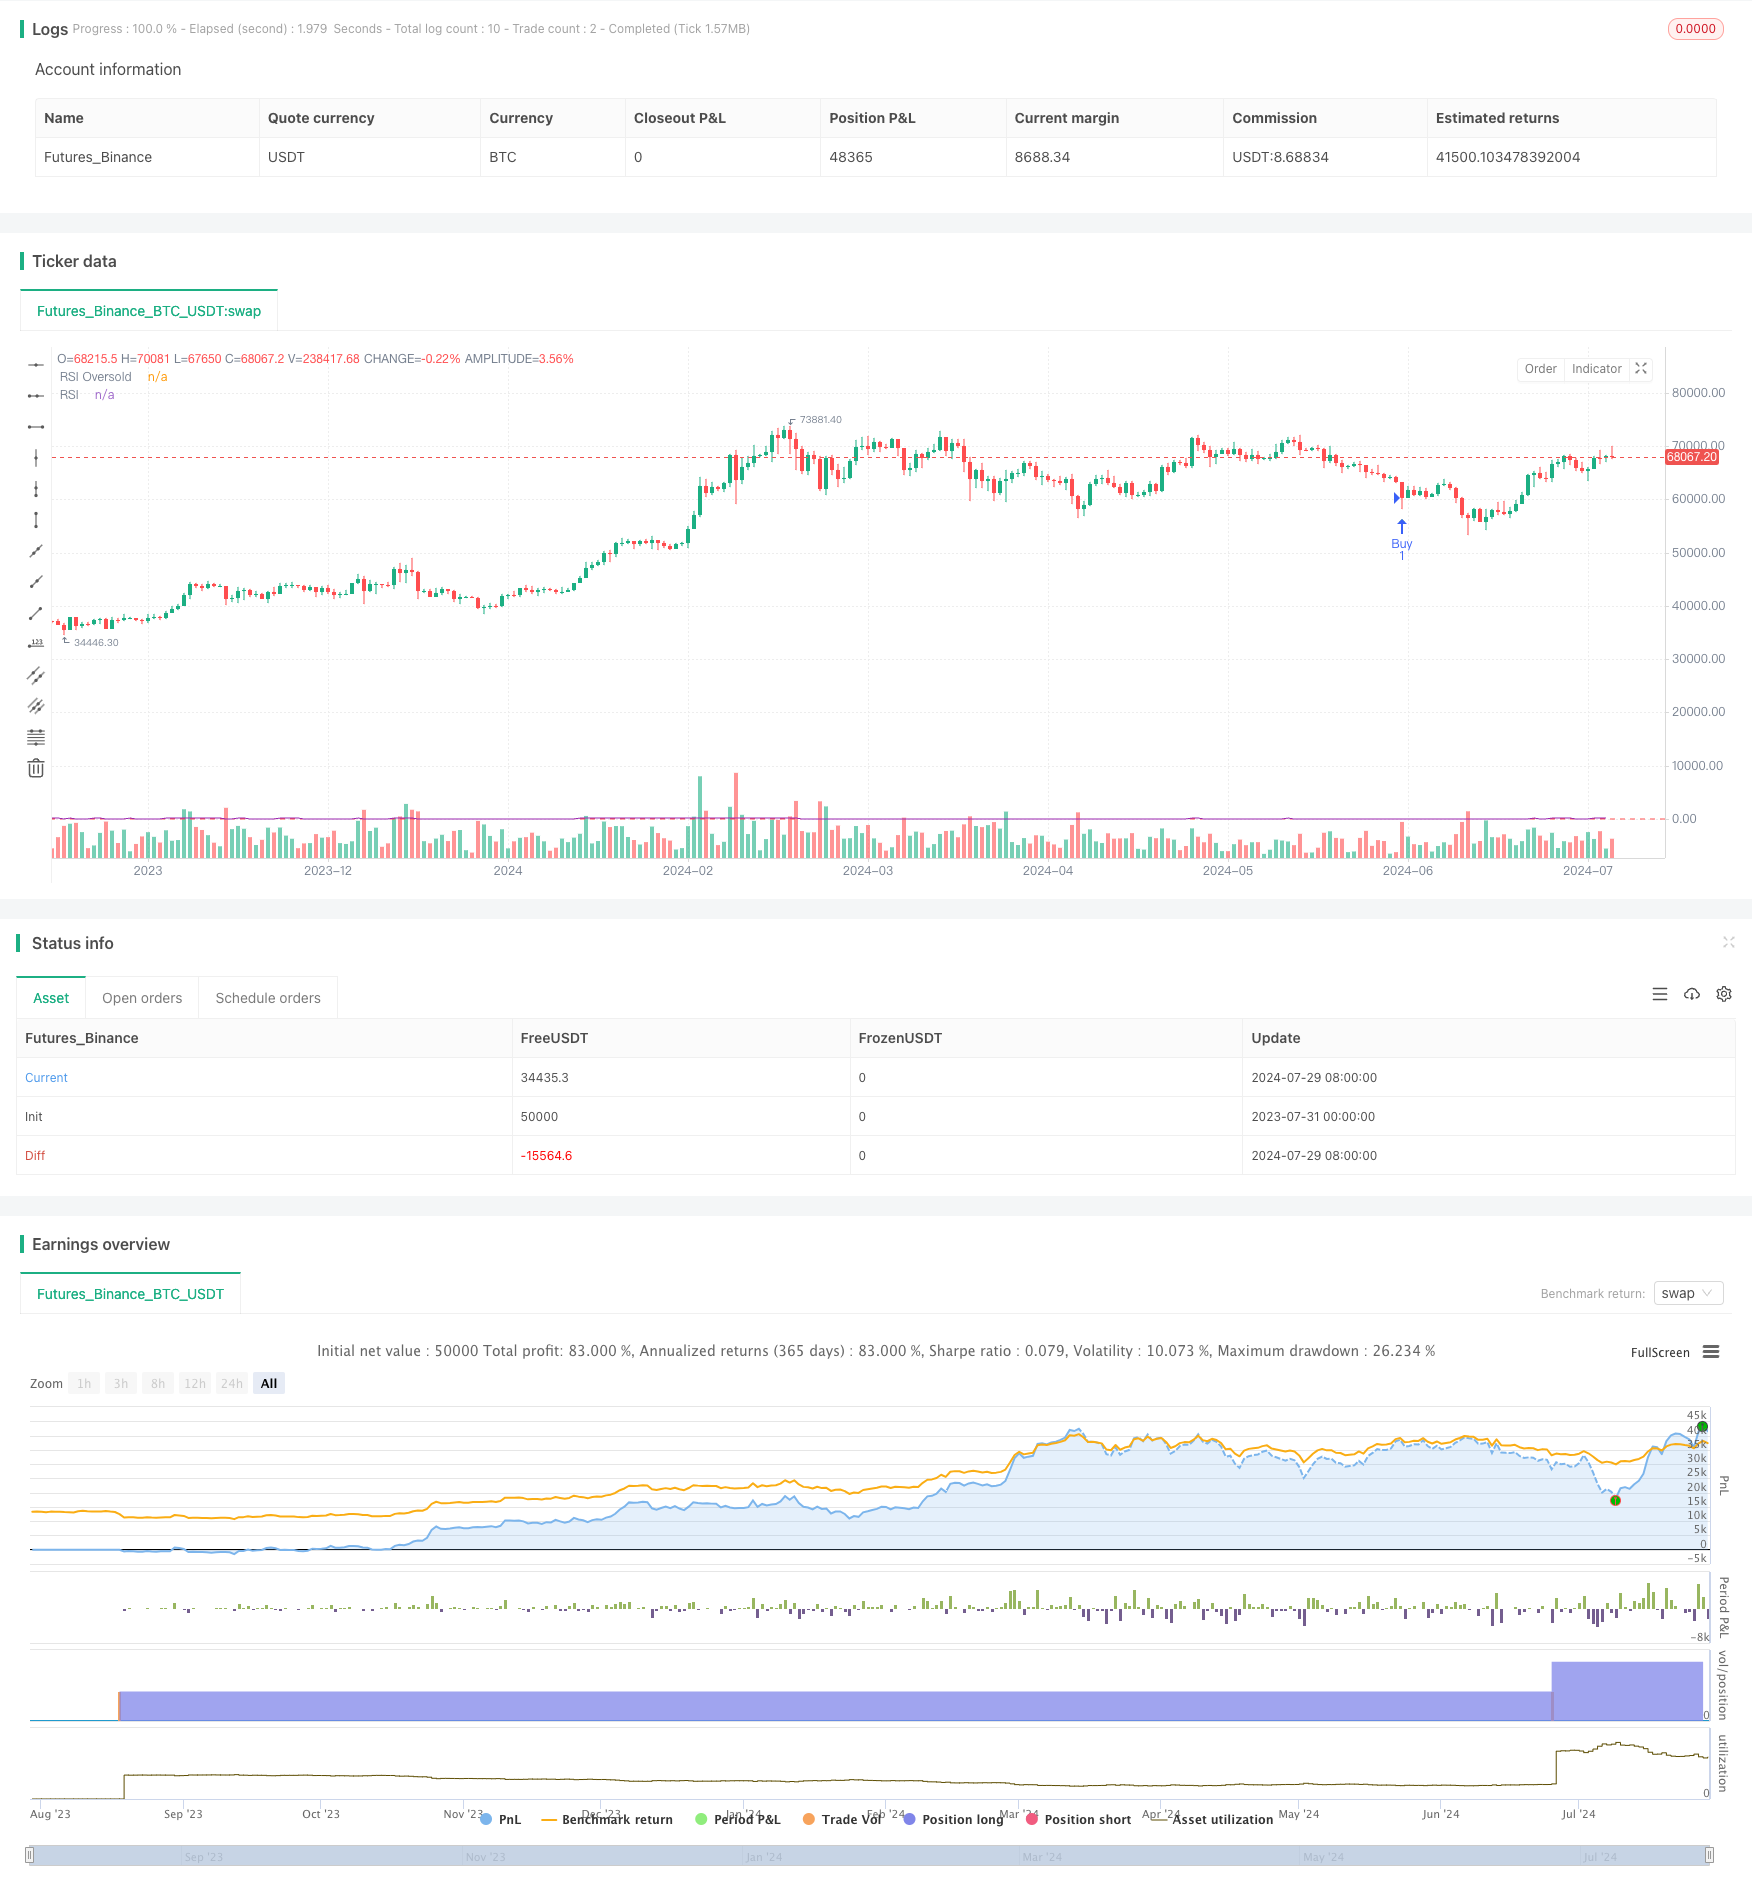
Overview
The RSI Oversold Periodic Investment Strategy with Cooldown Optimization is a quantitative trading strategy based on the Relative Strength Index (RSI). This strategy primarily uses the RSI indicator to identify oversold market conditions and executes buy orders when specific criteria are met. The core features of the strategy include using RSI oversold signals, fixed investment amounts, setting a cooldown period, and backtesting functionality. This approach aims to capture market lows while avoiding overtrading through a cooldown mechanism, providing investors with a systematic entry strategy.
Strategy Principles
RSI Calculation: The strategy uses a 14-period RSI as the main technical analysis tool. RSI is a momentum indicator used to measure the speed and change of price movements.
Oversold Determination: When the RSI value falls below a preset threshold (default 30), the market is considered oversold. This usually indicates that the asset may be undervalued and has potential for a rebound.
Buy Conditions: The strategy triggers a buy signal when two conditions are simultaneously met:
- RSI is in an oversold state (below the set threshold)
- At least 30 days (customizable cooldown period) have passed since the last purchase
Fixed Investment Amount: Each trade uses a preset fixed dollar amount (default $1,000) for investment. This method is similar to a dollar-cost averaging strategy, helping to diversify risk.
Cooldown Mechanism: After each purchase, the strategy enforces a 30-day cooldown period. During this time, no buy orders will be executed even if new oversold signals appear. This helps prevent excessive trading in the short term.
Backtesting: The strategy allows users to set a start date for backtesting, defaulting to 1000 days ago. This provides flexibility in evaluating the strategy's performance under different market conditions.
Visual Display: The strategy marks buy points on the chart, displays the RSI curve and oversold threshold line, and shows a summary of strategy execution at the end of the chart, including total investment amount, total assets acquired, average purchase cost, and total number of trades.
Strategy Advantages
Systematic Decision-Making: Through clear rules and indicators, the strategy eliminates subjective judgment, providing an objective and repeatable trading method.
Capturing Market Lows: By utilizing RSI oversold signals, the strategy aims to enter when asset prices are undervalued, increasing profit potential.
Risk Management: Fixed investment amounts and cooldown mechanisms help control risk, preventing overtrading and capital concentration.
Adapting to Market Cycles: The 30-day cooldown period helps the strategy adapt to longer market cycles, avoiding frequent trading during short-term fluctuations.
Simplicity: The strategy logic is intuitive, easy to understand and implement, suitable for investors of different experience levels.
Flexibility: Multiple customizable parameters allow investors to adjust the strategy according to personal preferences and market conditions.
Visual Feedback: Through chart markings and summary information, investors can visually assess strategy performance.
Strategy Risks
Market Trend Neglect: The strategy primarily based on the RSI indicator may ignore overall market trends, potentially leading to frequent buying in strong downward trends.
Missed Opportunities: The 30-day cooldown period may cause missing some potential good opportunities, especially in rapidly changing markets.
Single Indicator Dependence: Over-reliance on RSI may cause the strategy to perform poorly under certain market conditions, ignoring other important market signals.
Lack of Selling Mechanism: The strategy focuses only on buying, lacking clear selling or stop-loss mechanisms, which may lead to continued expansion of losses.
Fixed Investment Amount Limitation: Using a fixed amount may not fully utilize large funds or adapt to different portfolio sizes.
Backtest Bias: The strategy's backtest results may be affected by survivorship bias and overfitting, actual performance may differ from backtest results.
Trading Cost Neglect: The strategy does not consider transaction fees and slippage, which may significantly affect actual returns during frequent trading.
Strategy Optimization Directions
Introduce Trend Filters: Combine moving averages or MACD and other trend indicators to avoid frequent buying in strong downward trends.
Dynamic Cooldown Period: Adjust the length of the cooldown period based on market volatility, shortening it in high volatility periods and extending it in low volatility periods.
Multi-Indicator Integration: Combine other technical indicators such as Bollinger Bands, volume, etc., to build more comprehensive entry signals.
Add Selling Strategy: Design a selling mechanism that matches the buying strategy, such as based on RSI overbought signals or setting take-profit and stop-loss levels.
Capital Management Optimization: Introduce dynamic position management, adjusting investment amounts based on market conditions and account size.
Parameter Optimization: Use machine learning techniques to dynamically adjust RSI periods and oversold thresholds to adapt to different market environments.
Incorporate Fundamental Factors: Consider incorporating macroeconomic indicators or sentiment indicators into the decision-making process to enhance strategy comprehensiveness.
Risk Control Enhancement: Introduce maximum drawdown limits and overall risk exposure control to improve strategy robustness.
Backtest Framework Improvement: Consider trading costs, slippage, and conduct comprehensive backtests across markets and time periods to increase strategy reliability.
Conclusion
The RSI Oversold Periodic Investment Strategy with Cooldown Optimization provides investors with a systematic, quantifiable trading method. By combining RSI oversold signals, fixed investment amounts, and a cooldown mechanism, the strategy aims to capture market lows while controlling risk. Its simple and intuitive logic makes it easy to understand and implement, while customizable parameters provide flexibility.
However, the strategy also has some limitations and risks, such as potentially ignoring overall market trends, over-reliance on a single indicator, and lack of a selling mechanism. To enhance the strategy's robustness and adaptability, it is recommended to consider introducing trend filters, multi-indicator integration, dynamic parameter adjustment, and other optimization directions.
Overall, this strategy provides investors with a good starting point, but in practical application, investors should make appropriate adjustments and optimizations based on personal risk preferences and market conditions. Through continuous monitoring and improvement, combined with more comprehensive risk management measures, this strategy has the potential to become an effective long-term investment tool.
Source Pine Script
/*backtest
start: 2023-07-31 00:00:00
end: 2024-07-30 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("RSI Buy Strategy with 30-day Cooldown", overlay=true)

// Parameter Settings
rsiLength = 14
rsiOversold = 30
usdAmount = 1000
cooldownPeriod = 30 * 24 * 60

// CalculationRSI
rsi = ta.rsi(close, rsiLength)

// Track last buy time
var int lastBuyTime = 0
var bool buySignal = false

daysBack = input.int(1000, title="The number of days since the strategy started (from today back)", minval=1)
startDate = timenow - daysBack * 24 * 60 * 60 * 1000
isInTradingPeriod = true

// Execution Strategy
if (isInTradingPeriod and rsi < rsiOversold and (time - lastBuyTime) >= cooldownPeriod * 60000)
    strategy.entry("Buy", strategy.long)
    lastBuyTime := time
    buySignal := true

    // Show details in transaction list
    strategy.order("Buy", strategy.long, comment="USD: " + str.tostring(usdAmount))
else
    buySignal := false

// Displays a small mark at the buy point
plotshape(buySignal, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.triangleup, size=size.small)

// Display on chartRSI
plot(rsi, "RSI", color=color.purple)
hline(rsiOversold, "RSI Oversold", color=color.red)

// Calculate and Display Summary
if (barstate.islastconfirmedhistory)
    tradeCount = strategy.opentrades
    totalUsd = usdAmount * tradeCount
    totalBtc = strategy.position_size

    // Calculate the correct average purchase cost
    avgCost = totalBtc != 0 ? totalUsd / totalBtc : na

    label.new(bar_index, high, text="\nUSDTotal: " + str.tostring(totalUsd) +
              "\nBTCTotal: " + str.tostring(totalBtc) +
              "\nPurchase Cost: " + str.tostring(avgCost,"#.##") +
              "\nNumber of Trades: " + str.tostring(tradeCount),
              style=label.style_label_down,
              color=color.new(color.teal, 20),
textalign="left")Published by ChaoZhang on the FMZ strategy square · last modified 2024-07-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Oversold-Periodic-Investment-Strategy-with-Cooldown-Optimization.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive RSI Oscillator Dynamic Trading Strategy with Threshold OptimizationPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Fibonacci Retracement Trend Following and Reversal Trading StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d