Strategy vault / Mean reversion
RSI V shaped Pattern Swing Trading Strategy
This strategy is based on the V-shaped pattern formed by the RSI indicator, combined with EMA filters, to develop a reliable short-term profitable trading strategy. It captures rebound opportunities when the price is…
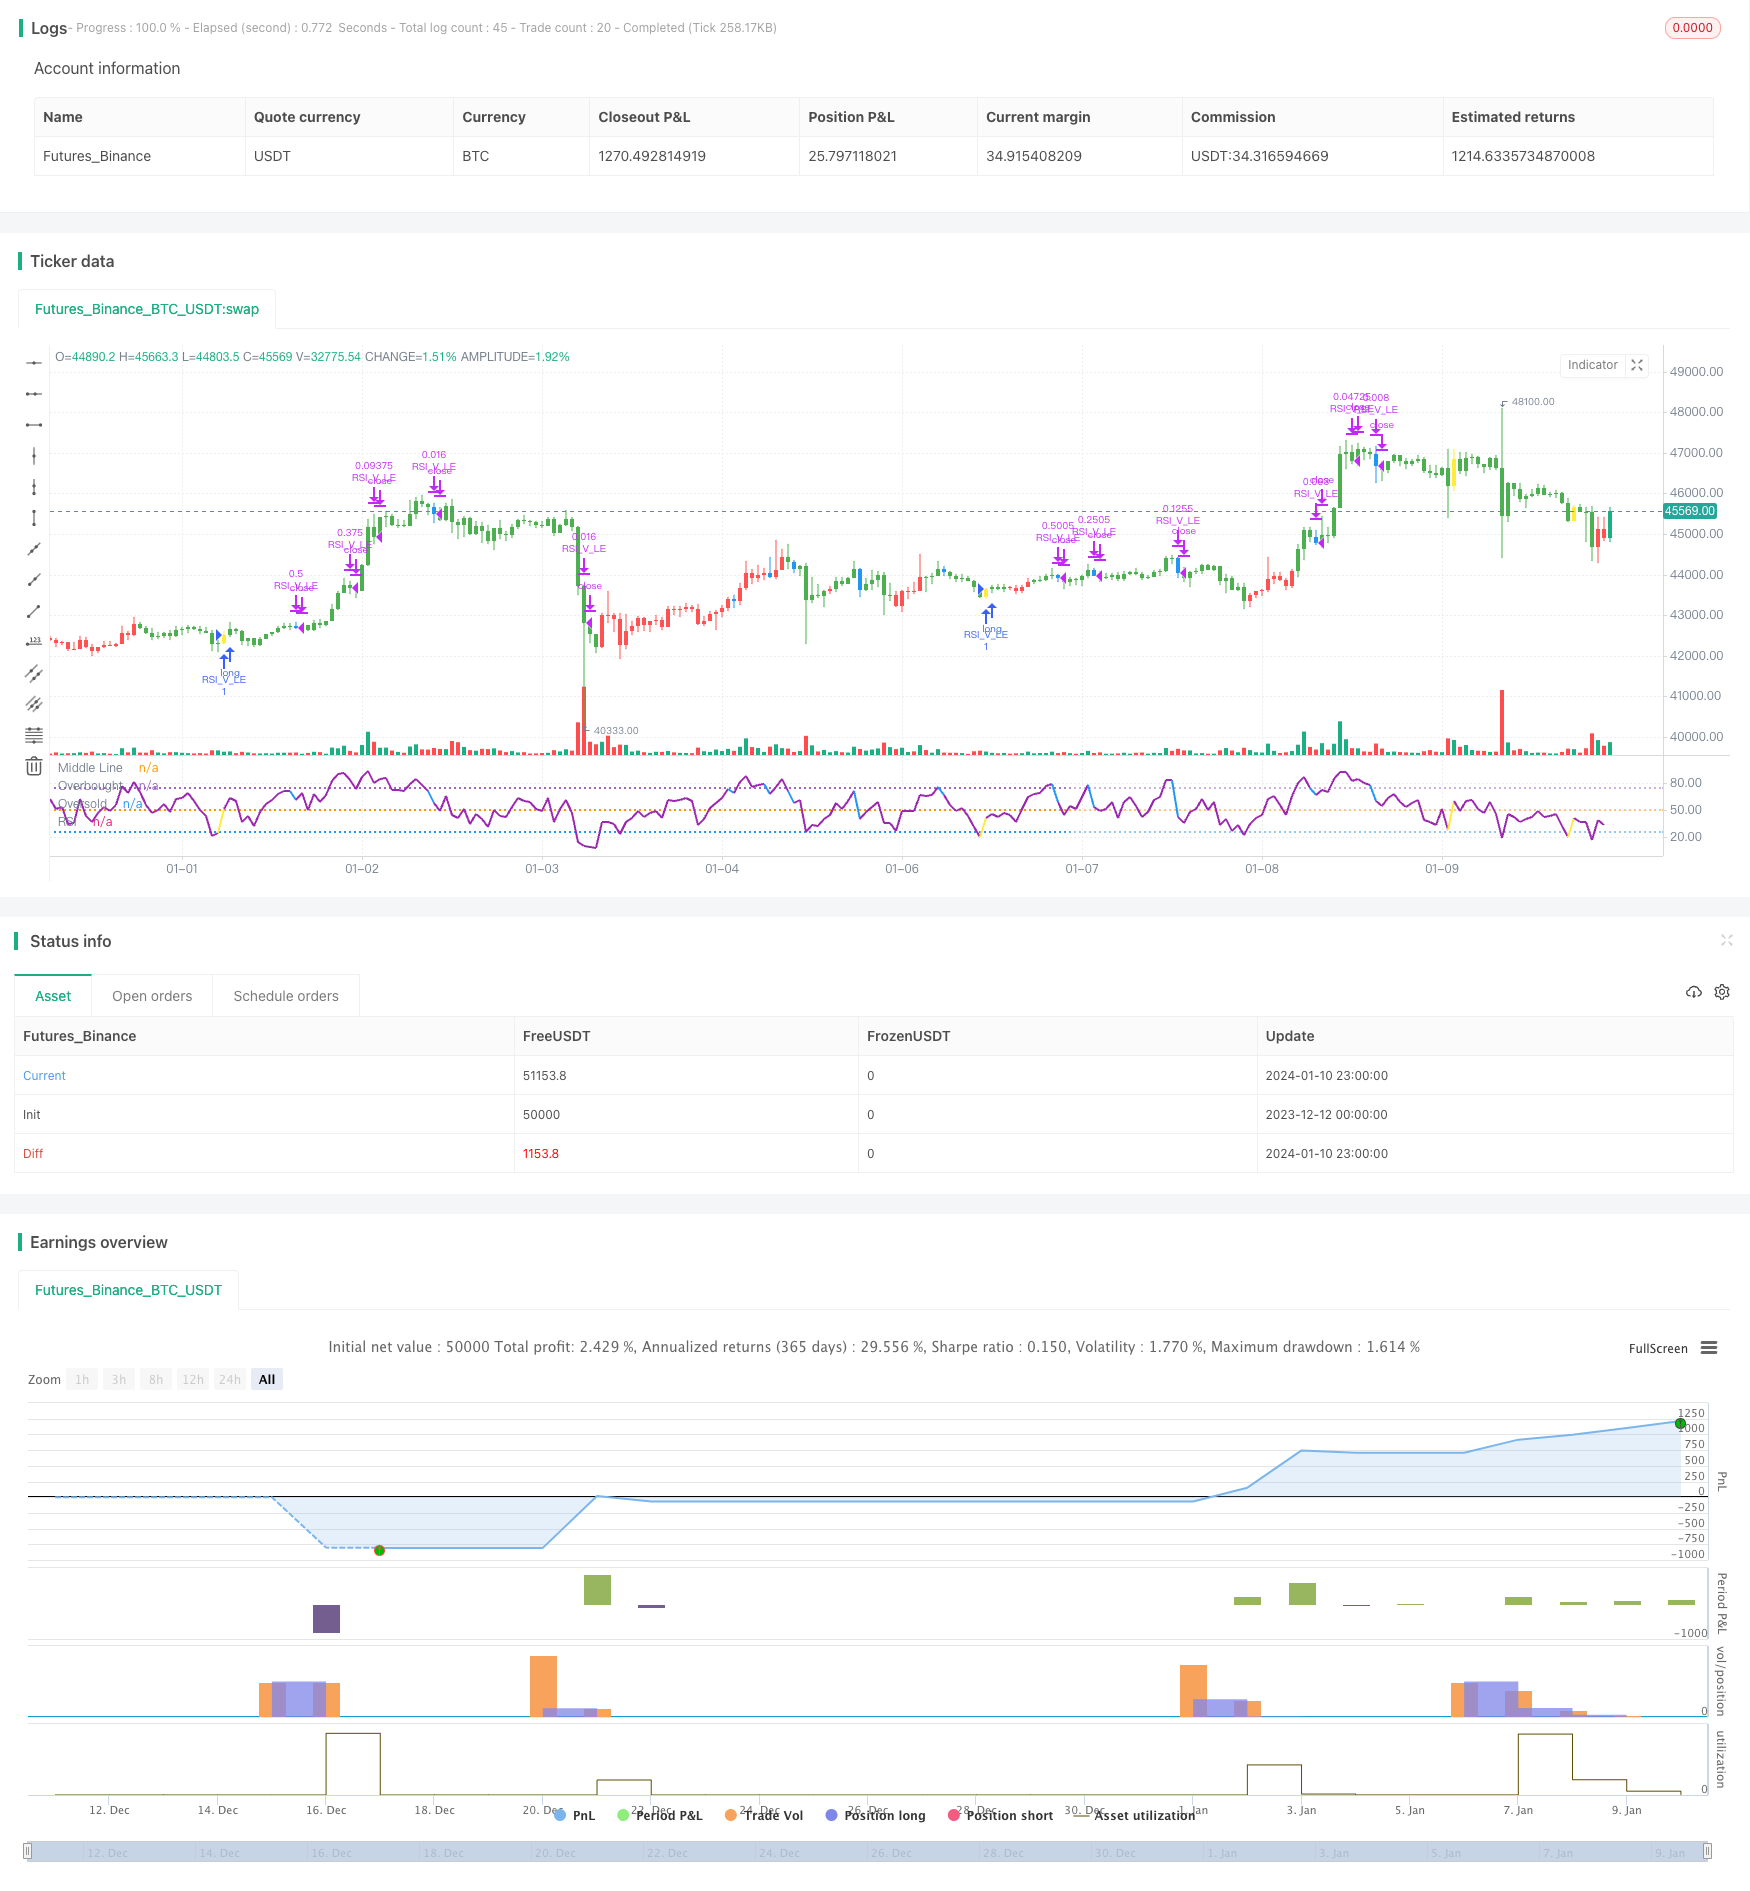
Overview
This strategy is based on the V-shaped pattern formed by the RSI indicator, combined with EMA filters, to develop a reliable short-term profitable trading strategy. It captures rebound opportunities when the price is oversold by accurately going long through RSI's V-shaped signals, for the purpose of making profits in the short run.
Strategy Logic
- Use 20-day EMA above 50-day EMA as the judgment of long-term uptrend
- RSI forms V-shaped pattern, indicating oversold rebound opportunities
- Previous bar's low is lower than previous 2 bars' low
- Current bar's RSI is higher than previous 2 bars' RSI
- RSI crosses above 30 as the completion signal of V-shaped pattern to go long
- Set stop loss at 8% below entry price
- When RSI crosses 70, start closing positions and move stop loss to entry price
- When RSI crosses 90, close 3/4 positions
- When RSI goes below 10 / stop loss triggered, close all positions
Advantage Analysis
- Use EMA to judge overall market direction, avoid trading against the trend
- RSI V-shaped pattern captures mean-reverting opportunities when oversold
- Multiple stop loss mechanisms to control risks
Risk Analysis
- Strong downtrend may incur unstoppable losses
- RSI V-shaped signals may give false signals, leading to unnecessary losses
Optimization Directions
- Optimize RSI parameters to find more reliable V-shaped patterns
- Incorporate other indicators to enhance reliability of reversal signals
- Refine stop loss strategy, balance between preventing over-aggressiveness and timely stop loss
Summary
This strategy integrates EMA filter and RSI V-shaped pattern judgment to form a reliable short-term trading strategy. It can effectively seize the rebound opportunities when oversold. With continuous optimization on parameters and models, improving stop loss mechanisms, this strategy can be further enhanced in stability and profitability. It opens the door of profitable swing trading for quant traders.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 5 | RSI Period |
| v_input_2 | 8 | Stop Loss % |
Source Pine Script
/*backtest
start: 2023-12-12 00:00:00
end: 2024-01-11 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © mohanee

//@version=4
//strategy("RSI V Pattern", overlay=true)
strategy(title="RSI V Pattern", overlay=false )

//Strategy Rules
//ema20 is above ema50  --- candles are colored  green on the chart
//RSI value sharply coming up which makes a V shape ,  colored in yellow on the chart
//RSI V pattern should occur from below 30

len = input(title="RSI Period", minval=1, defval=5)
stopLoss = input(title="Stop Loss %", minval=1, defval=8)

myRsi = rsi(close,len)

longEmaVal=ema(close,50)
shortEmaVal=ema(close,20)

//plot emas
//plot(longEmaVal, title="Long EMA" ,linewidth=2, color=color.orange, trackprice=true)
//plot(shortEmaVal, title="Short EMA" ,linewidth=2, color=color.green, trackprice=true)


longCondition =  ema(close,20)>ema(close,50)   and (low[1]<low[2] and  low[1]<low[3]) and (myRsi>myRsi[1] and myRsi>myRsi[2] ) and crossover(myRsi,30) //  (   and myRsi<60)

//(myRsi<60 and myRsi>30)  and myRsi>myRsi[1] and (myRsi[1]<myRsi[2]  or  myRsi[1]<myRsi[3]) and (myRsi[2]<30)  and (myRsi[3]<30 and myRsi[4]>=30)


barcolor(shortEmaVal>longEmaVal?color.green:color.red)
//longCondition = crossover(sma(close, 14), sma(close, 28))
barcolor(longCondition?color.yellow:na)
strategy.entry("RSI_V_LE", strategy.long, when=longCondition )
//stoploss value at 10%
stopLossValue=strategy.position_avg_price -  (strategy.position_avg_price*stopLoss/100)
//stopLossValue=valuewhen(longCondition,low,3)


//takeprofit at RSI highest  reading
//at RSI75 move the stopLoss to entry price
moveStopLossUp=strategy.position_size>0 and crossunder(myRsi,70)
barcolor(moveStopLossUp?color.blue:na)
stopLossValue:=crossover(myRsi,70) ? strategy.position_avg_price:stopLossValue

//stopLossValue:=moveStopLossUp?strategy.position_avg_price:stopLossValue
rsiPlotColor=longCondition ?color.yellow:color.purple
rsiPlotColor:= moveStopLossUp ?color.blue:rsiPlotColor
plot(myRsi, title="RSI", linewidth=2, color=rsiPlotColor)
//longCondition?color.yellow:#8D1699)
hline(50, title="Middle Line", linestyle=hline.style_dotted)
obLevel = hline(75, title="Overbought", linestyle=hline.style_dotted)
osLevel = hline(25, title="Oversold", linestyle=hline.style_dotted)
fill(obLevel, osLevel, title="Background", color=#9915FF, transp=90)


//when RSI crossing down 70 , close 1/2 position and move stop loss to average entry price
strategy.close("RSI_V_LE",  qty=strategy.position_size*1/2, when=strategy.position_size>0 and crossunder(myRsi,70))

//when RSI reaches high reading 90 and crossing down close 3/4 position
strategy.close("RSI_V_LE",  qty=strategy.position_size*3/4, when=strategy.position_size>0 and crossunder(myRsi,90))


//close everything when Rsi goes down below to 10 or stoploss hit
//just keeping RSI cross below 10 , can work as stop loss , which also keeps you long in the trade ... however sharp declines could  make large loss
//so I combine RSI goes below 10 OR stoploss hit  , whichever comes first - whole posiition closed
longCloseCondition=crossunder(myRsi,10)  or close<stopLossValue
strategy.close("RSI_V_LE", qty=strategy.position_size,when=longCloseCondition )
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-V-shaped-Pattern-Swing-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dual Moving Average Crossover with RSI Overbought Oversold Pyramid Dynamic Trend Trading StrategyPine Script · Mean reversion · 2h