SAR 3 SMMA with SL TP
This script is a combination of SAR strategy and 3 Smoothed Moving Averages. Strategy: Takes SAR longs when all 3 SMMAs are rising. Take SAR short when all 3 SMMAs are falling. Supports StopLoss and TakeProfit. If…
This script is a combination of SAR strategy and 3 Smoothed Moving Averages.
Strategy: Takes SAR longs when all 3 SMMAs are rising. Take SAR short when all 3 SMMAs are falling.
Supports StopLoss and TakeProfit.
If you have found a profitable setup for it, please share in the comments or private chat.
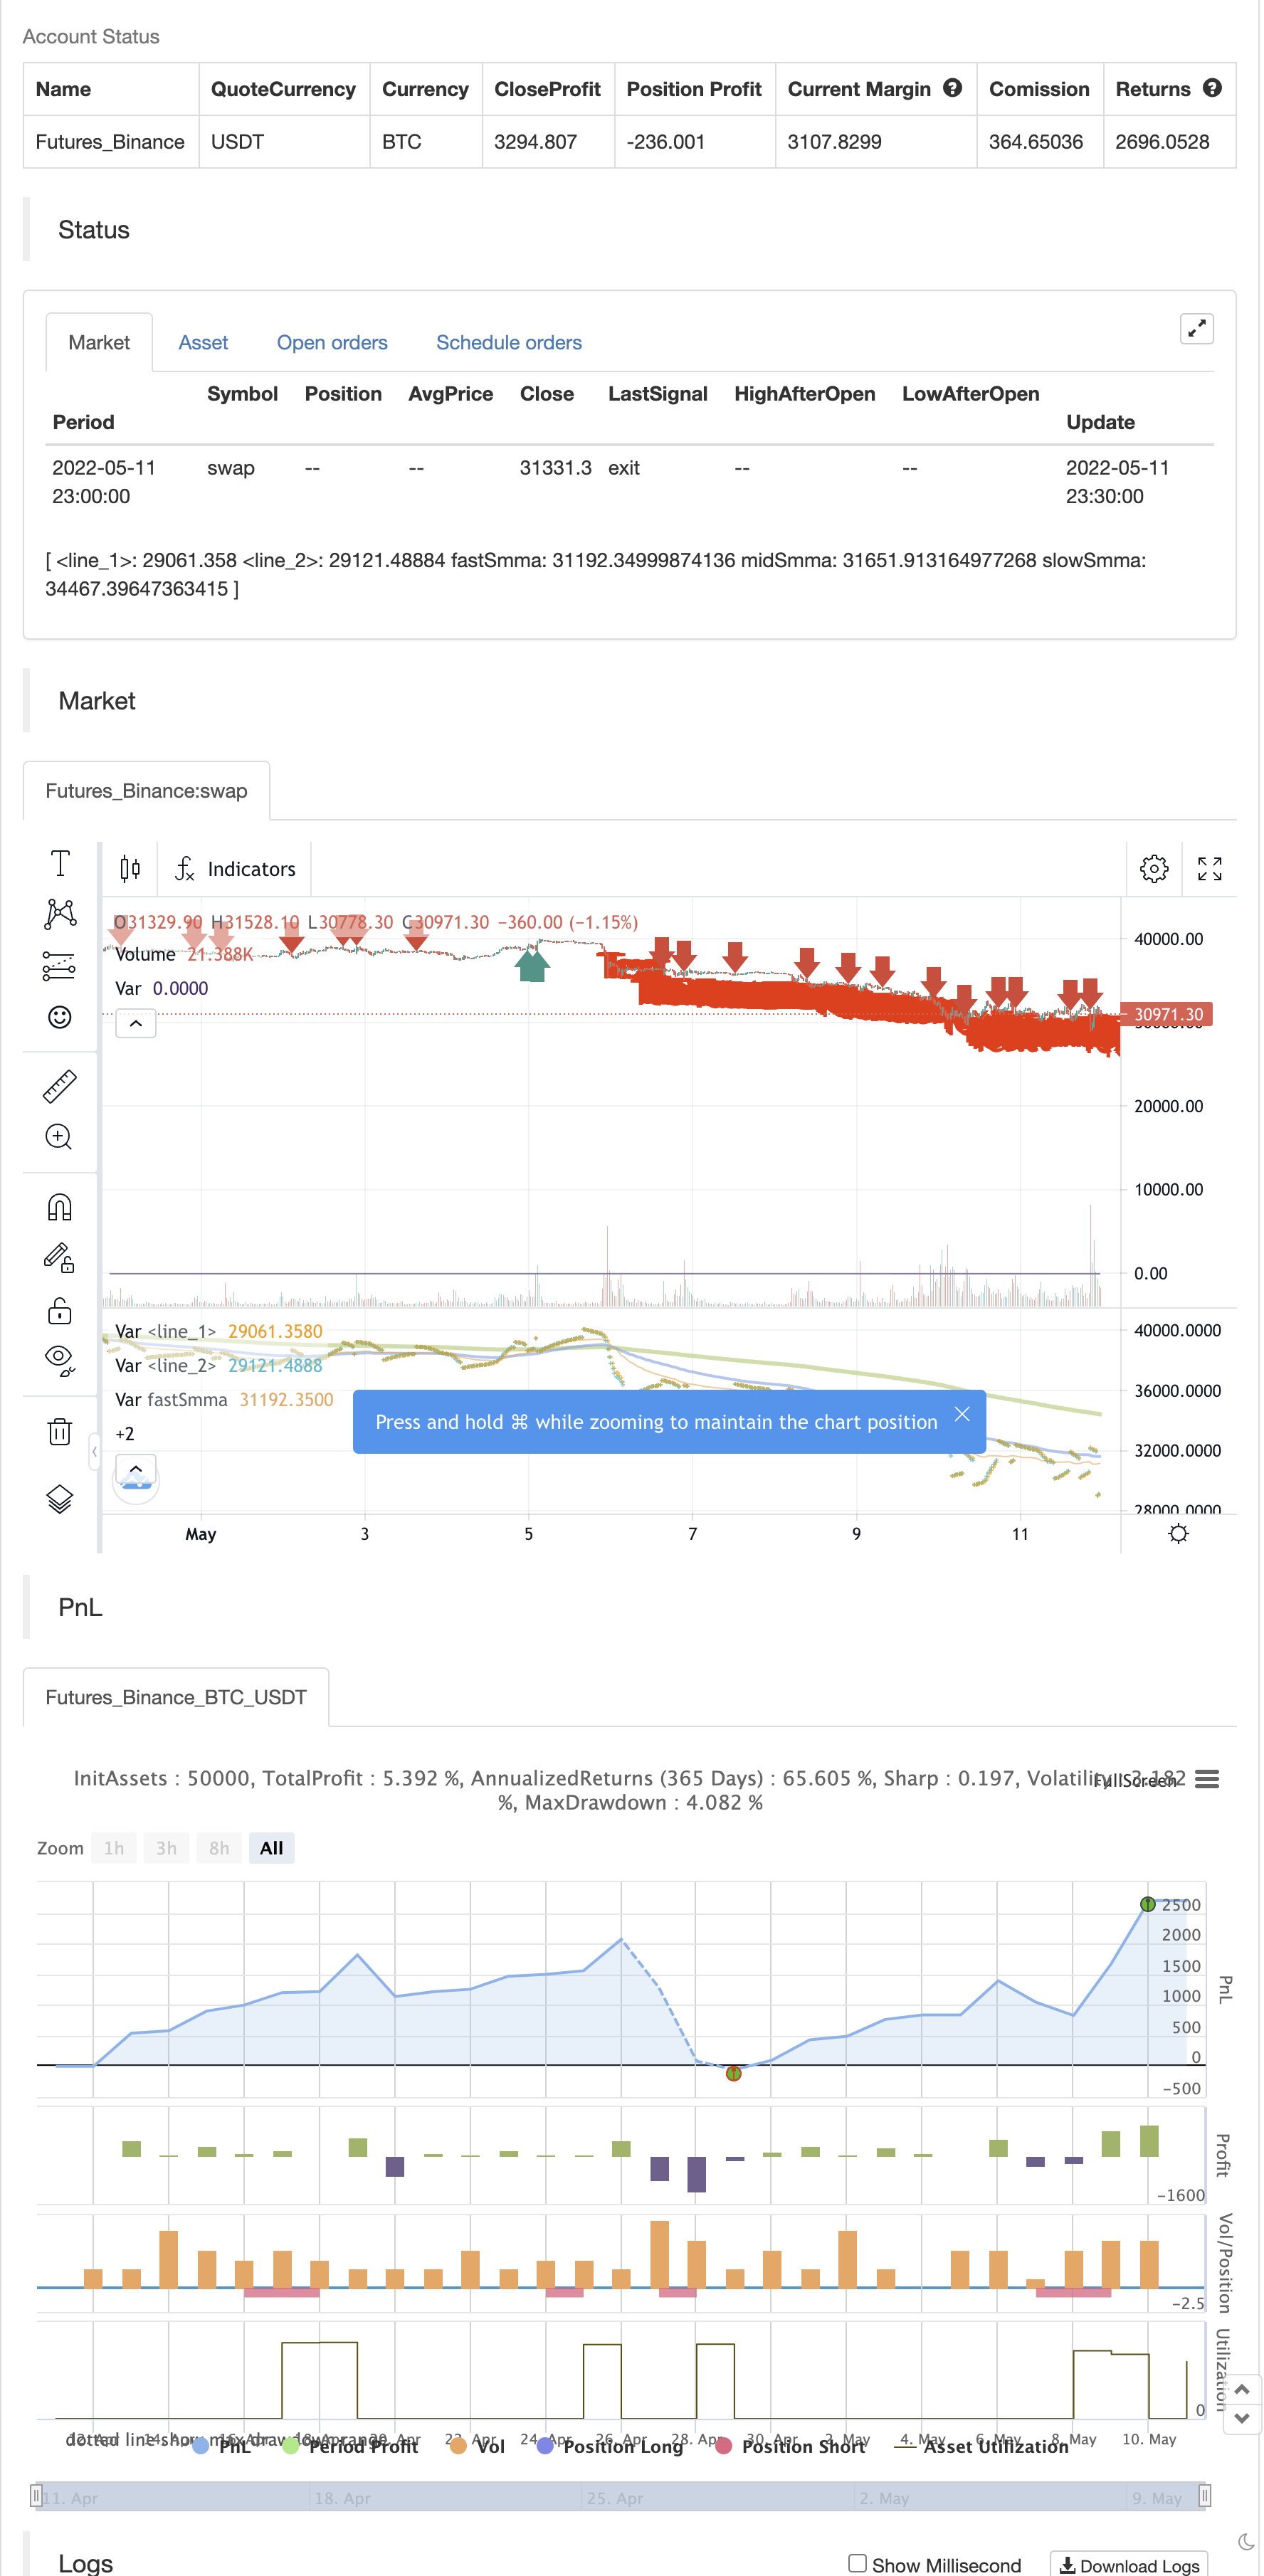
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | 0.02 | (?na)start |
| v_input_float_2 | 0.02 | increment |
| v_input_float_3 | 0.2 | maximum |
| v_input_float_4 | 0.1 | (?Stop Loss and Take Profit)Take Profit (%) |
| v_input_float_5 | true | StopLoss (%) |
| v_input_int_1 | 21 | (?Smooth Moving Average)Fast Length |
| v_input_int_2 | 50 | Mid Length |
| v_input_int_3 | 200 | Slow Length |
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
Source Pine Script
/*backtest
start: 2022-04-12 00:00:00
end: 2022-05-11 23:59:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
//strategy(title="SAR + 3SMMA with SL & TP", overlay=true, calc_on_order_fills=false, calc_on_every_tick=false, default_qty_type=strategy.percent_of_equity, default_qty_value=100, currency=currency.USD, commission_type= strategy.commission.percent, commission_value=0.03)
start = input.float(0.02, step=0.01, group="SAR")
increment = input.float(0.02, step=0.01, group="SAR")
maximum = input.float(0.2, step=0.01, group="SAR")

//Take Profit Inputs
take_profit = input.float(title="Take Profit (%)", minval=0.0, step=0.1, defval = 0.1, group="Stop Loss and Take Profit", inline="TP") * 0.01

//Stop Loss Inputs
stop_loss = input.float(title="StopLoss (%)", minval=0.0, step=0.1, defval=1, group="Stop Loss and Take Profit", inline="SL") * 0.01

// Smooth Moving Average
fastSmmaLen = input.int(21, minval=1, title="Fast Length", group = "Smooth Moving Average")
midSmmaLen = input.int(50, minval=1, title="Mid Length", group = "Smooth Moving Average")
slowSmmaLen = input.int(200, minval=1, title="Slow Length", group = "Smooth Moving Average")

src = input(close, title="Source", group = "Smooth Moving Average")

smma(ma, src, len) =>
    smma = 0.0
    smma := na(smma[1]) ? ma : (smma[1] * (len - 1) + src) / len
    smma

fastSma = ta.sma(src, fastSmmaLen)
midSma = ta.sma(src, midSmmaLen)
slowSma = ta.sma(src, slowSmmaLen)

fastSmma = smma(fastSma, src, fastSmmaLen)
midSmma = smma(midSma, src, midSmmaLen)
slowSmma = smma(slowSma, src, slowSmmaLen)

isSmmaUpward = ta.rising(fastSmma, 1) and ta.rising(midSmma, 1) and ta.rising(slowSmma, 1)

var bool uptrend = na
var float EP = na
var float SAR = na
var float AF = start
var float nextBarSAR = na

if bar_index > 0
	firstTrendBar = false
	SAR := nextBarSAR
	if bar_index == 1
		float prevSAR = na
		float prevEP = na
		lowPrev = low[1]
		highPrev = high[1]
		closeCur = close
		closePrev = close[1]
		if closeCur > closePrev
			uptrend := true
			EP := high
			prevSAR := lowPrev
			prevEP := high
		else
			uptrend := false
			EP := low
			prevSAR := highPrev
			prevEP := low
		firstTrendBar := true
		SAR := prevSAR + start * (prevEP - prevSAR)
	if uptrend
		if SAR > low
			firstTrendBar := true
			uptrend := false
			SAR := math.max(EP, high)
			EP := low
			AF := start
	else
		if SAR < high
			firstTrendBar := true
			uptrend := true
			SAR := math.min(EP, low)
			EP := high
			AF := start
	if not firstTrendBar
		if uptrend
			if high > EP
				EP := high
				AF := math.min(AF + increment, maximum)
		else
			if low < EP
				EP := low
				AF := math.min(AF + increment, maximum)
	if uptrend
		SAR := math.min(SAR, low[1])
		if bar_index > 1
			SAR := math.min(SAR, low[2])
	else
		SAR := math.max(SAR, high[1])
		if bar_index > 1
			SAR := math.max(SAR, high[2])
	nextBarSAR := SAR + AF * (EP - SAR)

sarIsUpTrend = uptrend ? true : false

sarFlippedDown = sarIsUpTrend and not sarIsUpTrend[1] ? true : false
sarFlippedUp = not sarIsUpTrend and sarIsUpTrend[1] ? true : false


longEntryCondition = isSmmaUpward and sarFlippedDown
shortEntryCondition = not isSmmaUpward and sarFlippedUp

if(longEntryCondition)
    strategy.entry("L", strategy.long, stop=nextBarSAR, comment="L")

if(shortEntryCondition)
    strategy.entry("S", strategy.short, stop=nextBarSAR, comment="S")


strategy.exit("CL", when=strategy.position_size > 0, limit=strategy.position_avg_price * (1+take_profit), stop=strategy.position_avg_price*(1-stop_loss))
strategy.exit("CS", when=strategy.position_size < 0, limit=strategy.position_avg_price * (1-take_profit), stop=strategy.position_avg_price*(1+stop_loss))


plot(SAR, style=plot.style_cross, linewidth=1, color=color.orange)
plot(nextBarSAR, style=plot.style_cross, linewidth=1, color=color.aqua)
plot(series = fastSmma, title="fastSmma", linewidth=1)
plot(series = midSmma, title="midSmma", linewidth=2)
plot(series = slowSmma, title="slowSmma", linewidth=3)
plotchar(series = isSmmaUpward, title="isSmmaUpward", char='')
plotchar(series=sarIsUpTrend, title="sarIsUpTrend", char='')
plotchar(series=sarFlippedUp, title="sarFlippedUp", char='')
plotchar(series=sarFlippedDown, title="sarFlippedDown", char='')
plotchar(series=longEntryCondition, title="longEntryCondition", char='')
plotchar(series=shortEntryCondition, title="shortEntryCondition", char='')
plotchar(series=strategy.position_size > 0, title="inLong", char='')
plotchar(series=strategy.position_size < 0, title="inShort", char='')


//plot(strategy.equity, title="equity", color=color.red, linewidth=2, style=plot.style_areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/SAR-3SMMA-with-SL-TP.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.