Scaled Normalized Vector Strategy with Activation Functions ver4
This is an improvement of drkhodakarami's Scaled Normalized Vector strategy, mainly adding activation functions to enhance the strategy's performance. The strategy calculates the rate of change in the market based on…
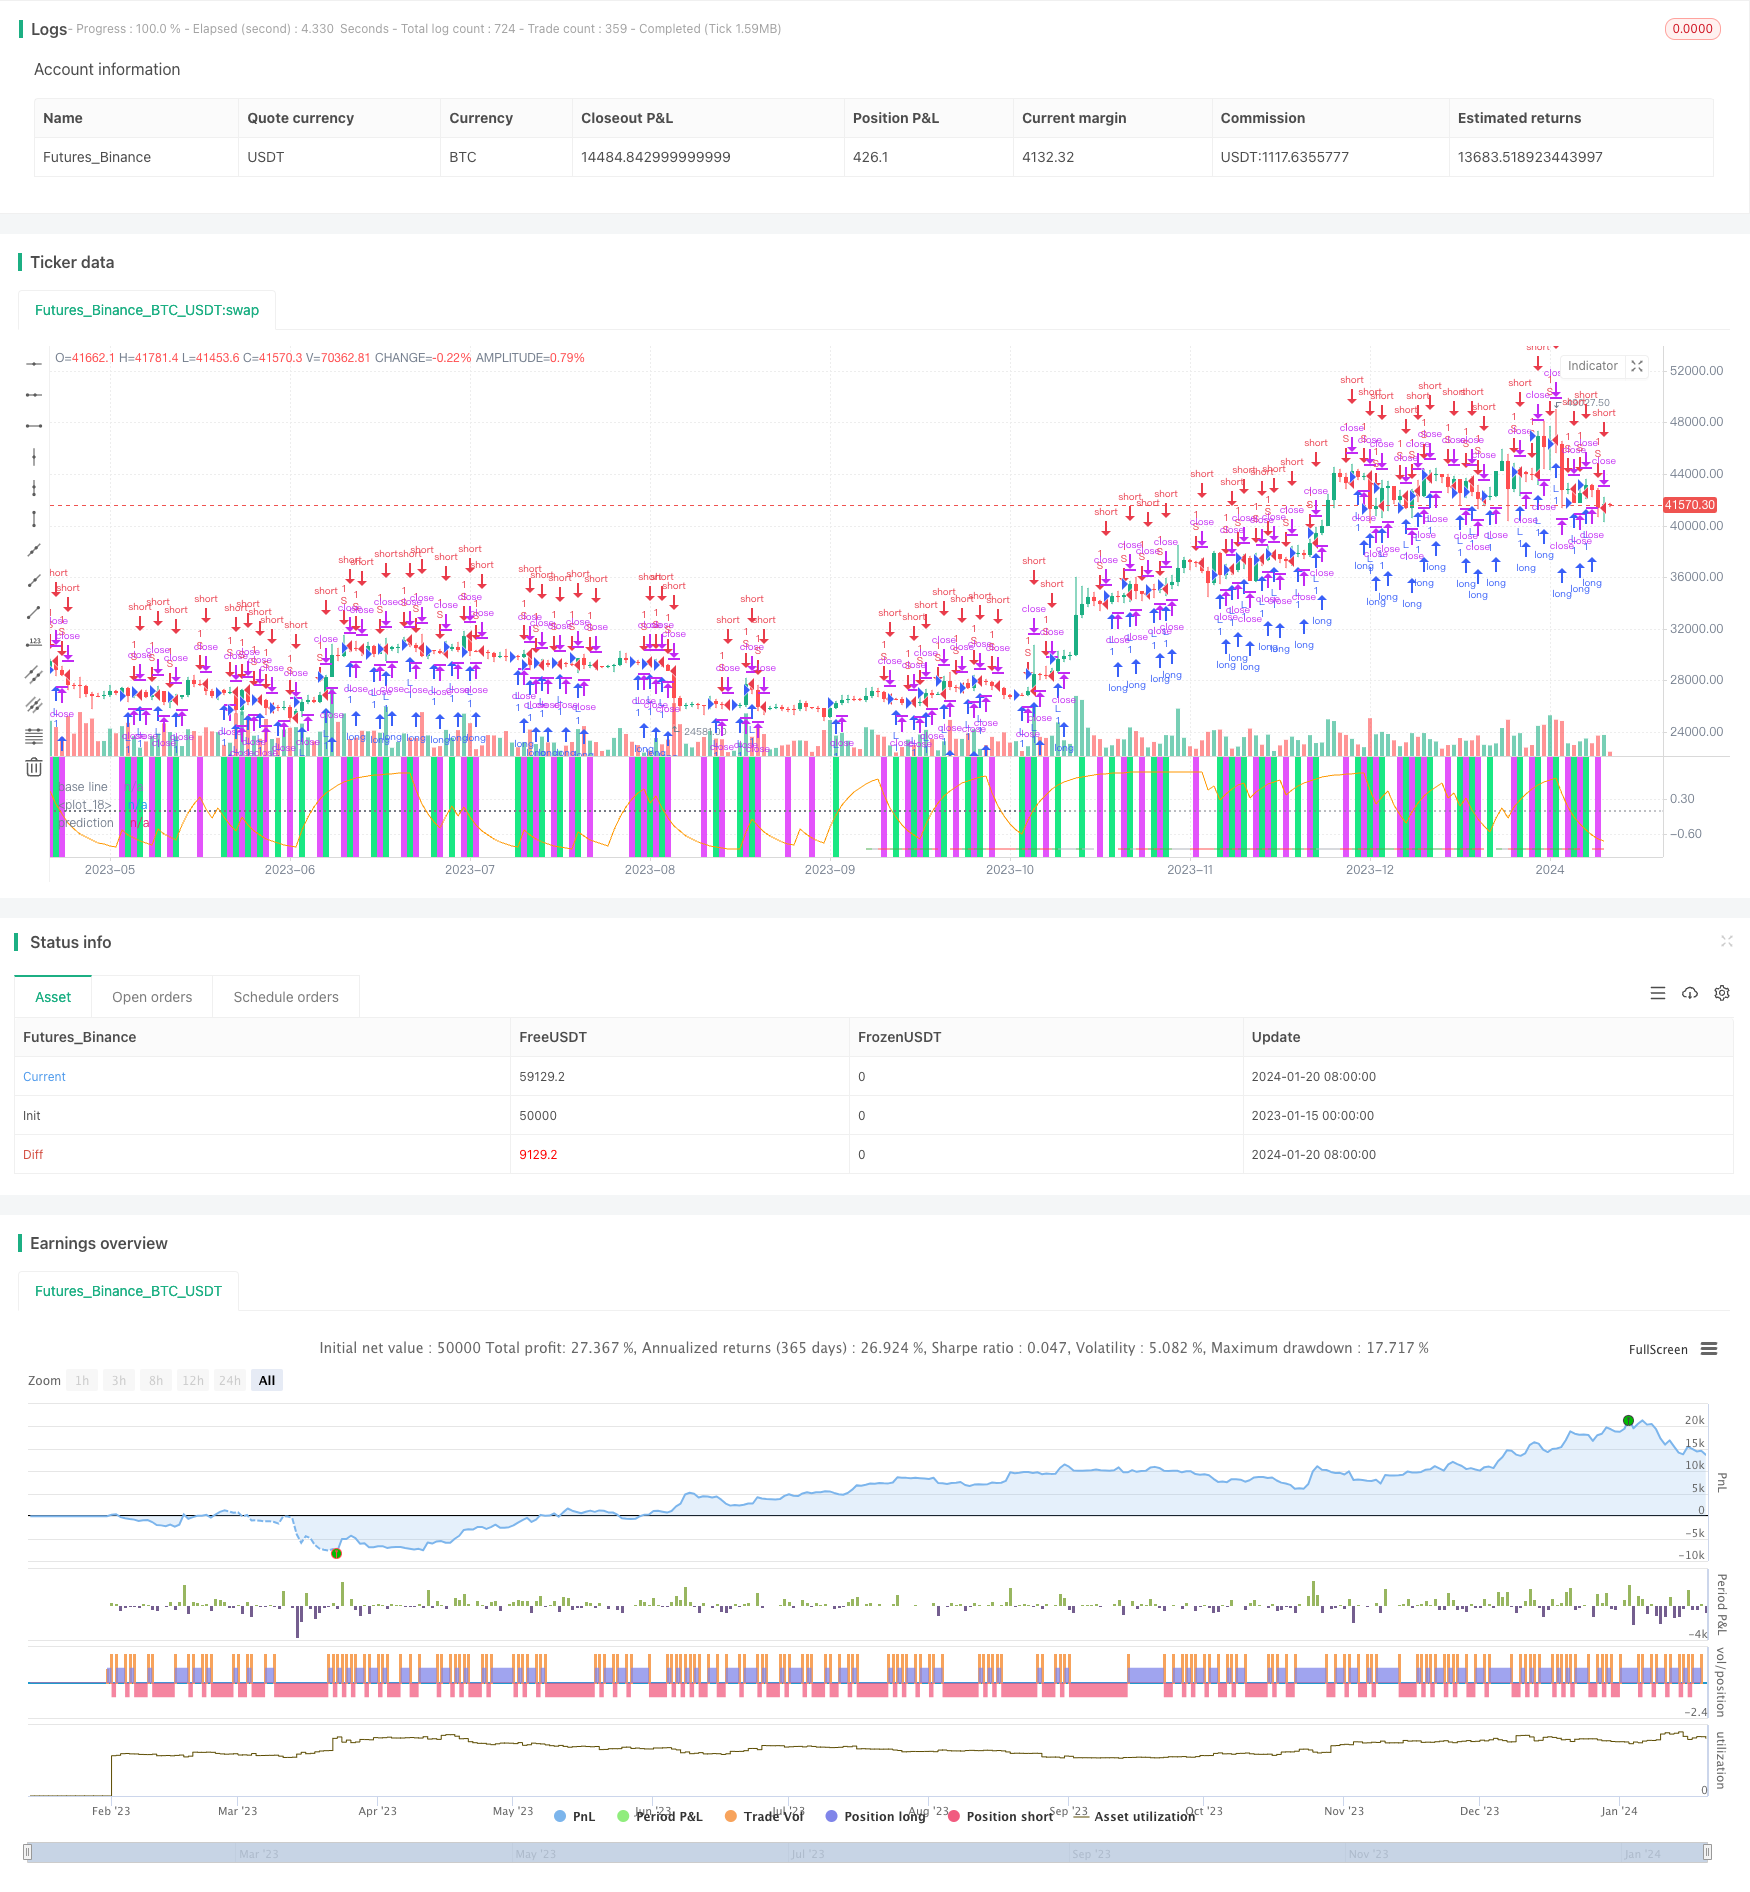
Overview
This is an improvement of drkhodakarami's Scaled Normalized Vector strategy, mainly adding activation functions to enhance the strategy's performance. The strategy calculates the rate of change in the market based on timeframe differences, and determines long and short signals based on threshold values. Meanwhile, swish, ReLU and step activation functions are introduced to smooth the differential sequence and improve the accuracy of signal judgement.
Strategy Logic
- Calculate the percentage price change x of close on the set timeframe
- Pass x to the activation function to get the processed sequence p
- Set positive and negative thresholds th, go long when p crosses above th, and go short when crossing below -th
- Disable repainting to avoid fake signals
Advantage Analysis
- Activation functions help filter noise and improve signal judgement
- New entry and close logic enables automated trading
- More parameter customization adapts to more markets
- Excellent visualization intuitively presents trade signals
Risk Analysis
- Improper threshold settings may miss trade opportunities
- Unsuitable activation functions may over-filter market information
- Repainting-induced signal distortions need testing
Solutions:
- Adjust threshold parameters to find optimum
- Try different activation functions to find the best match
- Add repainting detection logic to confirm valid signals
Optimization Directions
- Add adaptive threshold setting
- Optimize activation function parameters
- Incorporate automatic stop loss
- Filter signals with more factors
Conclusion
Based on drkhodakarami's work, this strategy introduces activation functions to enhance performance. The expanded parameter customization better adapts to market changes. Meanwhile, the excellent visualization intuitively presents trading opportunities. Next steps are to further optimize activation functions and threshold settings, incorporate stop loss logic and more signal filtering to achieve even better strategy efficacy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Price Data: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 18 | Timeframe |
| v_input_3 | 14 | Threshold |
| v_input_4 | 0 | Divisor: 1000000 | 10 | 100 | 1000 | 10000 | 100000 | 1 | 10000000 | 100000000 |
| v_input_5 | 0 | Minimax Lookback: 233 | 2 | 3 | 5 | 8 | 13 | 21 | 34 | 55 | 89 | 144 | 1 | 377 | 610 | 987 | 1597 | 2584 |
| v_input_6 | false | Volume |
| v_input_7 | true | Use Old System |
| v_input_8 | 0 | Activation: Swish | LReLU | Step | None |
| v_input_9 | 8 | Karobein Osc Lookback |
Source Pine Script
/*backtest
start: 2023-01-15 00:00:00
end: 2024-01-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
// author: capissimo
strategy("Scaled Normalized Vector Strategy, ver.4", precision=2, overlay=false)
// This is a modification of my Scaled Normalized Vector Strategy
// original: Drkhodakarami (https://www.tradingview.com/script/Fxv2xFWe-Normalized-Vector-Strategy-By-Drkhodakarami-Opensource/)

price    = input(close,  "Price Data")
tf       = input(18,     "Timeframe", minval=1, maxval=1440)
thresh   = input(14.,    "Threshold", minval=.1, step=.1)
div      = input(1000000,"Divisor", options=[1,10,100,1000,10000,100000,1000000,10000000,100000000])
mmx      = input(233,    "Minimax Lookback", options=[1, 2, 3, 5, 8, 13, 21, 34, 55, 89, 144, 233, 377, 610, 987, 1597, 2584])
showVol  = input(false,  "Volume")
useold   = input(true,   "Use Old System")
method   = input("Swish", "Activation", options=["Step", "LReLU", "Swish", "None"])

scaleMinimax(X, p, min, max) =>
    hi = highest(X, p), lo = lowest(X, p)
    (max - min) * (X - lo)/(hi - lo) + min

getdiff(prc, tf) =>
    prev  = scaleMinimax((useold ? security(syminfo.tickerid, tostring(tf), prc[1], barmerge.gaps_off, barmerge.lookahead_on)
                                 : security(syminfo.tickerid, tostring(tf), prc[1])), tf, 0, 1)
    curr  = scaleMinimax((useold ? security(syminfo.tickerid, tostring(tf), hlc3, barmerge.gaps_off, barmerge.lookahead_on)
                                 : security(syminfo.tickerid, tostring(tf), hlc3)), tf, 0, 1)
    (curr/prev) - 1

relu(x) => max(x, 0)
lrelu(x, alpha) => relu(x) - alpha * relu(-x)
step(x) => x >= 0 ? 1 : -1
log2(x) => log(x) / log(2)
sigmoid(x) => 1 / (1 + exp(-x))
swish(x) => x * sigmoid(x)

f(m) => method==m

vol  = useold ? security(syminfo.tickerid, tostring(tf), volume, barmerge.gaps_off, barmerge.lookahead_on)
              : security(syminfo.tickerid, tostring(tf), volume)
obv  = cum(change(price) > 0 ? vol : change(price) < 0 ? -vol : 0*vol)
prix = showVol ? obv : price
x    = getdiff(prix, tf)
p    = f("Swish") ? swish(x) : f("Step") ? step(x) : f("LReLU") ? lrelu(x, .8) : x
th   = thresh/div
long = crossover(p, th)
short= crossunder(p, -th)

lime  = color.new(color.lime, 10), fuchsia = color.new(color.fuchsia, 10),
black = color.new(color.black, 100), gray = color.new(color.gray, 50)
bg    = long ? lime : short ? fuchsia : black
cl    = p > th ? color.green : p < -th ? color.red : color.silver

bgcolor(bg, editable=false)
plot(scaleMinimax(th, mmx, -1, 1), color=lime, editable=false, transp=0)
hline(0, linestyle=hline.style_dotted, title="base line", color=gray, editable=false)
plot(scaleMinimax(-th, mmx, -1, 1), color=fuchsia, editable=false, transp=0)
plot(scaleMinimax(p, mmx, -1, 1), color=cl, style=plot.style_histogram, transp=70, editable=false)
plot(scaleMinimax(p, mmx, -1, 1), color=cl, style=plot.style_linebr, title="prediction", transp=0, editable=false)

strategy.entry("L", true, 1, when=long)
strategy.entry("S", false, 1, when=short)

alertcondition(long, title='Long', message='Long Signal!')
alertcondition(short, title='Short', message='Short Signal!')

//*** Karobein Oscillator
per  = input(8, "Karobein Osc Lookback")

prix2 = ema(price, per)
a = ema(prix2 < prix2[1] ? prix2/prix2[1] : 0, per)
b = ema(prix2 > prix2[1] ? prix2/prix2[1] : 0, per)
c = (prix2/prix2[1])/(prix2/prix2[1] + b)
d = 2*((prix2/prix2[1])/(prix2/prix2[1] + c*a)) - 1

plot(scaleMinimax(d, mmx, -1, 1), color=color.orange, transp=0)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Scaled-Normalized-Vector-Strategy-with-Activation-Functions-ver4.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.