Seven Candlestick Oscillation Breakthrough Strategy
The seven candlestick oscillation breakthrough strategy detects the persistence up and down candlestick patterns formed by seven K-lines to determine market oscillation trends and make breakthrough operations at…
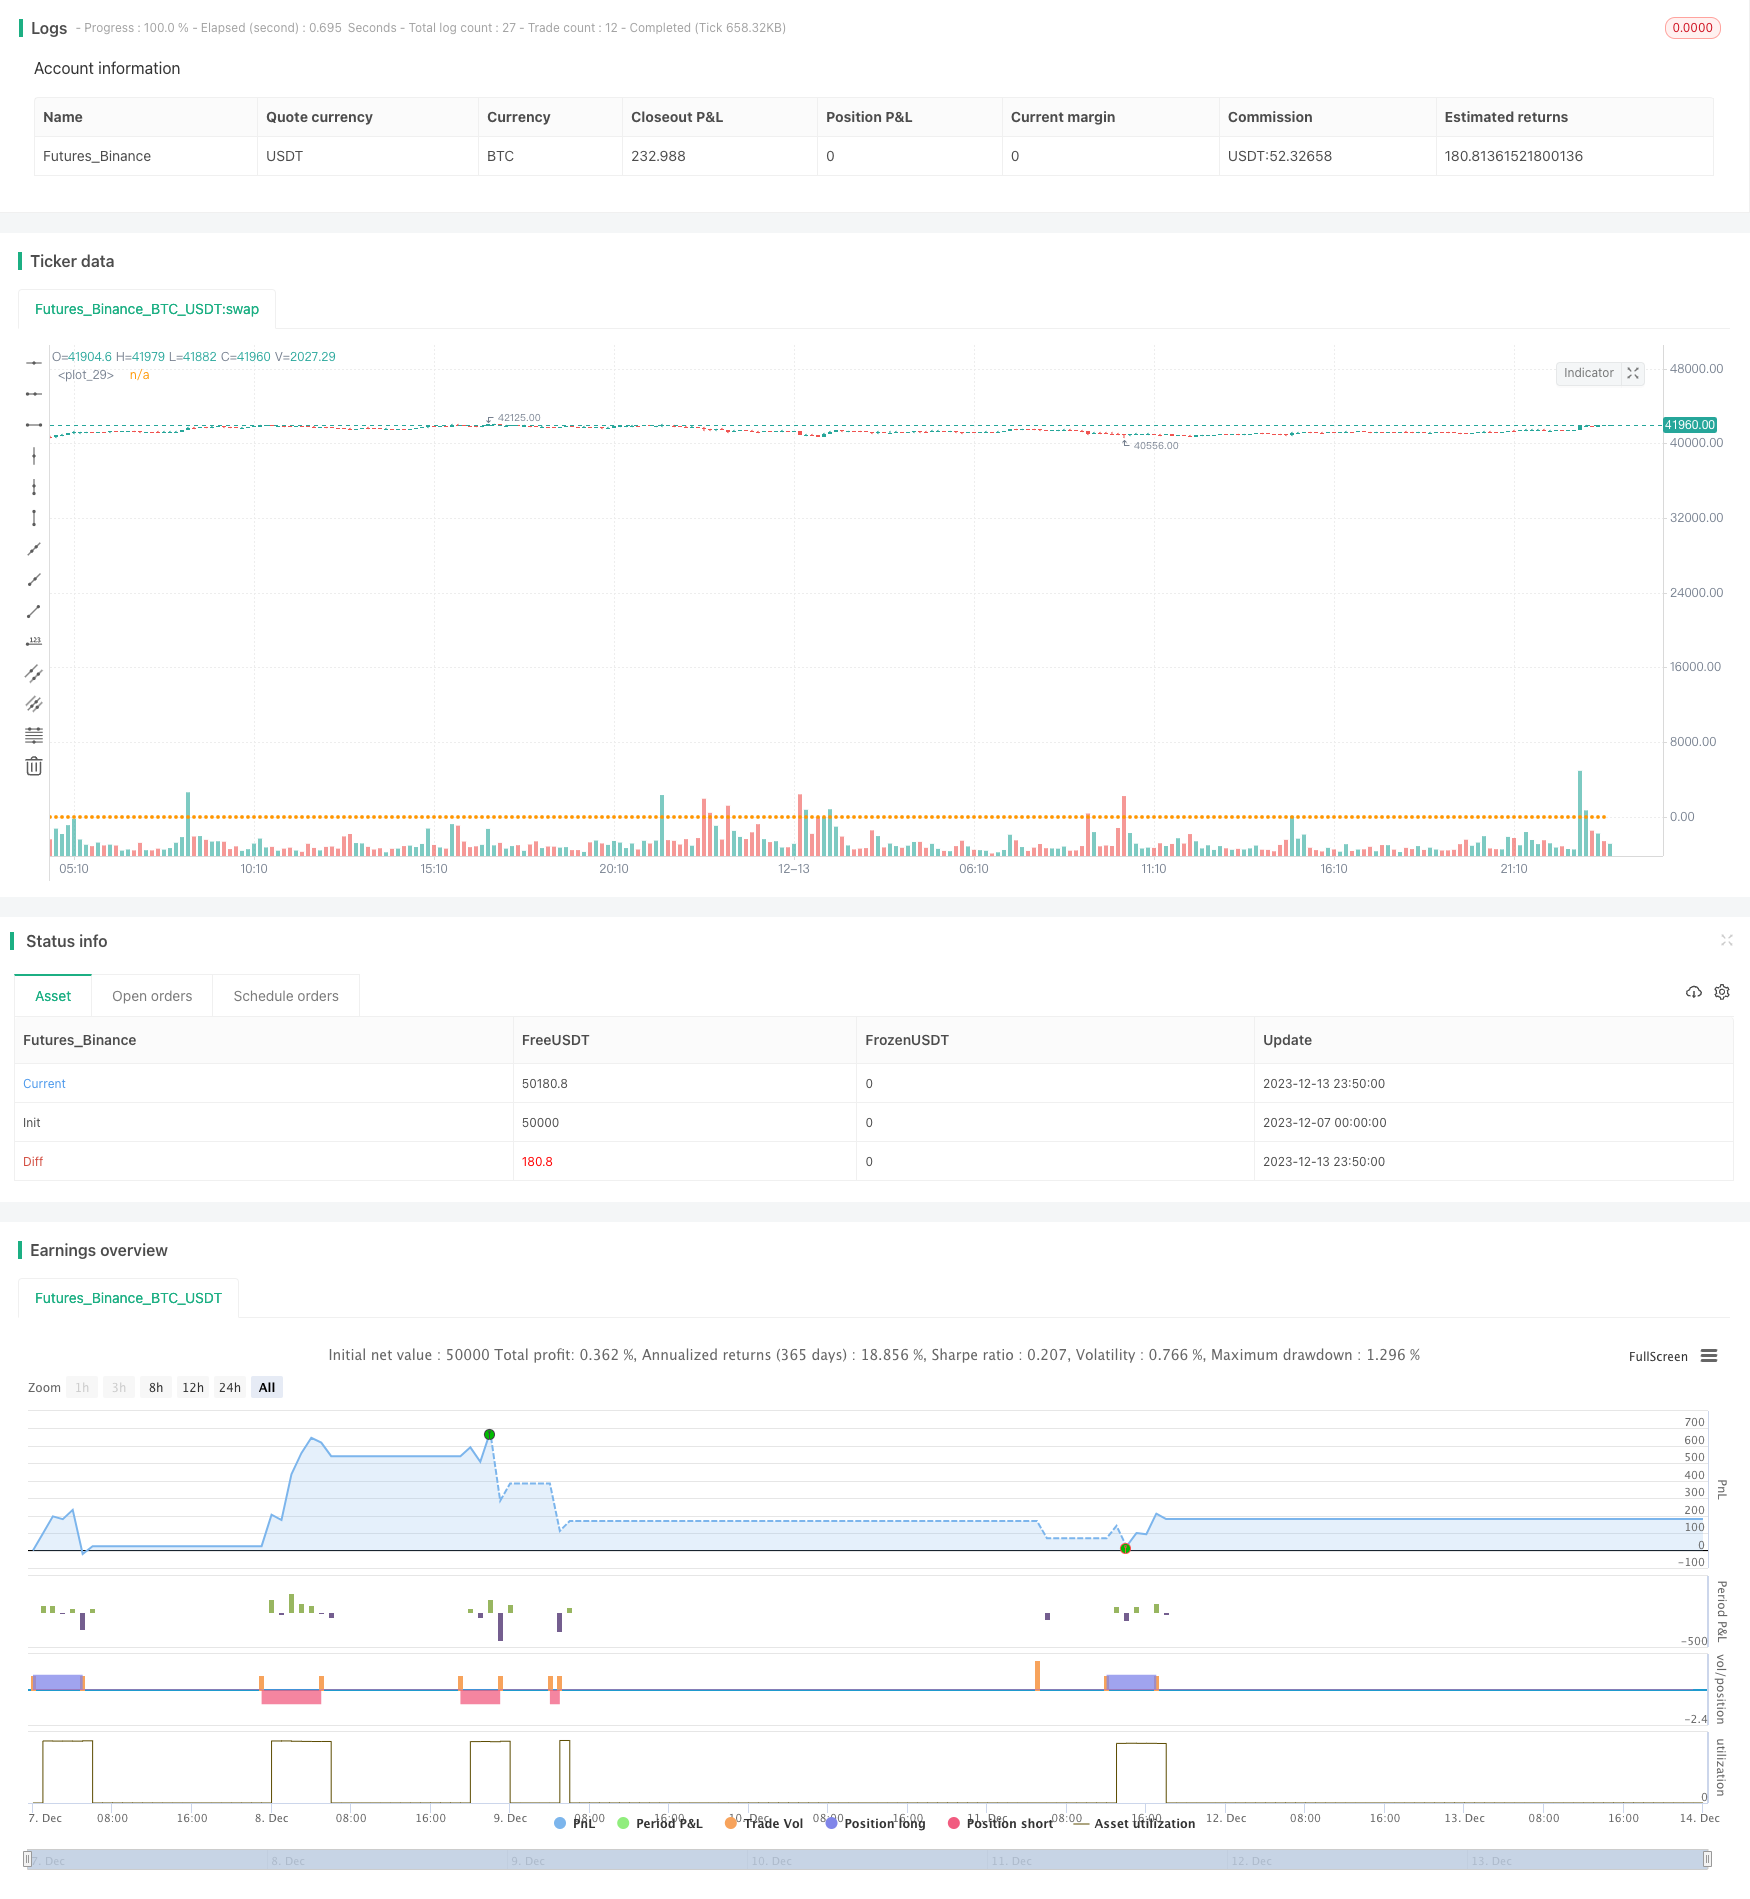
Overview
The seven candlestick oscillation breakthrough strategy detects the persistence up and down candlestick patterns formed by seven K-lines to determine market oscillation trends and make breakthrough operations at fixed times to profit.
Strategy Principle
The core logic of this strategy is based on two indicators:
- sevenReds: detecting 7 consecutive declining K-lines, defined as a downward trend in market oscillation
- sevenGreens: detecting 7 consecutive rising K-lines, defined as an upward trend in market oscillation
When sevenReds is detected, go long; when sevenGreens is detected, go short.
In addition, the strategy also closes positions at fixed times (important US data release times) every day to lock in profits.
Advantage Analysis
The seven candlestick oscillation breakthrough strategy has the following advantages:
- Captures market oscillation trends. Seven K-lines filter out market noise and improve signal quality
- Timed operation avoids systemic risks associated with large gap moves around major economic data
- Timely profit-taking locks in gains and reduces drawdowns
Risk Analysis
The seven candlestick oscillation breakthrough strategy also has some risks:
- Pattern recognition error risk. Seven K-lines cannot completely filter noise and may generate incorrect signals
- Lack of stop loss measures to limit per trade loss
- Profit-taking times cannot adjust dynamically, risk of failure to take profits in time
Corresponding solutions:
- Increase number of K-lines, raise persistence threshold
- Add moving stop loss logic
- Dynamically adjust profit-taking time based on volatility indicators
Optimization Directions
The seven candlestick oscillation breakthrough strategy can be optimized in the following aspects:
- Add multiple security pools for index/sector rotation
- Add machine learning models to aid market regime prediction
- Incorporate moving averages for optimized entry signals
- Dynamically adjust position sizing based on drawdown to control risk
Conclusion
The seven candlestick oscillation breakthrough strategy profits by capturing short-term oscillation trends in the market, while using timed execution to avoid major risks and taking profits to lock in gains. The strategy can be enhanced via multi-asset rotation, machine learning etc. It is a typical medium-frequency quantitative trading strategy.
Source Pine Script
/*backtest
start: 2023-12-07 00:00:00
end: 2023-12-14 00:00:00
period: 10m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Eliza123123

//@version=5
strategy("Breakeven Line Demo", overlay=true)

// Generic signal (not a viable strategy don't use, just some code I wrote quick for demo purposes only)
red = open > close, green = open < close
sevenReds = red and red[1] and red[2] and red[3] and red[4] and red[5] and red[6]
sevenGreens = green and green[1] and green[2] and green[3] and green[4] and green[5] and green[6]
if sevenReds
    strategy.entry('Buy', direction=strategy.long)
if sevenGreens
    strategy.entry('Sell', direction=strategy.short)
if (hour == 5 and minute == 0 ) or (hour == 11 and minute == 0) or (hour == 17 and minute == 0 ) or (hour == 23 and minute == 0)
    strategy.close_all("Close")

// Breakeven line for visualising breakeven price on stacked orders.
var breakEvenLine = 0.0
if strategy.opentrades > 0
    breakEvenLine := strategy.position_avg_price
else
    breakEvenLine := 0.0
color breakEvenLineColor = na
if strategy.position_size > 0
    breakEvenLineColor := #15FF00
if strategy.position_size < 0
    breakEvenLineColor := #FF000D
plot(breakEvenLine, color = breakEvenLine and breakEvenLine[1] > 0 ? breakEvenLineColor : na, linewidth = 2, style = plot.style_circles)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Seven-Candlestick-Oscillation-Breakthrough-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h