Shock Breakout Strategy
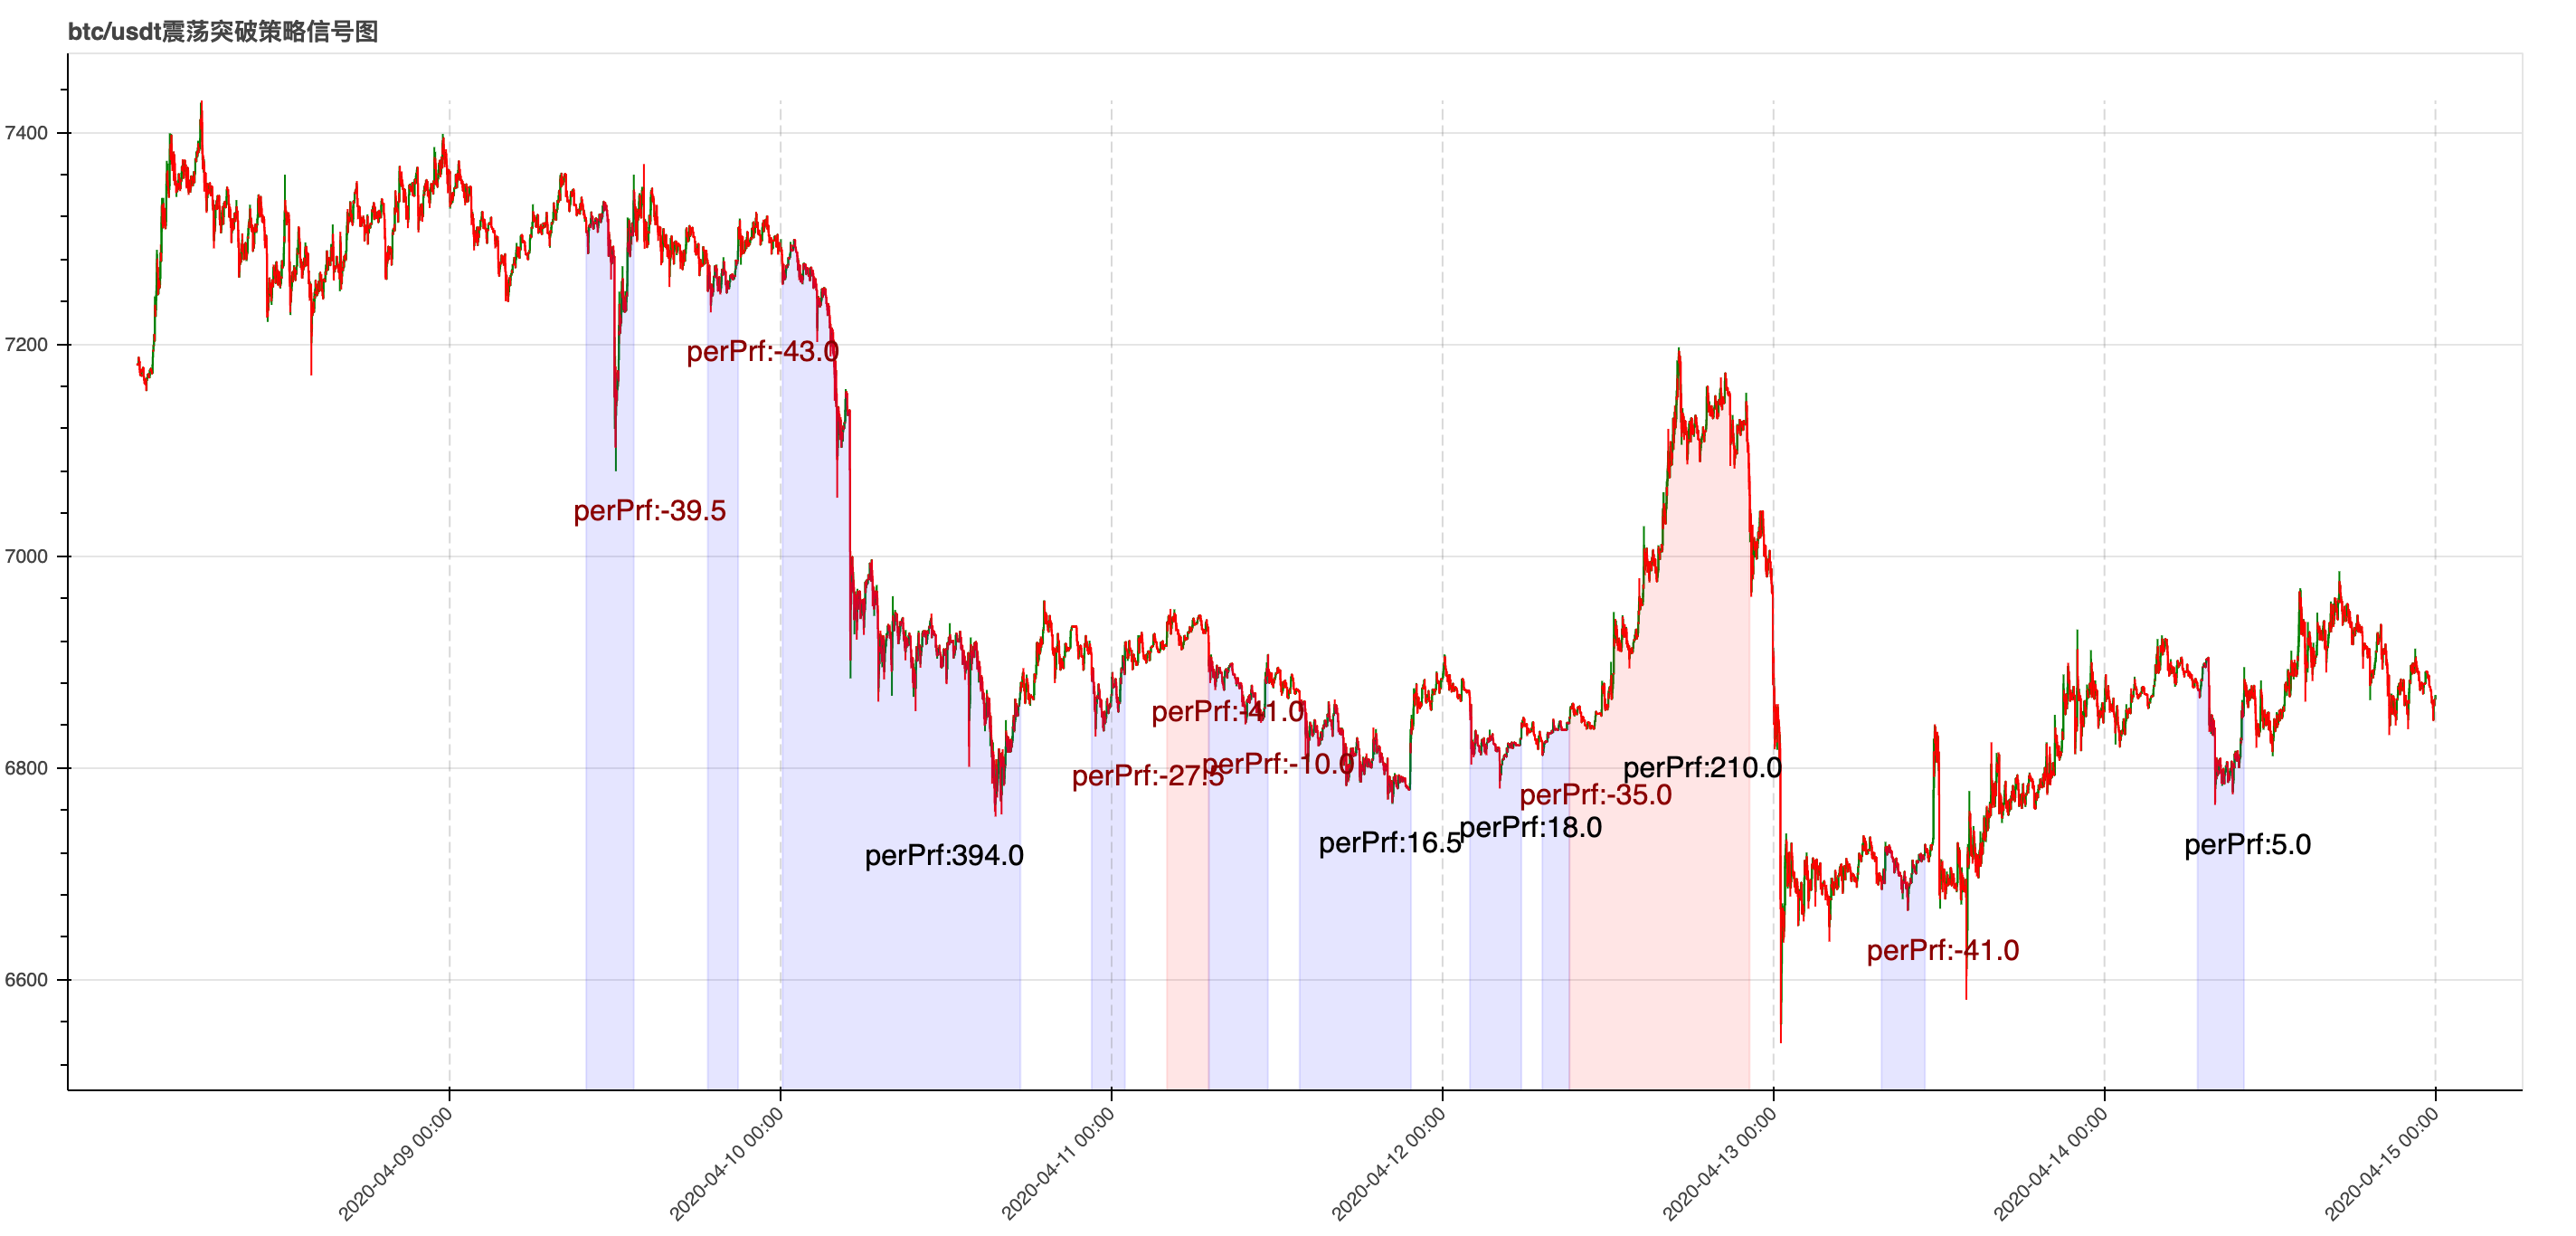
Upper band: highest price of the past 30 candlesticks Lower band: lowest price of the past 30 candlesticks range amplitude: (upper band - lower band) / (upper band + lower band)) If the range is less than the…
Strategy Description
Upper band: highest price of the past 30 candlesticks
Lower band: lowest price of the past 30 candlesticks
range amplitude: (upper band - lower band) / (upper band + lower band))
If the range is less than the threshold a, the price breaks through the upper track upwards, a buy position is opened, and the price falls below the lower track and the position is closed.
If the range is less than the threshold a, the price breaks through the upper track downwards, a sell position is opened, and the position is closed when the price breaks through the upper track.
Contact Information
If you are interested in this strategy, please+V:Irene11229 (Click on my homepage to continuously update more strategies, and also access market analysis data from several leading exchanges)
Source Python
#!/usr/bin/env python3
# -*- coding: utf-8 -*-


import json
import time

import requests
from kumex.client import Trade


def check_response_data(response_data):
    if response_data.status_code == 200:
        try:
            d = response_data.json()
        except ValueError:
            raise Exception(response_data.content)
        else:
            if d and d.get('s'):
                if d.get('s') == 'ok':
                    return d
                else:
                    raise Exception("{}-{}".format(response_data.status_code, response_data.text))
    else:
        raise Exception("{}-{}".format(response_data.status_code, response_data.text))


def get_kline(s, r, f, t, timeout=5, is_sandbox=False):
    headers = {}
    url = 'https://kitchen.kumex.com/kumex-kline/history'
    if is_sandbox:
        url = 'https://kitchen-sdb.kumex.com/kumex-kline/history'
    uri_path = url
    data_json = ''
    p = []
    if s:
        p.append("{}={}".format('symbol', s))
    if r:
        p.append("{}={}".format('resolution', r))
    if f:
        p.append("{}={}".format('from', f))
    if t:
        p.append("{}={}".format('to', t))
    data_json += '&'.join(p)
    uri_path += '?' + data_json

    response_data = requests.request('GET', uri_path, headers=headers, timeout=timeout)
    return check_response_data(response_data)


class Shock(object):

    def __init__(self):
        # read configuration from json file
        with open('config.json', 'r') as file:
            config = json.load(file)

        self.api_key = config['api_key']
        self.api_secret = config['api_secret']
        self.api_passphrase = config['api_passphrase']
        self.sandbox = config['is_sandbox']
        self.symbol = config['symbol']
        self.resolution = int(config['resolution'])
        self.valve = float(config['valve'])
        self.leverage = float(config['leverage'])
        self.size = int(config['size'])
        self.trade = Trade(self.api_key, self.api_secret, self.api_passphrase, is_sandbox=self.sandbox)


if __name__ == "__main__":
    shock = Shock()

    while 1:
        time_to = int(time.time())
        time_from = time_to - shock.resolution * 60 * 35
        data = get_kline(shock.symbol, shock.resolution, time_from, time_to, is_sandbox=shock.sandbox)
        print('now time =', time_to)
        print('symbol closed time =', data['t'][-1])
        if time_to != data['t'][-1]:
            continue
        now_price = int(data['c'][-1])
        print('closed price =', now_price)
        # high_track
        high = data['h'][-31:-1]
        high.sort(reverse=True)
        high_track = float(high[0])
        print('high_track =', high_track)

        # low_track
        low = data['l'][-31:-1]
        low.sort()
        low_track = float(low[0])
        print('low_track =', low_track)

        # interval_range
        interval_range = (high_track - low_track) / (high_track + low_track)
        print('interval_range =', interval_range)

        order_flag = 0
        # current position qty of the symbol
        position_details = shock.trade.get_position_details(shock.symbol)
        position_qty = int(position_details['currentQty'])
        print('current position qty of the symbol =', position_qty)
        if position_qty > 0:
            order_flag = 1
        elif position_qty < 0:
            order_flag = -1

        if order_flag == 1 and now_price < low_track:
            order = shock.trade.create_limit_order(shock.symbol, 'sell', position_details['realLeverage'],
                                                   position_qty, now_price)
            print('order_flag == 1,order id =', order['orderId'])
            order_flag = 0
        elif order_flag == -1 and now_price > high_track:
            order = shock.trade.create_limit_order(shock.symbol, 'buy', position_details['realLeverage'],
                                                   position_qty, now_price)
            print('order_flag == -1,order id =', order['orderId'])
            order_flag = 0

        if interval_range < shock.valve and order_flag == 0:
            if now_price > high_track:
                order = shock.trade.create_limit_order(shock.symbol, 'buy', shock.leverage, shock.size, now_price)
                print('now price > high track,buy order id =', order['orderId'])
                order_flag = 1
            if now_price < high_track:
                order = shock.trade.create_limit_order(shock.symbol, 'sell', shock.leverage, shock.size, now_price)
                print('now price < high track,sell order id =', order['orderId'])
order_flag = -1Published by 巴啦啦小魔仙 on the FMZ strategy square · last modified 2021-03-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Shock-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- TurtlePython · Breakout
- Turtle Strategy BTC Spot VersionPython · Breakout
- Keltner Channel Breakout Stop Loss Plus Profit 10 I.e. Long Term Holding Strategy V23 Dev Multi CyclePython · Breakout
- bollmabollPython · Breakout
- Bollinger Moving Average Breakthrough Vnpy Botvs Implementation VersionPython · Breakout
- WR Breakthrough MartinPython · Breakout