Strategy vault / Mean reversion
Significant Pivot Points Reversal Strategy
This strategy optimizes the traditional pivot points reversal strategy by calculating the ATR and setting ATR filters to eliminate insignificant pivot points, only trading on truly significant ones.
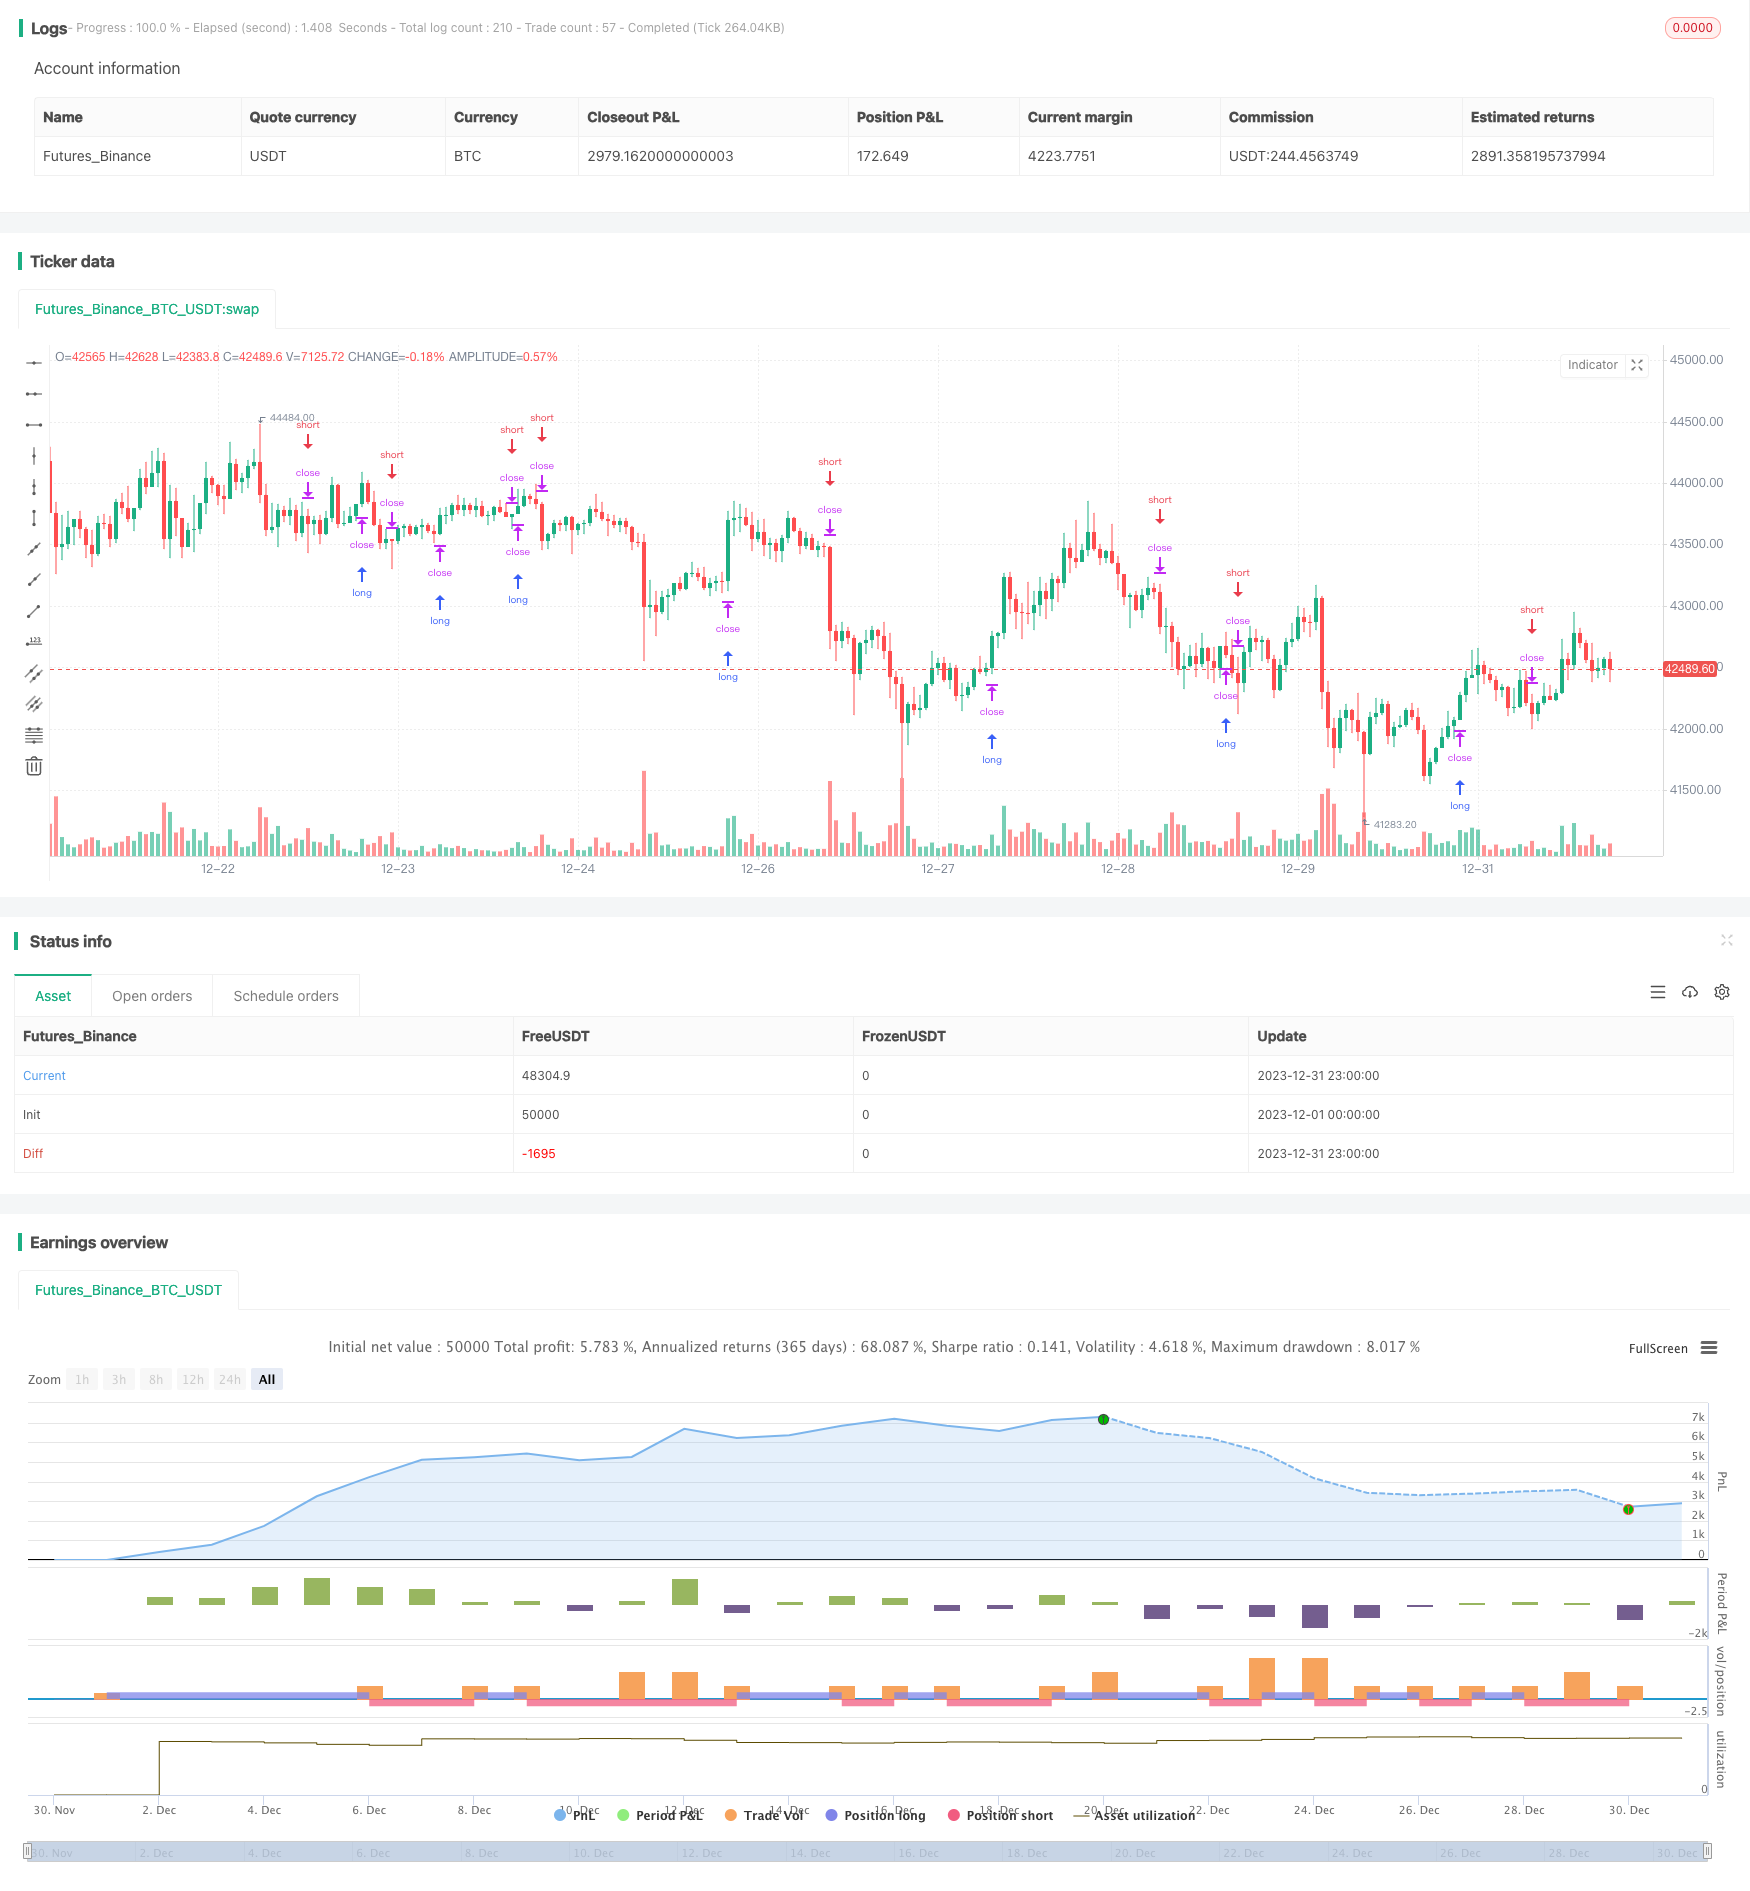
Overview
This strategy optimizes the traditional pivot points reversal strategy by calculating the ATR and setting ATR filters to eliminate insignificant pivot points, only trading on truly significant ones.
Strategy Logic
The core logic is to identify significant peak and trough pivot points. The key steps to calculate significant peak pivots are:
- Calculate ATR and set the ATR filter factor atr_mult.
- Traverse a certain number of bars on the left (set by leftBars), if the peak pivot is higher than any high + ATR*atr_mult on the left, the pivot is invalid.
- Traverse a certain number of bars on the right (set by rightBars), if the peak pivot is higher than any high + ATR*atr_mult on the right, the pivot is invalid.
- If the peak pivot remains valid after the above tests, return it as an important peak pivot.
The logic for calculating significant trough pivots is similar.
After obtaining the significant pivots, go short when price breaks an important peak pivot, and go long when it breaks an important trough pivot.
Advantage Analysis
The main advantages of this strategy are:
- The ATR and atr_mult filter can eliminate insignificant fluctuations and only trade truly significant pivots, avoiding unnecessary trades.
- The dynamic ATR parameter can adjust the trading range automatically in volatile markets, preventing over-trading.
- Pivot points reversal itself has relatively high win rate and profitability.
Risk Analysis
The main risks are:
- Improper ATR parameters may filter out too many valid trades. If ATR is too high, valid pivots could be eliminated.
- Risk of being trapped still exists, need to set stop loss to control risk.
- Reversal strategies are sensitive to transaction costs, reasonable stop loss and take profit should be set.
To control the above risks, optimize from the following aspects:
- Optimize ATR parameters to ensure enough trading opportunities.
- Set reasonable stop loss and take profit ratios.
- Adjust position sizing to reduce transaction cost impact.
Optimization Directions
Further optimization directions include:
Combining with other indicators to determine market regime, avoiding trading reversals in trending markets. Consider MACD, KDJ etc.
Adding machine learning algorithms to auto-optimize parameters. Methods like genetic algorithms, random forest can be used to find optimum parameter sets.
Training models using quantitative data to find optimal ATR range. More historical data improves parameter selection accuracy.
Consider combining with other strategies, utilizing strengths of different strategy types. For example, combining with trend following strategy, reverse during ranging, trend-follow during sustained trends.
Conclusion
This significant pivot reversal strategy filters out meaningless minor fluctuations by calculating ATR and setting filters. Only trading reversals on significant pivots can effectively improve strategy profitability. Meanwhile, it also increases parameter optimization difficulty. The optimal parameters need to be found by comprehensive consideration of ATR range, stop loss/take profit ratios etc. If optimized thoroughly, it can become a highly efficient and stable short-term trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 4 | PP Left Bars |
| v_input_2 | 2 | PP Right Bars |
| v_input_3 | 14 | ATR Length |
| v_input_4 | 0.1 | ATR Mult |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("QuantNomad - Significant Pivot Reversal Strategy", shorttitle = "SPPS", overlay=true)

// Inputs
leftBars   = input(4,   title = 'PP Left Bars')
rightBars  = input(2,   title = 'PP Right Bars')
atr_length = input(14,  title = 'ATR Length')
atr_mult   = input(0.1, title = 'ATR Mult')

// Pivot High Significant Function
pivotHighSig(left, right) =>
    pp_ok = true
    atr   = atr(atr_length)

    for i = 1 to left
        if (high[right] < high[right+i] + atr * atr_mult)
            pp_ok := false
    for i = 0 to right-1
        if (high[right] < high[i] + atr * atr_mult)
            pp_ok := false

    pp_ok ? high[right] : na

// Pivot Low Significant Function
pivotLowSig(left, right) =>
    pp_ok = true
    atr   = atr(atr_length)

    for i = 1 to left
        if (low[right] > low[right+i] - atr * atr_mult)
            pp_ok := false
    for i = 0 to right-1
        if (low[right] > low[i] - atr * atr_mult)
            pp_ok := false

    pp_ok ? low[right] : na


swh = pivotHighSig(leftBars, rightBars)
swl = pivotLowSig (leftBars, rightBars)

swh_cond = not na(swh)

hprice = 0.0
hprice := swh_cond ? swh : hprice[1]

le = false
le := swh_cond ? true : (le[1] and high > hprice ? false : le[1])

if (le)
    strategy.entry("PivRevLE", strategy.long, comment="PivRevLE", stop=hprice + syminfo.mintick)

swl_cond = not na(swl)

lprice = 0.0
lprice := swl_cond ? swl : lprice[1]


se = false
se := swl_cond ? true : (se[1] and low < lprice ? false : se[1])

if (se)
strategy.entry("PivRevSE", strategy.short, comment="PivRevSE", stop=lprice - syminfo.mintick)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Significant-Pivot-Points-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic MACD and Ichimoku Cloud Trading StrategyPine Script · Mean reversion · 1h
- Multi Timeframe Gold Reversal Tracking StrategyPine Script · Mean reversion · 2h
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d
- Mean Reversion Trading Strategy Based on Bollinger Bands and Golden RatioPine Script · Mean reversion · 1h
- RSI Indicator Long Short Separation Trading StrategyPine Script · Mean reversion · 3h
- RSI Divergence StrategyPine Script · Mean reversion · 30m