Simple Arithmetic Contract Grid
The parameters are very simple, they areBTCFor example, when you reach the area where you open a long position, close short to buy a bottom position and open a long position; when you reach the area where you open a…
The parameters are very simple, they areBTCFor example, when you reach the area where you open a long position, close short to buy a bottom position and open a long position; when you reach the area where you open a short position, you buy a bottom position and open a short position, repeating this cycle
Obviously, in the crypto world, in the long run, any complex model cannot outperform a mindless grid strategy
Wealth code is brainless grid+Reckless all-in local dog
Hopefully, like the earliest Martin, this is the simplest and most brutal yet profitable strategy
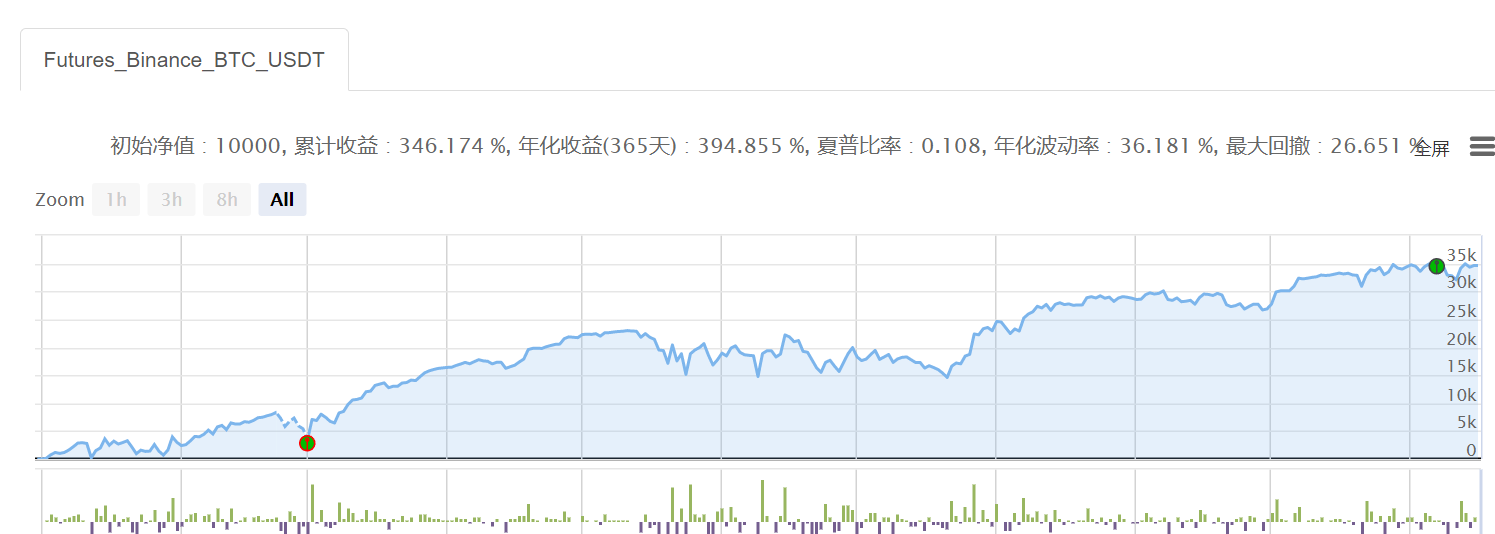
Parameters
| Name | Default | What it controls |
|---|---|---|
| M | 20 | Leverage Size |
| H | 50 | Initial base position quantity |
| n1 | true | Quantity per single grid trade |
| grid | 200 | Spacing per single grid trade |
| xia | 35000 | Open multiple points |
| shang | 60000 | Open short position |
Source Python
'''backtest
start: 2021-01-01 00:00:00
end: 2021-11-17 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":2500}]
args: [["H",30],["n1",0.001],["grid",300],["xia",50000]]
'''

def CancelPendingOrders():
    orders = _C(exchanges[0].GetOrders)
    if len(orders)>0:
        for j in range(len(orders)):
            exchanges[0].CancelOrder(orders[j].Id, orders[j])
            j=j+1

def main():
    exchange.SetContractType('swap')
    exchange.SetMarginLevel(M)
    currency=exchange.GetCurrency()
    if _G('buyp') and _G('sellp'):
        buyp=_G('buyp')
        sellp=_G('sellp')
        Log('Read grid prices')
    else:
        ticker=exchange.GetTicker()
        buyp=ticker["Last"]-grid
        sellp=ticker["Last"]+grid
        _G('buyp',buyp)
        _G('sellp',sellp)
        Log('Initialize grid data')
    while True:
            account=exchange.GetAccount()
            ticker=exchange.GetTicker()
            position=exchange.GetPosition()
            orders=exchange.GetOrders()
            if len(position)==0:
                if ticker["Last"]>shang:
                    exchange.SetDirection('sell')
                    exchange.Sell(-1,n1*H)
                    Log(currency,'Reached short opening area,Buy short base position')

                else:
                    exchange.SetDirection('buy')
                    exchange.Buy(-1,n1*H)
                    Log(currency,'Reached long opening area,Buy long base position')
            if len(position)==1:
                if position[0]["Type"]==1:
                    if ticker["Last"]<xia:
                        Log(currency,'Take profit and reverse all short orders')
                        exchange.SetDirection('closesell')
                        exchange.Buy(-1,position[0].Amount)
                    else:
                        orders=exchange.GetOrders()
                        if len(orders)==0:
                            exchange.SetDirection('sell')
                            exchange.Sell(sellp,n1)
                            exchange.SetDirection('closesell')
                            exchange.Buy(buyp,n1)
                        if len(orders)==1:
                            if orders[0]["Type"]==1: #take profit transaction
                                Log(currency,'Grid reduction,Current number of copies:',position[0].Amount)
                                CancelPendingOrders()
                                buyp=buyp-grid
                                sellp=sellp-grid
                                LogProfit(account["Balance"])
                            if orders[0]["Type"]==0:
                                Log(currency,'Grid increase position,Current number of copies:',position[0].Amount)
                                CancelPendingOrders()
                                buyp=buyp+grid
                                sellp=sellp+grid
                                LogProfit(account["Balance"])

                if position[0]["Type"]==0:
                    if ticker["Last"]>float(shang):
                        Log(currency,'Take profit and reverse all long orders')
                        exchange.SetDirection('closebuy')
                        exchange.Sell(-1,position[0].Amount)
                    else:
                        orders=exchange.GetOrders()
                        if len(orders)==0:
                            exchange.SetDirection('buy')
                            exchange.Buy(buyp,n1)
                            exchange.SetDirection('closebuy')
                            exchange.Sell(sellp,n1)
                        if len(orders)==1:
                            if orders[0]["Type"]==0: #take profit transaction
                                Log(currency,'Grid reduction,Current number of copies:',position[0].Amount)
                                CancelPendingOrders()
                                buyp=buyp+grid
                                sellp=sellp+grid
                                LogProfit(account["Balance"])
                            if orders[0]["Type"]==1:
                                Log(currency,'Grid increase position,Current number of copies:',position[0].Amount)
                                CancelPendingOrders()
                                buyp=buyp-grid
                                sellp=sellp-grid
                                LogProfit(account["Balance"])
Published by 恐龙宝宝 on the FMZ strategy square · last modified 2021-11-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a grid bot with inventory caps and order deduplication from strategies/Simple-Arithmetic-Contract-Grid.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.