Simple Momentum Strategy Based on SMA EMA and Volume
This is a simple intraday momentum strategy that only goes long and does not short. It utilizes SMA, EMA and volume indicators to attempt entering the market at the optimal timing when both price and momentum are…
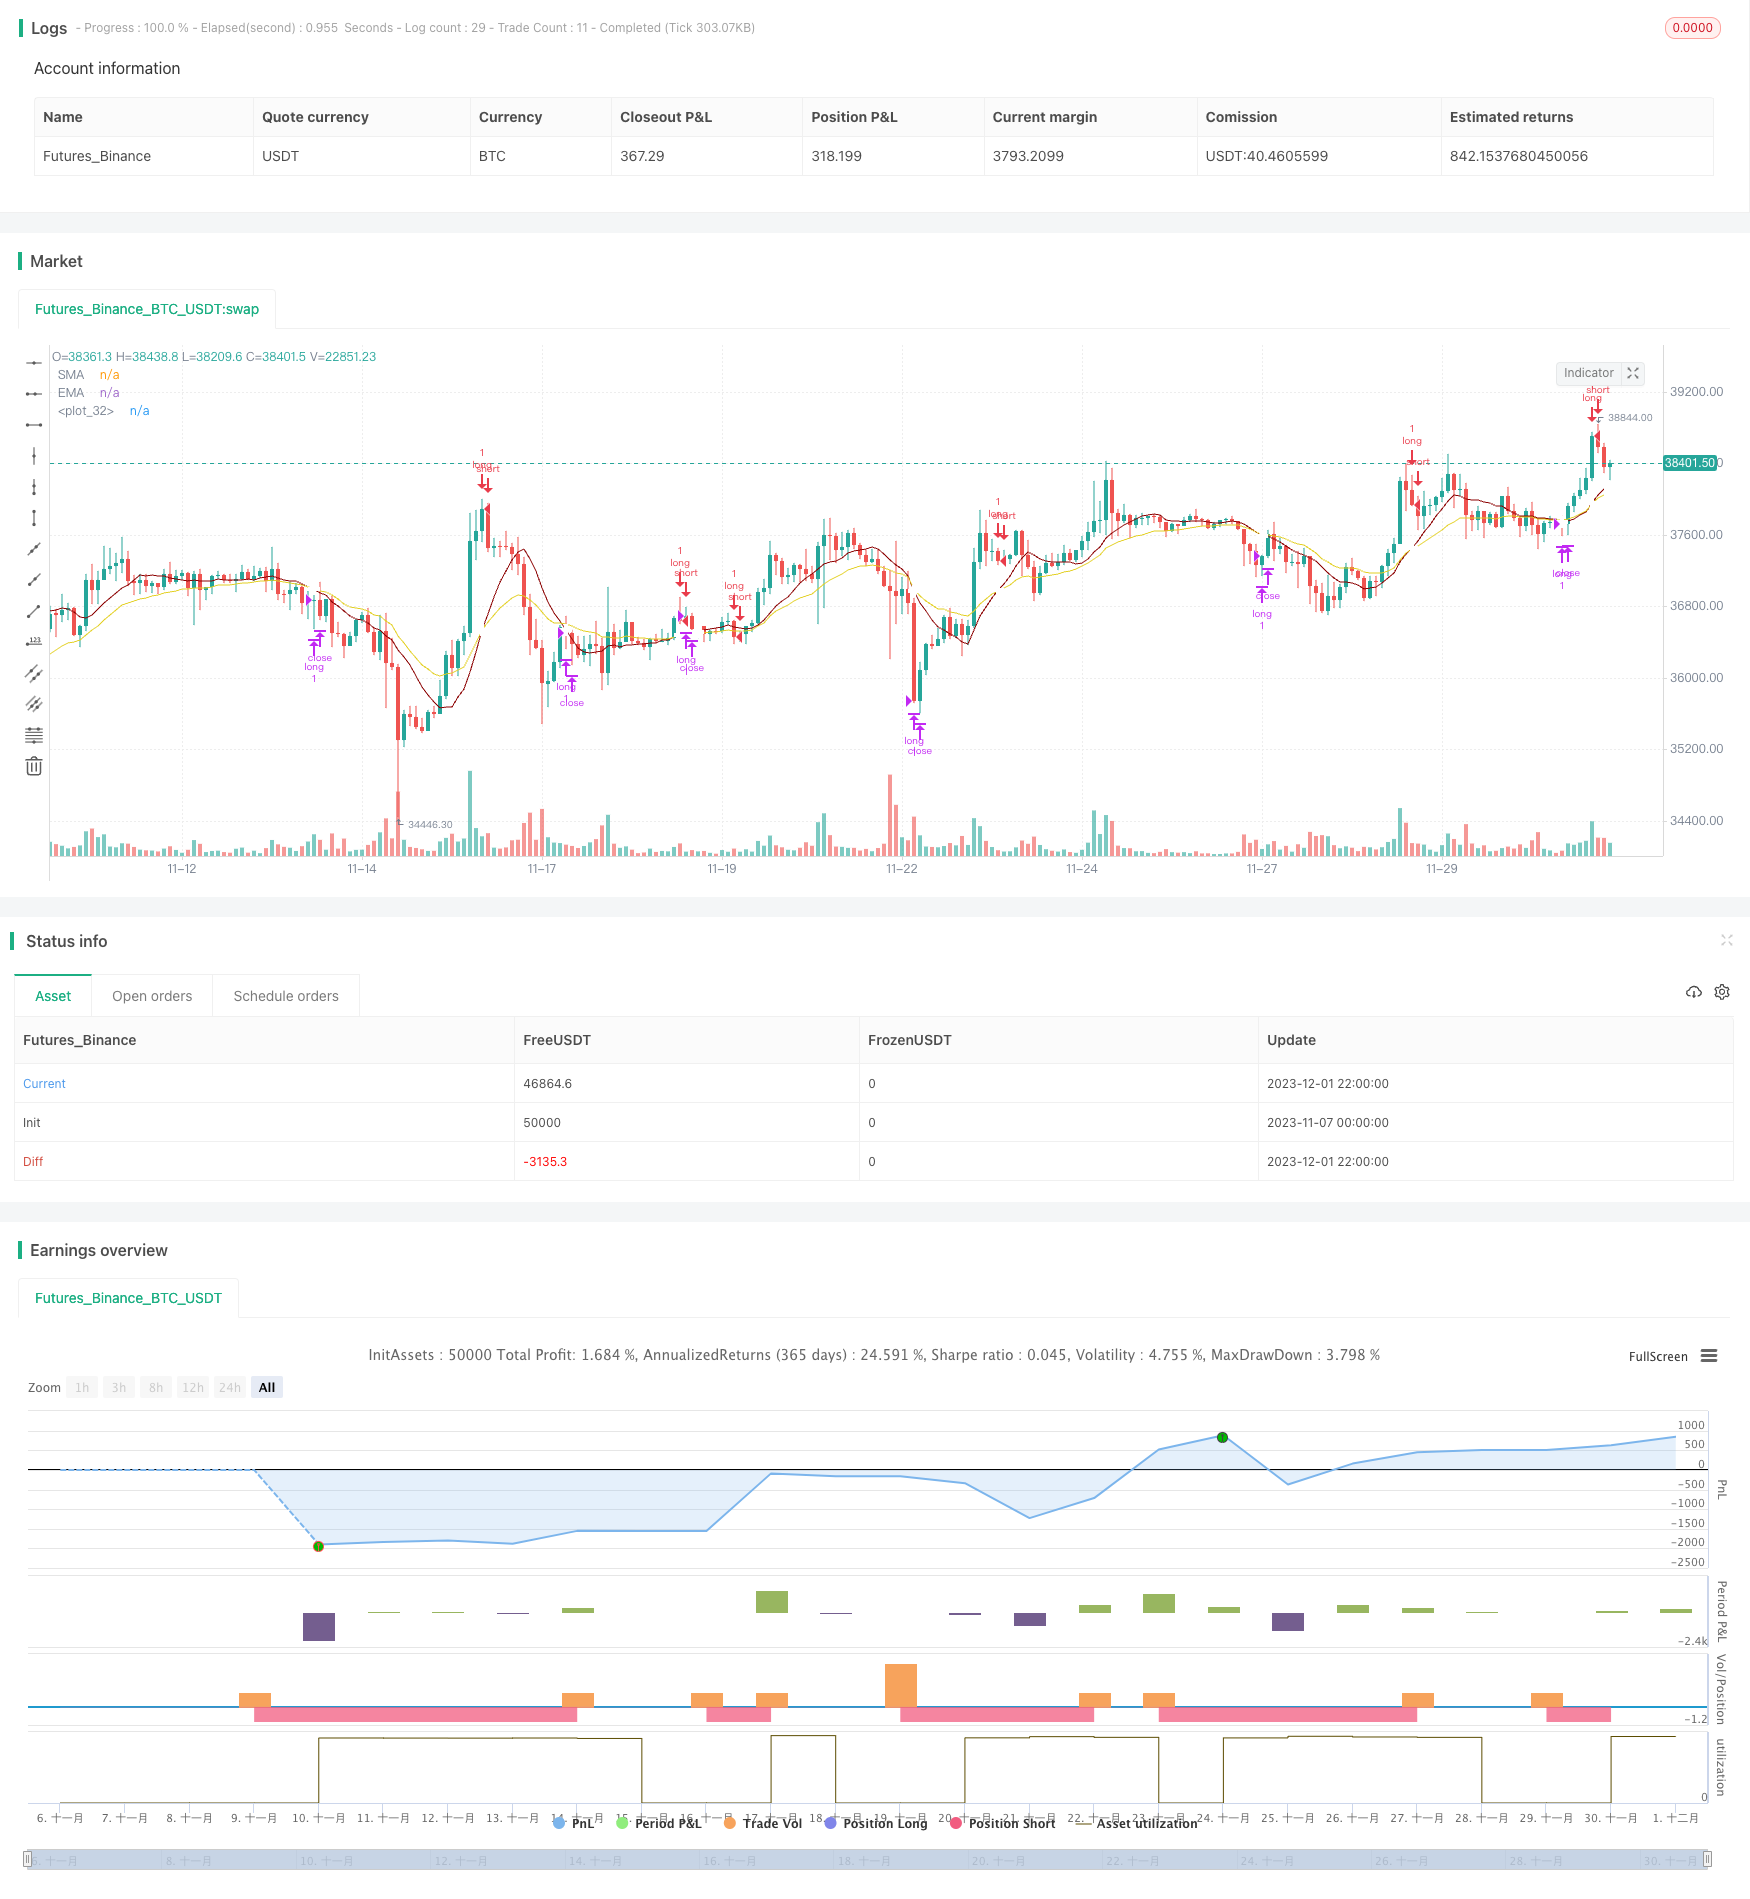
Overview
This is a simple intraday momentum strategy that only goes long and does not short. It utilizes SMA, EMA and volume indicators to attempt entering the market at the optimal timing when both price and momentum are trending up. Its advantage is being simple while having some trend recognition capability.
Strategy Principle
The entry signal logic is: when SMA is higher than EMA, and there is a consecutive 3-bar or 4-bar uptrend pattern, with the lowest price of the middle bars being higher than the open price of the starter uptrend bar, an entry signal is generated.
The exit signal logic is: when SMA crosses below EMA, an exit signal is generated.
This strategy only goes long and does not short. Its entry and exit logic has some capability in recognizing persistent uptrends.
Advantage Analysis
The advantages of this strategy:
The logic is simple and easy to understand and implement;
Utilizes common technical indicators like SMA, EMA and volume for flexibility in parameter tuning;
Has some capability in catching some opportunities during persistent uptrends.
Risk Analysis
The risks of this strategy:
Inability to detect downtrends or consolidation markets, leading to large drawdowns;
Inability to utilize shorting opportunities, unable to hedge against downtrends, missing good profit chances;
Volume indicator does not work well on high frequency data, parameters need adjustment;
Can use stop loss to control risks.
Optimization Directions
This strategy can be optimized in the following aspects:
Adding shorting capability for mean reversion opportunities;
Using more advanced indicators like MACD and RSI for better trend detection;
Optimizing stop loss logic to reduce drawdowns;
Tuning parameters and testing different timeframes to find optimal parameter sets.
Conclusion
In summary this is a very simple trend following strategy utilizing SMA, EMA and volume for entry timing. Its advantage is being simple and easy to implement, good for beginners to learn, but it cannot detect consolidation or downtrends and has risks. Improvements can be made by introducing shorting, optimizing indicators and stop loss etc.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | SMA (small length) |
| v_input_2 | 20 | EMA (large length) |
| v_input_3 | 10 | Volume Trigger |
Source Pine Script
/*backtest
start: 2023-11-07 00:00:00
end: 2023-12-02 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © slip_stream

//@version=4

// Simple strategy for riding the momentum and optimising the timings of truer/longer price moves upwards for an long posistions on a daily basis (can be used, but with less effect
// on other time frames. Volume settings would have to be adjusted by the user accordingly. (short positions are not used).
// This strategy has default settings of a short(er) SMA of 10, a long(er) EMA of 20, and Volume trigger of 10 units and above. All these settings can be changed by the user
// using the GUI settings and not having to change the script.

// The strategy will only open a long position when there is a clear indication that price momentum is upwards through the SMA moving and remaining above the EMA (mandatory) and price period indicators
// of either 1) a standard 3 bar movement upwards, 2) a standard but "aggressive" 3 or 4 bar play where the low of the middle resting bars can be equal to or higher than (i.e. not
// the more standard low of about half) of the opening of the ignition bar. The "aggression" of the 3/4 bar play was done in order to counteract the conservatisme of having a mandatory
// SMA remaining higher than the EMA (this would have to be changed in the script by the user if they want to optimise to their own specifications. However, be warned, all programmatic
// settings for the maximum acceptable low of the middle resting bars runs a risk of ignoring good entry points due to the low being minutely e.g. 0.01%, lower than the user defined setting)


strategy(title = "Simple Momentum Strategy Based on SMA, EMA and Volume", overlay = true, pyramiding = 1, initial_capital = 100000, currency = currency.USD)


// Obtain inputs
sma_length = input(defval = 10, minval=1, type = input.integer, title = "SMA (small length)")
ema_length = input(defval = 20,minval=1, type = input.integer, title = "EMA (large length)")
volume_trigger = input(defval = 10, title = "Volume Trigger", type = input.integer)
sma_line = sma(close, sma_length)
ema_line = ema(close, ema_length)


// plot SMA and EMA lines with a cross for when they intersect
plot(sma_line, color = #8b0000, title = "SMA")
plot(ema_line, color = #e3d024, title = "EMA")
plot(cross(sma_line, ema_line) ? sma_line : na, style = plot.style_cross, linewidth = 4, color = color.white)


// Create variables
// variables to check if trade should be entered
//three consecutive bar bar moves upwards and volume of at least one bar is more than 10
enter_trade_3_bar_up = sma_line > ema_line and close[1] >= close [2] and close[3] >= close[4] and close[2] >= close[3] and (volume[1] >= volume_trigger or volume[2] >= volume_trigger or volume[3] >= volume_trigger)
// aggressive three bar play that ensures the low of the middle bar is equal to or greater than the open of the instigator bar. Volume is not taken into consideration (i.e. aggressive/risky)
enter_3_bar_play = sma_line > ema_line and close[1] > close[3] and low[2] >= open[3]
// aggressive four bar play similar to the 3 bar play above
enter_4_bar_play = sma_line > ema_line and close[1] > close[4] and low[2] >= open[4]
trade_entry_criteria = enter_trade_3_bar_up or enter_3_bar_play or enter_4_bar_play // has one of the trade entry criterias returned true?

// exit criteria for the trade: when the sma line goes under the ema line
trade_exit_criteria = crossunder (sma_line, ema_line)


if (year >= 2019)
    strategy.entry(id = "long", long = true, qty = 1, when = trade_entry_criteria)
    strategy.close(id = "long", when = trade_exit_criteria, qty = 1)
    // for when you want to brute force close all open positions: strategy.close_all (when = trade_exit_criteria)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Simple-Momentum-Strategy-Based-on-SMA-EMA-and-Volume.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- MACD Momentum Indicator Backtest StrategyPine Script · Momentum · 1h
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Multi factor Adaptive Momentum Tracking StrategyPine Script · Momentum · 3m
- Dual Momentum Oscillator Smart Timing Trading StrategyPine Script · Momentum · 1h