Single Point Moving Average Breakout Strategy
The single point moving average breakout strategy is a quantitative trading strategy based on the Chande Momentum Oscillator. It detects when the market is in a consolidation phase by calculating the momentum changes…
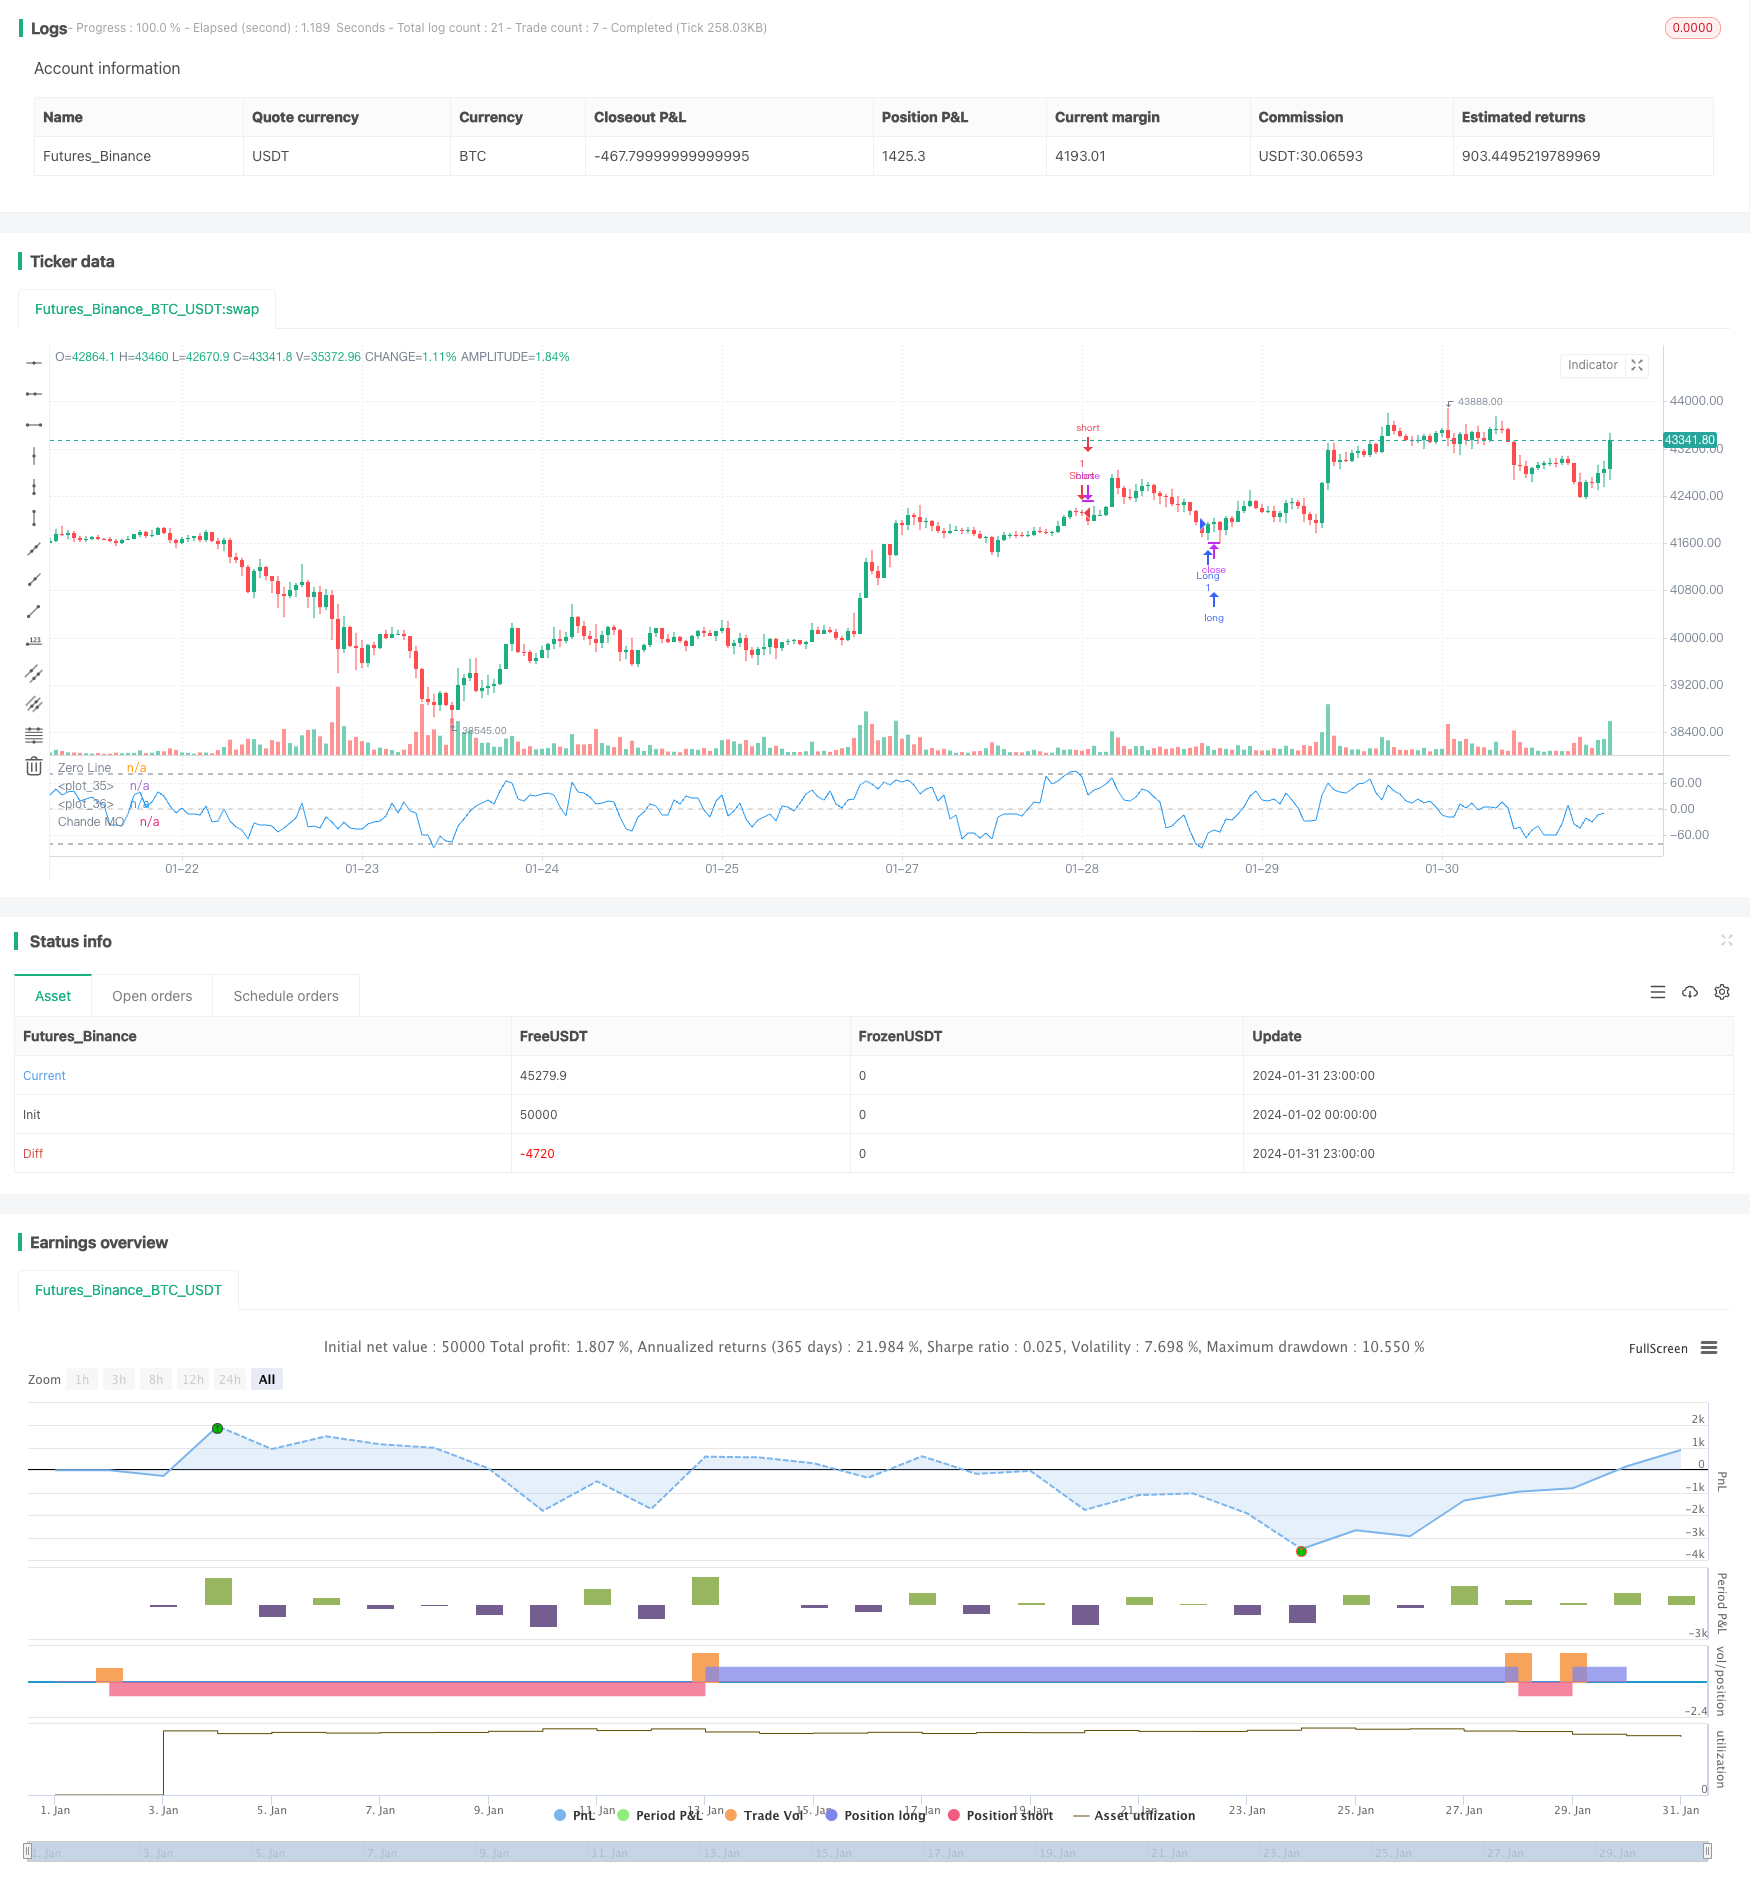
Overview
The single point moving average breakout strategy is a quantitative trading strategy based on the Chande Momentum Oscillator. It detects when the market is in a consolidation phase by calculating the momentum changes of price. When the Chande Momentum line crosses above the buy line or falls below the sell line, long or short trades will be executed accordingly.
Strategy Logic
The strategy first calculates the price momentum change momm, then separates it into positive momentum m1 and negative momentum m2. Next, it sums the positive and negative momentum over a lookback period into sm1 and sm2. Finally, the Chande Momentum Oscillator chandeMO is derived. The indicator oscillates around the zero line. Readings above zero indicate stronger upward momentum, while readings below zero indicate stronger downward momentum.
When the Chande Momentum line crosses above the buy line from lower levels, it signals that price is breaking out of a downtrend and ready to start an uptrend. The strategy will go long. When the line falls below the sell line from higher levels, short positions will be initiated.
Advantage Analysis
- The strategy is able to identify turning points from downtrend to consolidation to uptrend, allowing entries at low prices and exits at high prices.
- The Chande Momentum Oscillator considers both magnitude and rate of price changes, making it very effective for trend detection.
- The strategy logic is simple and easy to implement.
Risk Analysis
- The Chande Momentum Oscillator is sensitive to input parameters. Different parameter tuning can lead to vastly different trading signals and results.
- Static buy and sell line settings may also introduce excessive false signals.
- The lack of stop loss means that losing trades can accumulate large losses.
Some ways to improve include using dynamic buy/sell lines, filtering signals with other indicators, and implementing stop loss to control risks.
Optimization Directions
- Test different parameter settings to find optimal values
- Adopt dynamic buy and sell lines
- Add additional filters with other indicators
- Incorporate stop loss logic to cut losses
Conclusion
The single point moving average breakout strategy identifies trend turning points from downtrend to consolidation to uptrend using the Chande Momentum Oscillator, allowing low buy high sell trading. Despite being simple and intuitive, enhancements in parameter tuning, signal filtering and risk control can further improve performance. Overall, it serves as an effective tool for quantitative traders to determine trend reversals.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2021 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | 10 | Backtest Start Day |
| v_input_4 | 999999 | Backtest Stop Year |
| v_input_5 | 9 | Backtest Stop Month |
| v_input_6 | 26 | Backtest Stop Day |
| v_input_7 | 9 | length |
| v_input_8_close | 0 | Price: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_9 | -80 | buyline |
| v_input_10 | 80 | sellline |
Source Pine Script
/*backtest
start: 2024-01-02 00:00:00
end: 2024-02-01 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4

//* Backtesting Period Selector | Component *//
//* https://www.tradingview.com/script/eCC1cvxQ-Backtesting-Period-Selector-Component *//
//* https://www.tradingview.com/u/pbergden/ *//
//* Modifications made *//
testStartYear = input(2021, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(10, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(999999, "Backtest Stop Year")
testStopMonth = input(9, "Backtest Stop Month")
testStopDay = input(26, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

testPeriod() => true
/////////////// END - Backtesting Period Selector | Component ///////////////
strategy(title="Chande Momentum Strat", shorttitle="ChandeMO Strat", format=format.price, precision=2)
length = input(9, minval=1)
src = input(close, "Price", type = input.source)
momm = change(src)
f1(m) => m >= 0.0 ? m : 0.0
f2(m) => m >= 0.0 ? 0.0 : -m
m1 = f1(momm)
m2 = f2(momm)
sm1 = sum(m1, length)
sm2 = sum(m2, length)
percent(nom, div) => 100 * nom / div
chandeMO = percent(sm1-sm2, sm1+sm2)
plot(chandeMO, "Chande MO", color=color.blue)
hline(0, color=#C0C0C0, linestyle=hline.style_dashed, title="Zero Line")
buyline= input(-80)
sellline= input(80)
hline(buyline, color=color.gray)
hline(sellline, color=color.gray)

if testPeriod()
    if crossover(chandeMO, buyline)
        strategy.entry("Long", strategy.long, alert_message="a=ABCD b=buy e=binanceus q=1.2 s=uniusd")
    //    strategy.exit(id="Long Stop Loss", stop=strategy.position_avg_price*0.8) //20% stop loss

    if crossunder(chandeMO, sellline)
        strategy.entry("Short", strategy.short, alert_message="a=ABCD b=sell e=binanceus q=1.2 s=uniusd")
    //    strategy.exit(id="Short Stop Loss", stop=strategy.position_avg_price*1.2) //20% stop loss

//      remember to alert as    {{strategy.order.alert_message}}
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Single-Point-Moving-Average-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h