Strategy vault / Trend following
Slow Stochastic Trend Following Strategy
This is a trend following strategy based on slow stochastic indicator. It uses a long period K line moving average to smooth the slow stochastic and filters out market noise to lock in major trends. The strategy…
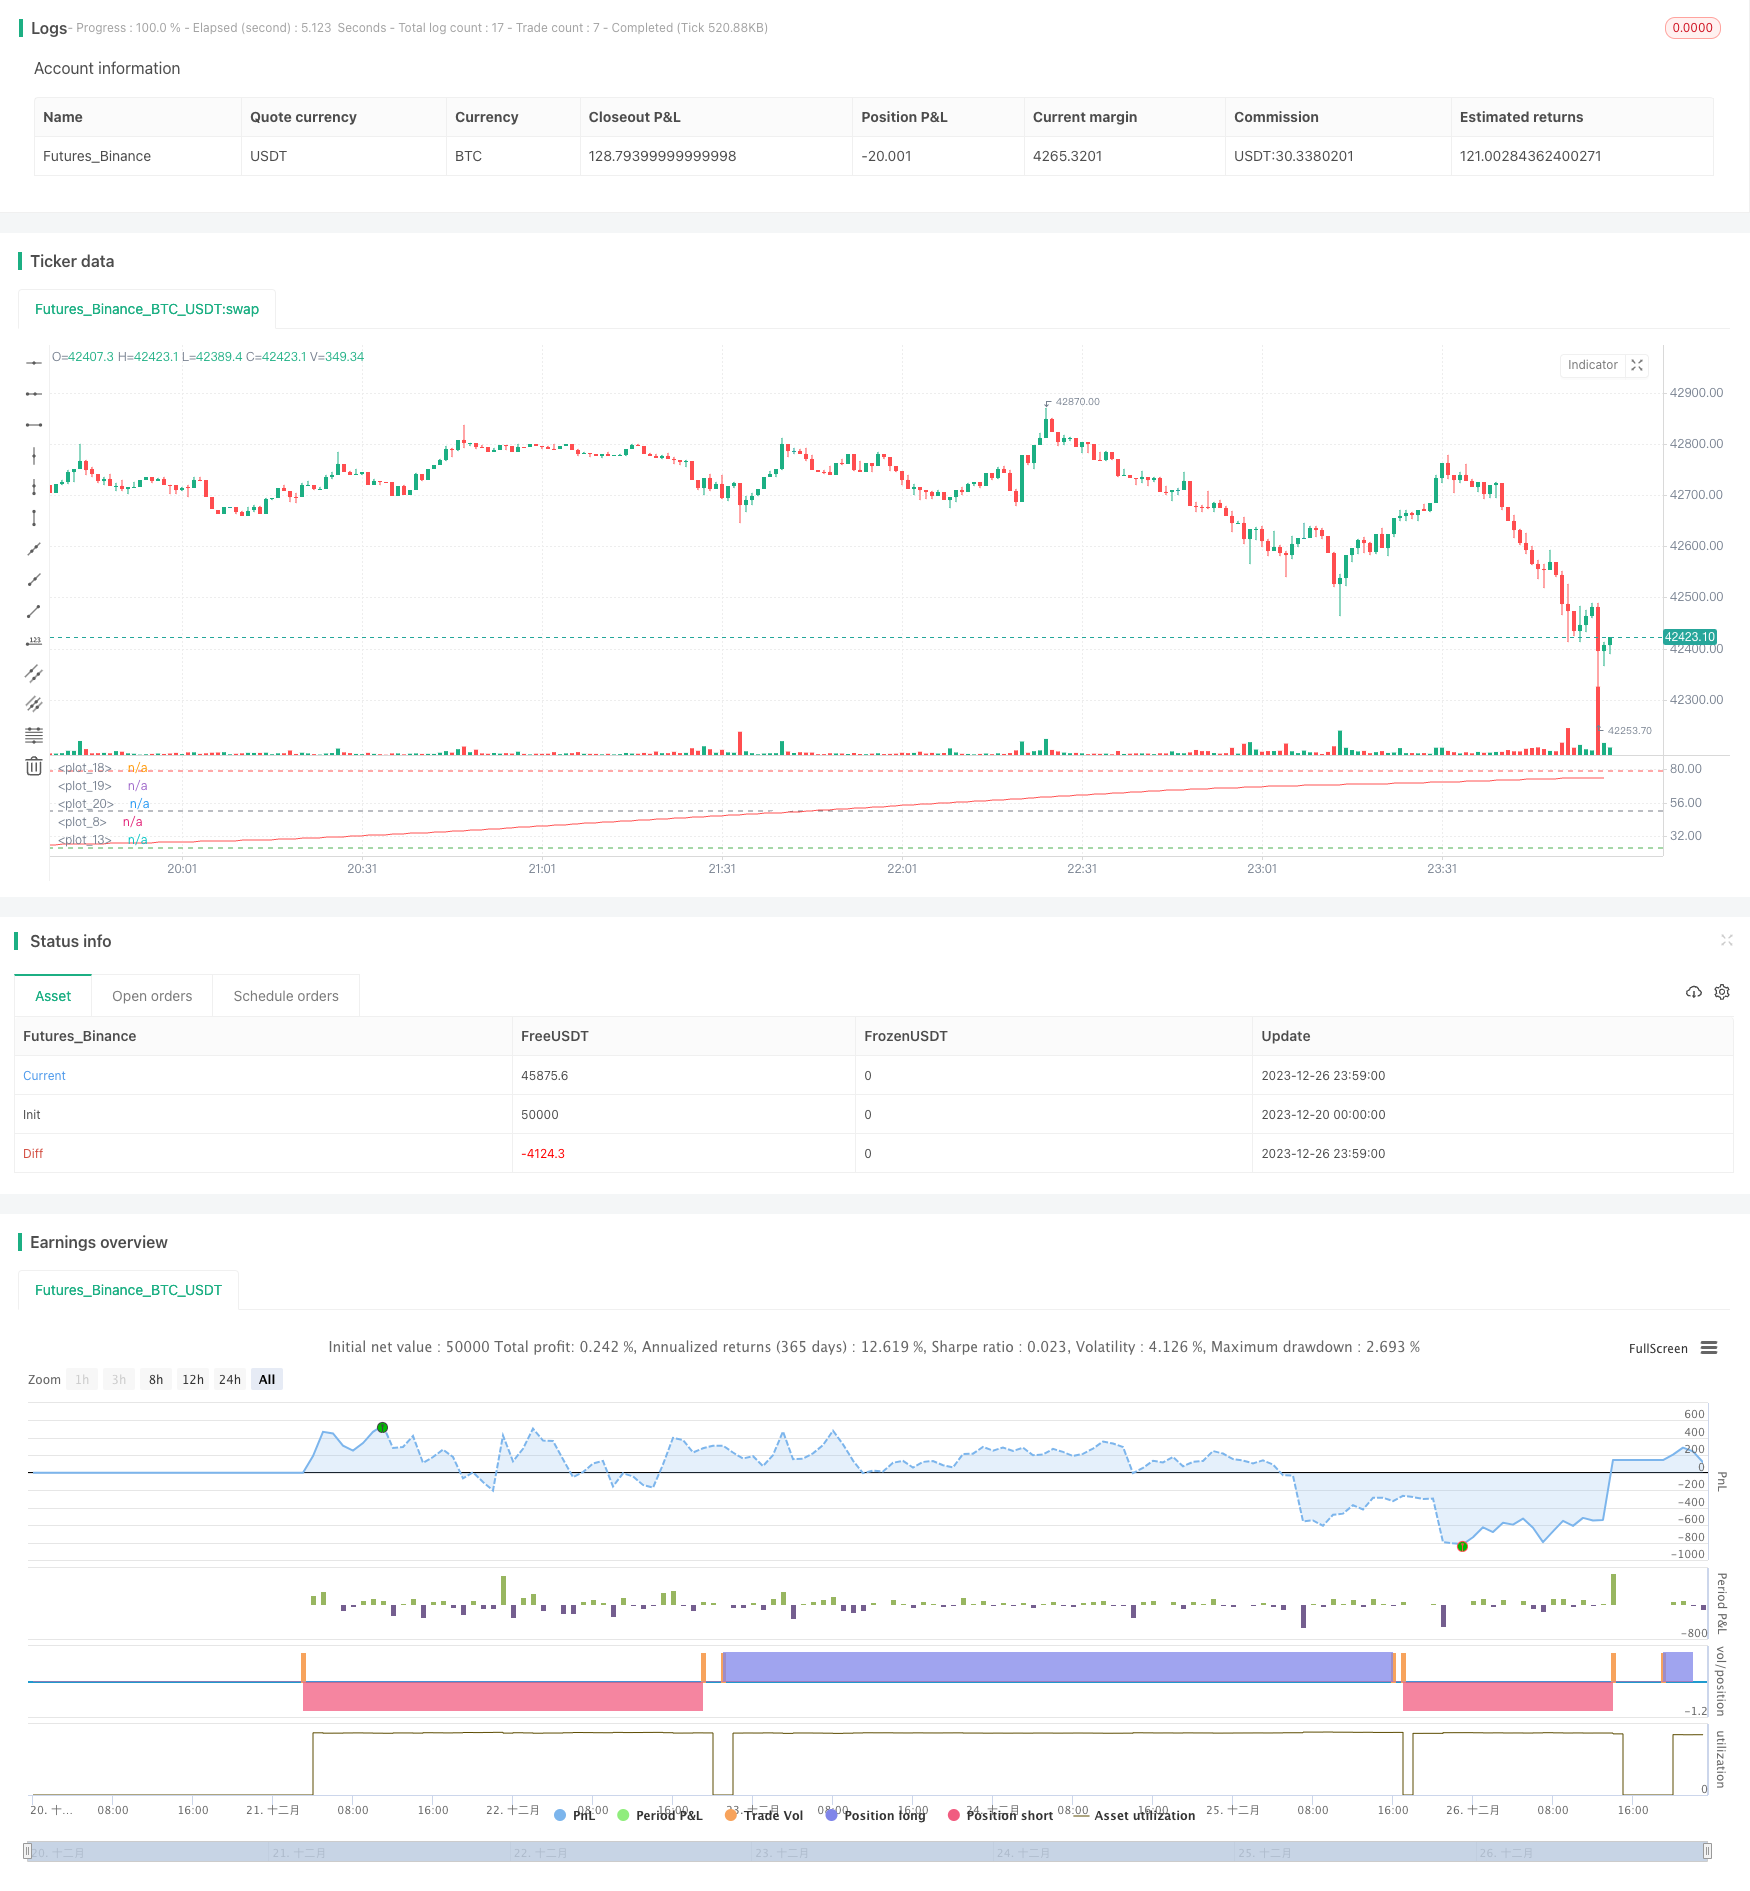
Overview
This is a trend following strategy based on slow stochastic indicator. It uses a long period K line moving average to smooth the slow stochastic and filters out market noise to lock in major trends. The strategy determines entry and exit points based on overbought and oversold levels of the smoothed slow stochastic.
Strategy Logic
The strategy first calculates a 400-period K value SMA smoothing line, and then calculates another 275-period SMA line to further smooth the K line. This makes the final K line very smooth, basically only reflecting the major trend direction of the market. The strategy uses this ultra-smoothed slow stochastic K value as trading signal.
When the K line crosses above the 23 oversold level from below, it goes long. When the K line crosses below the 78.5 overbought level from above, it goes short. Exit signals happen when the K line crosses back above/below the overbought/oversold levels. Thus the strategy achieves trend following effect.
Advantage Analysis
The biggest advantage of this strategy is using the ultra-smoothed slow stochastic to lock in major market trends, avoiding noise interference. The ultra-smoothing makes it only sensitive to major trend changes, filtering out high frequency reversals and oscillations.
Also, compared to common moving average strategies, this strategy can capture trend turning points faster, with larger profit windows.
Risk Analysis
The main risk of this strategy is that the market may oscillate within the overbought/oversold zones for extended periods, causing multiple false signals and losses. In this case parameters need to be adjusted to make the K line smoother, or widen the overbought/oversold zones.
Also, if trend changes abruptly with huge moves, the ultra-smoothed K line may delay signal recognition, causing some potential profit loss. Here the K line MA parameters should be shortened to make it more sensitive.
Optimization Directions
The strategy can be optimized in the following aspects:
- Adjust smoothing periods of K & D values to find optimal combo;
- Test different price inputs like close, typical price etc;
- Add trading volume or position sizing control like ATR stop loss, capital utilization rate control etc;
- Add auxiliary indicators like MACD to avoid false signals;
- Use machine learning to optimize parameters.
Conclusion
The slow stochastic trend following strategy achieves capturing major market trends and avoids high frequency noise interference through ultra-smoothing processing. There are also risks of delayed signal recognition. We can optimize the strategy by adjusting parameters or adding auxiliary conditions to improve stability and profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 400 | smoothK |
| v_input_2_ohlc4 | 0 | price: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
| v_input_3 | 275 | SMAsmoothK |
| v_input_4 | 10 | smoothD |
| v_input_5 | 78.5 | OB |
| v_input_6 | 23 | OS |
Source Pine Script
/*backtest
start: 2023-12-20 00:00:00
end: 2023-12-27 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="Slow Stochastic OB/OS Strategy", overlay=false )

smoothK = input(400, step=5)
price = input(ohlc4)
SMAsmoothK = input(275, step=5)
k = sma(stoch(price, high, low, smoothK), SMAsmoothK)
plot(k, color=white)


smoothD = input(10, step=2)
d = sma(k, smoothD)
plot(d, color=red)


OB = input(78.5, step=0.5)
OS = input(23, step=0.5)
hline(OB, linewidth=1, color=red)
hline(OS,linewidth=1, color=green)
hline(50,linewidth=1, color=gray)


long = crossover(d, OS)
short = crossunder(d, OB)

strategy.entry("Long", strategy.long, when=long) //_signal or long) //or closeshort_signal)
strategy.entry("Short", strategy.short, when=short) //_signal or short) // or closelong_signal)

//If you want to try to play with exits you can activate these!

closelong = crossover(d, OB)
closeshort = crossunder(d, OS)

strategy.close("Long", when=closelong)
strategy.close("Short", when=closeshort)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Slow-Stochastic-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Moving Average Crossover Strategy with Stop Loss and Take ProfitPine Script · Trend following · 4h
- Multi Dimensional Short Term Trend Predictor Technical Analysis and Volatility Adaptive Trading StrategyPine Script · Trend following · 1h
- Mini Pullback Supertrend StrategyPine Script · Trend following · 1h
- Three Exponential Moving Averages and Stochastic Relative Strength Index Trading StrategyPine Script · Trend following · 1h
- Enhanced Moving Average Crossover Sakkoulas Trading StrategyPine Script · Trend following · 1h
- Multi Technical Indicator Gold Real Time Movement Detection and Risk Management StrategyPine Script · Trend following · 1d