SMA Based Intelligent Trailing Stop Strategy with Intraday Pattern Recognition
This is a strategy based on the 18-day Simple Moving Average (SMA18), combining intraday pattern recognition and intelligent trailing stop mechanisms. The strategy primarily observes the price relationship with…
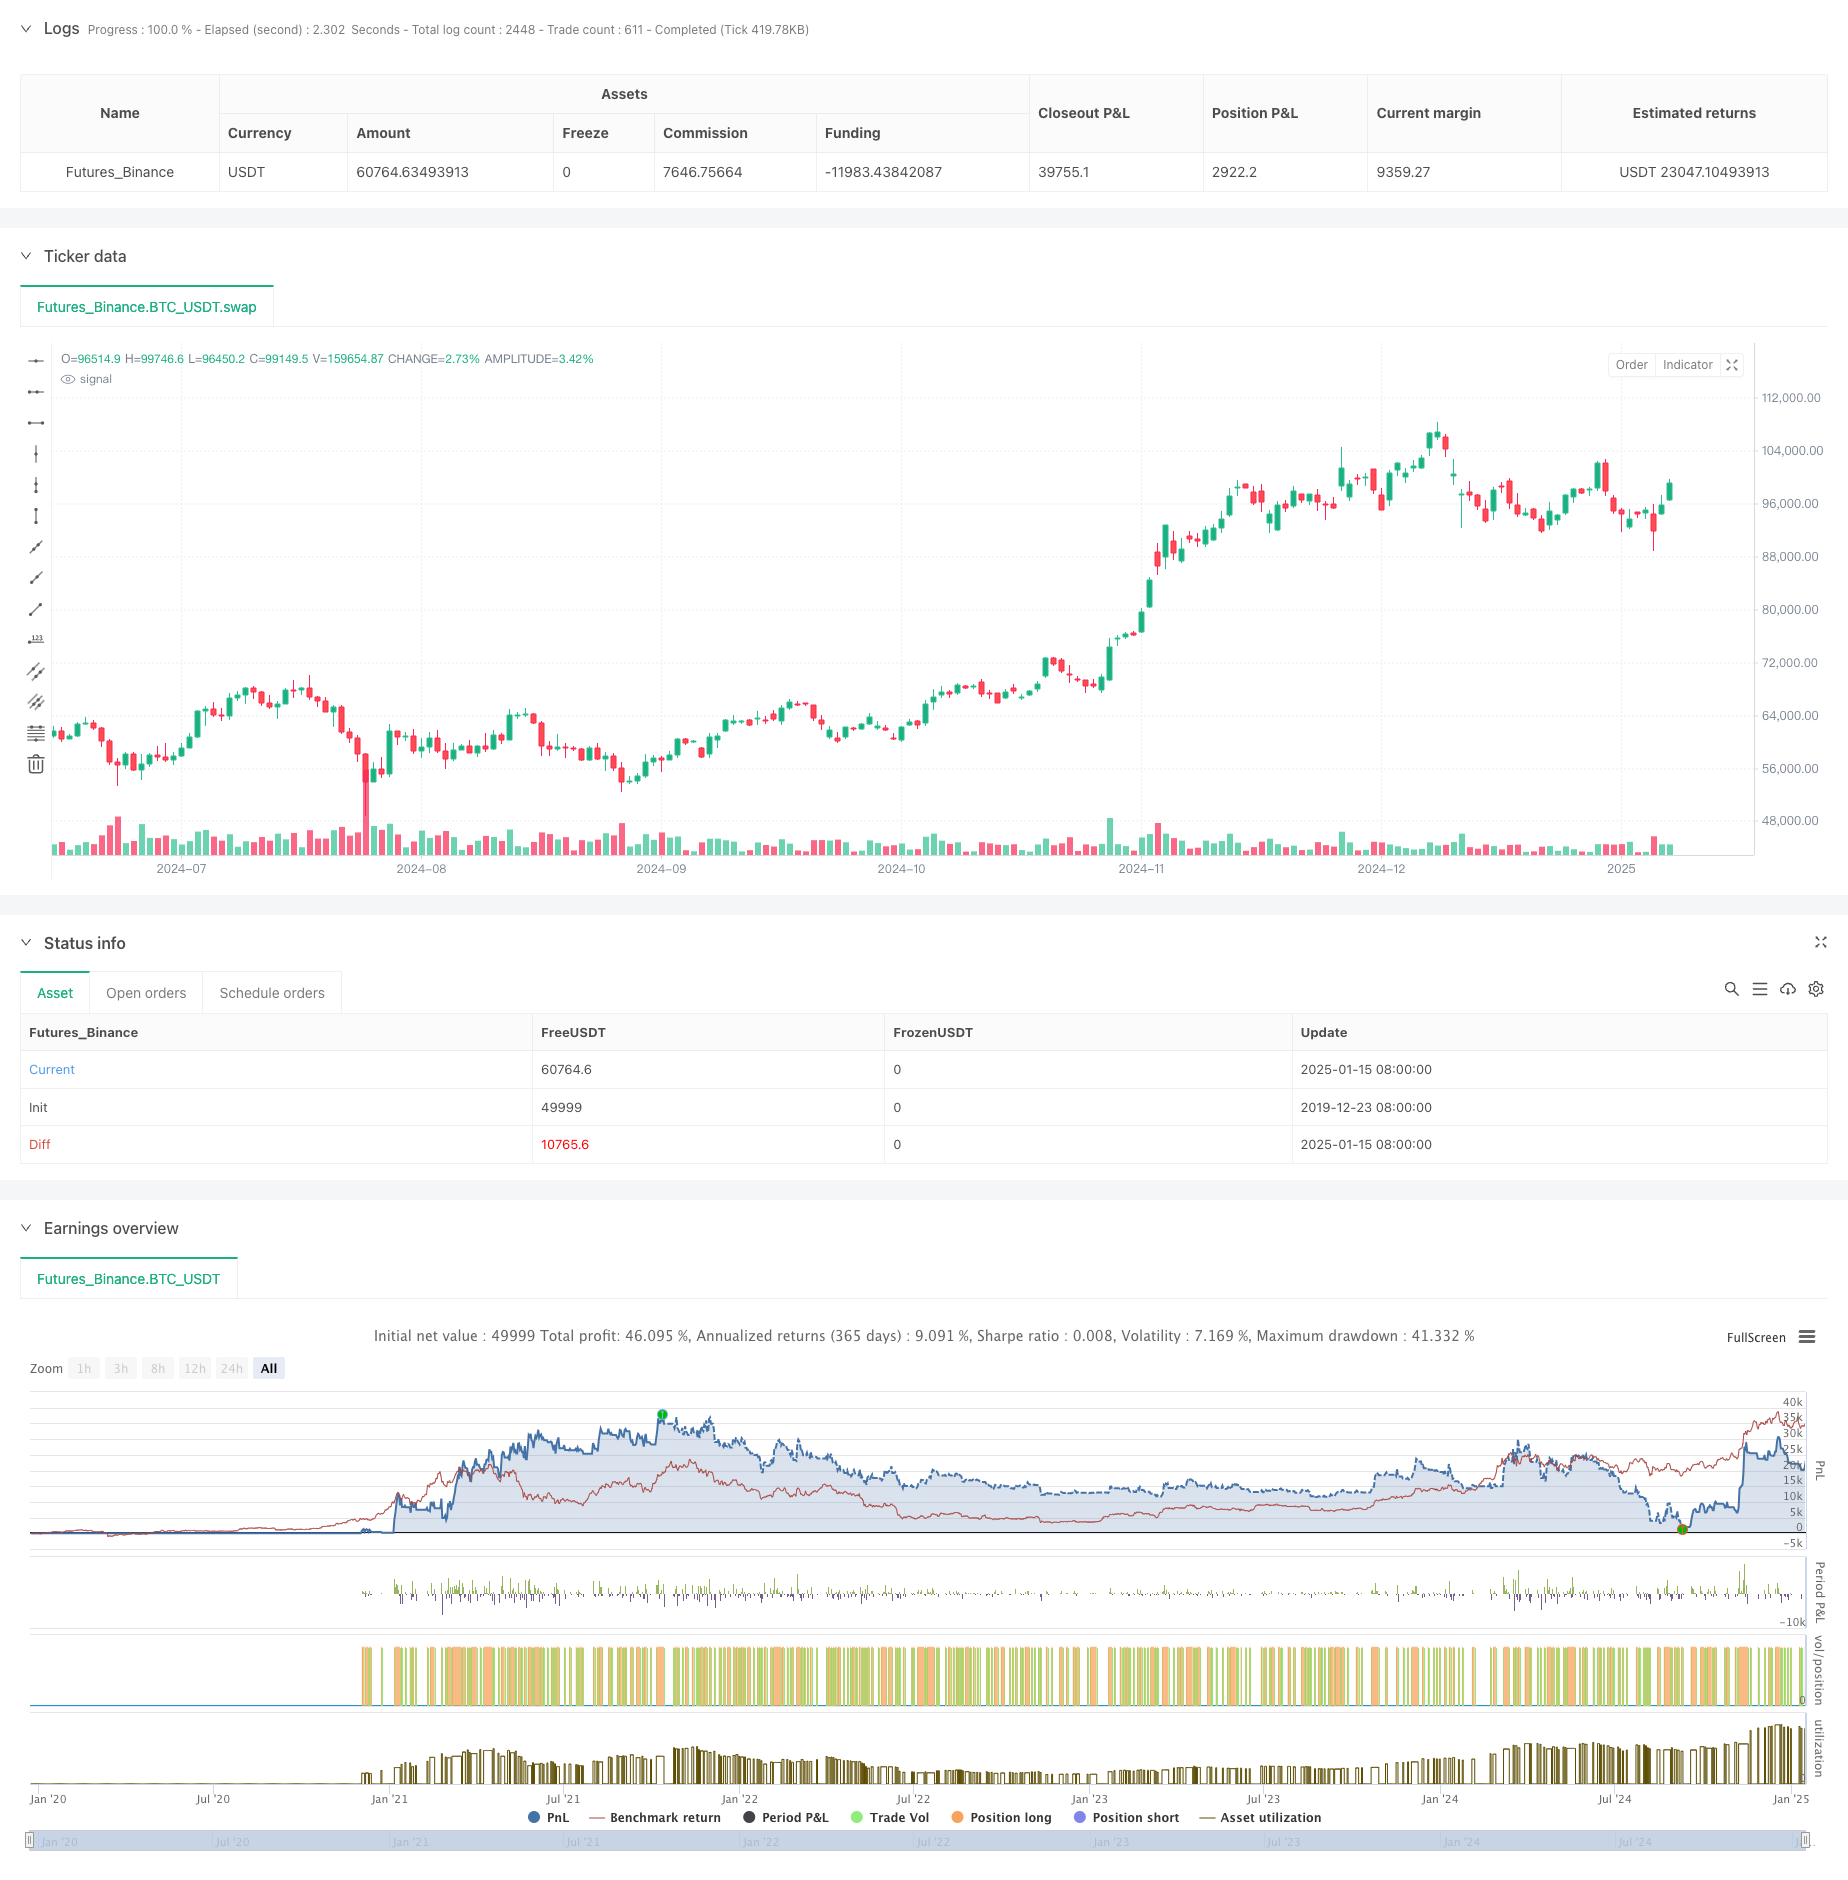
Overview
This is a strategy based on the 18-day Simple Moving Average (SMA18), combining intraday pattern recognition and intelligent trailing stop mechanisms. The strategy primarily observes the price relationship with SMA18, along with intraday high and low positions, to execute long entries at optimal times. It employs a flexible stop-loss approach, offering both fixed stop-loss points and a two-day low trailing stop option.
Strategy Principles
The core logic includes several key elements:
- Entry conditions based on price position relative to the 18-day moving average, with options for breakout or above-line entries
- Analysis of intraday candlestick patterns, particularly focusing on Inside Bar patterns, to improve entry accuracy
- Selective trading based on day-of-week characteristics
- Entry price setting using limit orders with small upward offset from lows to improve fill probability
- Dual stop-loss mechanisms: fixed stops based on entry price or trailing stops based on two-day lows
Strategy Advantages
- Combines technical indicators and price patterns for more reliable entry signals
- Flexible trading time selection mechanism for market-specific optimization
- Intelligent stop-loss system that both protects profits and allows adequate price movement
- Highly adjustable parameters for different market environments
- Effective false signal reduction through Inside Bar pattern filtering
Strategy Risks
- Fixed stops may trigger early exits in volatile markets
- Trailing stops might lock in minimal profits during quick reversals
- Frequent Inside Bars during consolidation may lead to overtrading Mitigation measures:
- Dynamic stop-loss adjustment based on market volatility
- Addition of trend confirmation indicators
- Implementation of minimum profit targets to filter low-quality trades
Optimization Directions
- Incorporate volatility indicators (like ATR) for dynamic stop-loss adjustment
- Add volume analysis dimension to improve signal reliability
- Develop smarter date selection algorithms based on historical performance
- Implement trend strength filters to avoid trading in weak trends
- Enhance Inside Bar recognition algorithms for improved pattern identification
Summary
This strategy constructs a comprehensive trading system by combining multiple analytical dimensions. Its core strengths lie in flexible parameter settings and intelligent stop-loss mechanisms, enabling adaptation to various market environments. Through continuous optimization and improvement, the strategy shows promise for maintaining stable performance across different market conditions.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-16 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
*/

//@version=5
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © zweiprozent

strategy('Buy Low over 18 SMA Strategy', overlay=true, default_qty_value=1)
xing = input(false, title='crossing 18 sma?')
sib = input(false, title='trade inside Bars?')
shortinside = input(false, title='trade inside range bars?')
offset = input(title='offset', defval=0.001)
belowlow = input(title='stop below low minus', defval=0.001)
alsobelow = input(false, title='Trade only above 18 sma?')
tradeabove = input(false, title='Trade with stop above order?')
trailingtwo = input(false, title='exit with two days low trailing?')


insideBar() =>  //and high <= high[1] and low >= low[1] ? 1 : 0
    open <= close[1] and close >= open[1] and close <= close[1] or open >= close[1] and open <= open[1] and close <= open[1] and close >= close[1] ? 1 : 0

inside() =>
    high <= high[1] and low >= low[1] ? 1 : 0
enterIndex = 0.0
enterIndex := enterIndex[1]

inPosition = not na(strategy.position_size) and strategy.position_size > 0
if inPosition and na(enterIndex)
    enterIndex := bar_index
    enterIndex


//if strategy.position_size <= 0

//    strategy.exit("Long", stop=low[0]-stop_loss,comment="stop loss")


//if not na(enterIndex) and bar_index - enterIndex + 0 >= 0

//    strategy.exit("Long", stop=low[0]-belowlow,comment="exit")

//    enterIndex := na

T_Low = request.security(syminfo.tickerid, 'D', low[0])
D_High = request.security(syminfo.tickerid, 'D', high[1])
D_Low = request.security(syminfo.tickerid, 'D', low[1])
D_Close = request.security(syminfo.tickerid, 'D', close[1])
D_Open = request.security(syminfo.tickerid, 'D', open[1])

W_High2 = request.security(syminfo.tickerid, 'W', high[1])
W_High = request.security(syminfo.tickerid, 'W', high[0])
W_Low = request.security(syminfo.tickerid, 'W', low[0])
W_Low2 = request.security(syminfo.tickerid, 'W', low[1])
W_Close = request.security(syminfo.tickerid, 'W', close[1])
W_Open = request.security(syminfo.tickerid, 'W', open[1])

//longStopPrice  = strategy.position_avg_price * (1 - stopl)
// Go Long - if prev day low is broken and stop loss prev day low
entryprice = ta.sma(close, 18)

//(high[0]<=high[1]or close[0]<open[0]) and low[0]>vwma(close,30) and time>timestamp(2020,12,0,0,0)

showMon = input(true, title='trade tuesdays?')
showTue = input(true, title='trade wednesdayy?')
showWed = input(true, title='trade thursday?')
showThu = input(true, title='trade friday?')
showFri = input(true, title='trade saturday?')
showSat = input(true, title='trade sunday?')
showSun = input(true, title='trade monday?')

isMon() =>
    dayofweek(time('D')) == dayofweek.monday and showMon
isTue() =>
    dayofweek(time('D')) == dayofweek.tuesday and showTue
isWed() =>
    dayofweek(time('D')) == dayofweek.wednesday and showWed
isThu() =>
    dayofweek(time('D')) == dayofweek.thursday and showThu
isFri() =>
    dayofweek(time('D')) == dayofweek.friday and showFri
isSat() =>
    dayofweek(time('D')) == dayofweek.saturday and showSat
isSun() =>
    dayofweek(time('D')) == dayofweek.sunday and showSun


clprior = close[0]
entryline = ta.sma(close, 18)[1]
//(isMon() or isTue()or isTue()or  isWed()
noathigh = high < high[1] or high[2] < high[3] or high[1] < high[2] or low[1] < ta.sma(close, 18)[0] and close > ta.sma(close, 18)[0]

if noathigh and time > timestamp(2020, 12, 0, 0, 0) and (alsobelow == false or high >= ta.sma(close, 18)[0]) and (isMon() or isTue() or isWed() or isThu() or isFri() or isSat() or isSun()) and (high >= high[1] or sib or low <= low[1])  //((sib == false and inside()==true) or inside()==false) and (insideBar()==true or shortinside==false)
    if tradeabove == false
        strategy.entry('Long', strategy.long, limit=low + offset * syminfo.mintick, comment='long')
    if tradeabove == true and (xing == false or clprior < entryline)  // and high<high[1]
        strategy.entry('Long', strategy.long, stop=high + offset * syminfo.mintick, comment='long')


//if time>timestamp(2020,12,0,0,0) and isSat()
//    strategy.entry("Long", strategy.long, limit=0, comment="long")


//strategy.exit("Long", stop=low-400*syminfo.mintick)

//strategy.exit("Long", stop=strategy.position_avg_price-10*syminfo.mintick,comment="exit")
//strategy.exit("Long", stop=low[1]-belowlow*syminfo.mintick, comment="stop")

if strategy.position_avg_price > 0 and trailingtwo == false and close > strategy.position_avg_price
    strategy.exit('Long', stop=strategy.position_avg_price, comment='stop')

if strategy.position_avg_price > 0 and trailingtwo == false and (low > strategy.position_avg_price or close < strategy.position_avg_price)
    strategy.exit('Long', stop=low[0] - belowlow * syminfo.mintick, comment='stop')

if strategy.position_avg_price > 0 and trailingtwo
    strategy.exit('Long', stop=ta.lowest(low, 2)[0] - belowlow * syminfo.mintick, comment='stop')
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/SMA-Based-Intelligent-Trailing-Stop-Strategy-with-Intraday-Pattern-Recognition.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Bull Flag Breakout StrategyPine Script · Breakout · 1h
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h