Strategy vault / Trend following
Sma BTC killer
Hello !! I made nice strategy with insane profit with only LONG and SHORT orders well, this straegy is for ------- BINANCE:BTCUSDT The strategy logic is quite simple Strategy using 3 diffrent sma (7,21,55) to find a…
Hello !!
I made nice strategy with insane profit with only LONG and SHORT orders well, this straegy is for ------->>> BINANCE:BTCUSDT
The strategy logic is quite simple
Strategy using 3 diffrent sma (7,21,55) to find a correct trend To avoid a lot of wrong signals I added two indicators like:
ADX - Is one of the most powerful and accurate trend indicators. ADX measures how strong a trend is, and can give valuable information on whether there is a potential trading opportunity. CLOUD - This is one of the newset indicators I'm using. This indicator helps strategy , this indicator is designed to indicate the correct market trend. By applying the great length of this indicator, I am able to notice a change in the trend a little later, but more accurately.
additionally I added trailing stop-loss to max security
To be honest this strategy looks really good, a lot of trades, high profit and a small amount of indicators, the future profits could be similar
Using this combinations of SMA gives me amazing quick changes while trend is also changin fast like here:
snapshot
unfortunetlly I was not able to 100% eleiminate wrong signals on the flat chart like here:
snapshot
I hope this strategy will be usefull for anyone ;)
Ass always
ENJOY !!
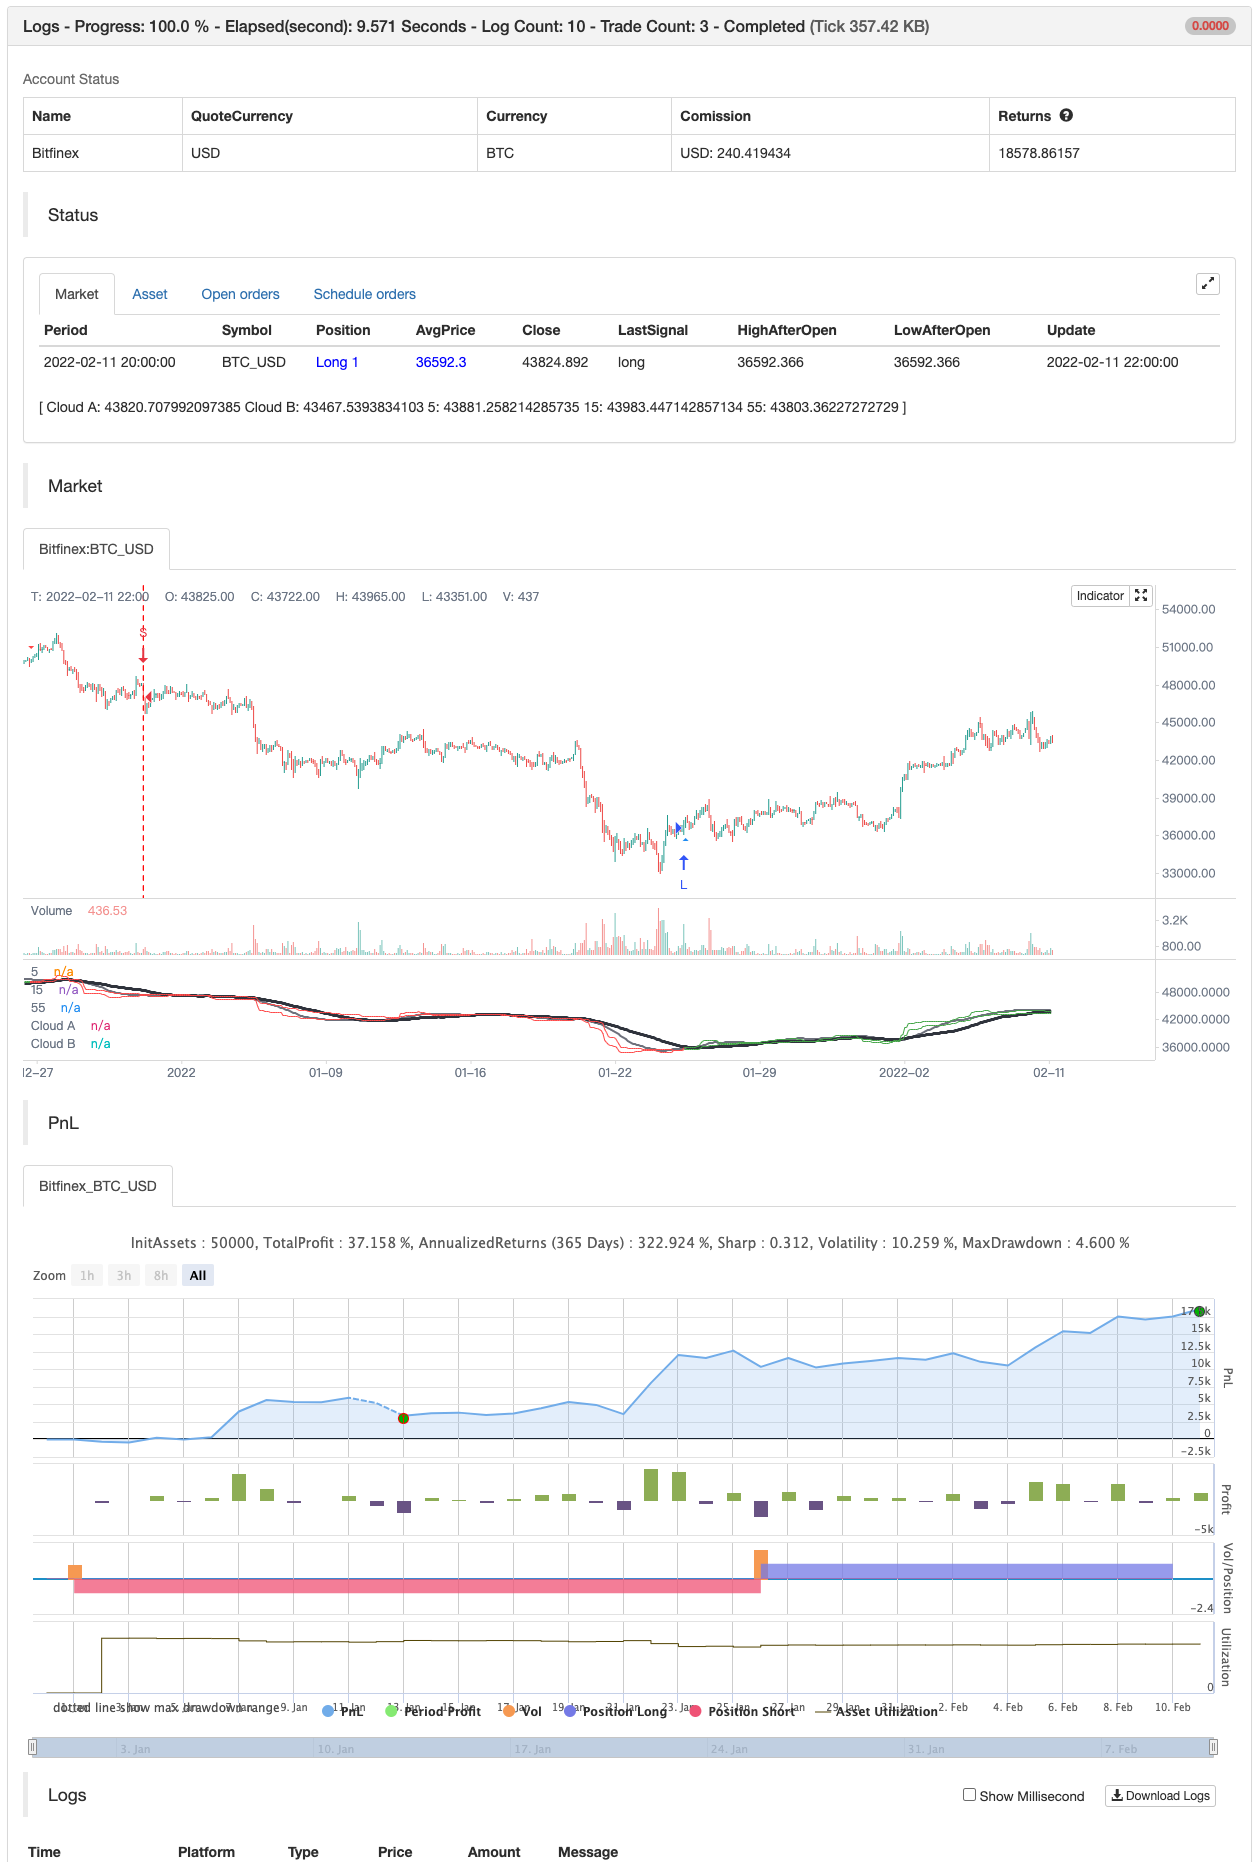
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | 1-SMA Lenght |
| v_input_2 | 28 | 2-SMA Lenght |
| v_input_3 | 55 | 3-SMA Lenght |
| v_input_4 | 0 | (?Average Directional Index) Adx Type: MASANAKAMURA | CLASSIC |
| v_input_5 | 29 | Adx Lenght |
| v_input_6 | 21 | Adx Treshold |
| v_input_7 | 11 | (?Cloud)Cloud Length |
| v_input_8 | 18 | (?Average True Range) PP period |
| v_input_9 | 5 | ATR Factor |
| v_input_10 | 6 | ATR Period |
Source Pine Script
/*backtest
start: 2022-01-01 00:00:00
end: 2022-02-11 23:59:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Bitfinex","currency":"BTC_USD"}]
*/
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © wielkieef
//@version=4
src = close
//strategy("Sma BTC killer [60MIN]", overlay = true, pyramiding=1,initial_capital = 10000, default_qty_type= strategy.percent_of_equity, default_qty_value = 100, calc_on_order_fills=false, slippage=0,commission_type=strategy.commission.percent,commission_value=0.04)
//SMAs -----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
Length1 = input(14, title=" 1-SMA Lenght", minval=1)
Length2 = input(28, title=" 2-SMA Lenght", minval=1)
Length3 = input(55, title=" 3-SMA Lenght", minval=1)
xPrice = close
SMA1 = sma(xPrice, Length1)
SMA2 = sma(xPrice, Length2)
SMA3 = sma(xPrice, Length3)
//Indicators Inputs -------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
ADX_options = input("MASANAKAMURA", title=" Adx Type", options = ["CLASSIC", "MASANAKAMURA"], group="Average Directional Index")
ADX_len = input(29, title=" Adx Lenght", type=input.integer, minval = 1, group="Average Directional Index")
th = input(21, title=" Adx Treshold", type=input.integer, minval = 0, group="Average Directional Index")
len = input(11, title="Cloud Length", group="Cloud")
// ATR Inputs -------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
prd = input(18, title=" PP period", group="Average True Range")
Factor = input(5, title=" ATR Factor", group="Average True Range")
Pd = input(6, title=" ATR Period", group="Average True Range")
//Indicators -------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
calcADX(_len) =>
up = change(high)
down = -change(low)
plusDM = na(up) ? na : (up > down and up > 0 ? up : 0)
minusDM = na(down) ? na : (down > up and down > 0 ? down : 0)
truerange = rma(tr, _len)
_plus = fixnan(100 * rma(plusDM, _len) / truerange)
_minus = fixnan(100 * rma(minusDM, _len) / truerange)
sum = _plus + _minus
_adx = 100 * rma(abs(_plus - _minus) / (sum == 0 ? 1 : sum), _len)
[_plus,_minus,_adx]
calcADX_Masanakamura(_len) =>
SmoothedTrueRange = 0.0
SmoothedDirectionalMovementPlus = 0.0
SmoothedDirectionalMovementMinus = 0.0
TrueRange = max(max(high - low, abs(high - nz(close[1]))), abs(low - nz(close[1])))
DirectionalMovementPlus = high - nz(high[1]) > nz(low[1]) - low ? max(high - nz(high[1]), 0) : 0
DirectionalMovementMinus = nz(low[1]) - low > high - nz(high[1]) ? max(nz(low[1]) - low, 0) : 0
SmoothedTrueRange := nz(SmoothedTrueRange[1]) - (nz(SmoothedTrueRange[1]) /_len) + TrueRange
SmoothedDirectionalMovementPlus := nz(SmoothedDirectionalMovementPlus[1]) - (nz(SmoothedDirectionalMovementPlus[1]) / _len) + DirectionalMovementPlus
SmoothedDirectionalMovementMinus := nz(SmoothedDirectionalMovementMinus[1]) - (nz(SmoothedDirectionalMovementMinus[1]) / _len) + DirectionalMovementMinus
DIP = SmoothedDirectionalMovementPlus / SmoothedTrueRange * 100
DIM = SmoothedDirectionalMovementMinus / SmoothedTrueRange * 100
DX = abs(DIP-DIM) / (DIP+DIM)*100
adx = sma(DX, _len)
[DIP,DIM,adx]
[DIPlusC,DIMinusC,ADXC] = calcADX(ADX_len)
[DIPlusM,DIMinusM,ADXM] = calcADX_Masanakamura(ADX_len)
DIPlus = ADX_options == "CLASSIC" ? DIPlusC : DIPlusM
DIMinus = ADX_options == "CLASSIC" ? DIMinusC : DIMinusM
ADX = ADX_options == "CLASSIC" ? ADXC : ADXM
L_adx = DIPlus > DIMinus and ADX > th
S_adx = DIPlus < DIMinus and ADX > th
ADX_COLOR = L_adx ? color.lime : S_adx ? color.red : color.orange
PI = 2 * asin(1)
hilbertTransform(src) =>
0.0962 * src + 0.5769 * nz(src[2]) - 0.5769 * nz(src[4]) - 0.0962 * nz(src[6])
computeComponent(src, mesaPeriodMult) =>
hilbertTransform(src) * mesaPeriodMult
computeAlpha(src, fastLimit, slowLimit) =>
mesaPeriod = 0.0
mesaPeriodMult = 0.075 * nz(mesaPeriod[1]) + 0.54
smooth = 0.0
smooth := (4 * src + 3 * nz(src[1]) + 2 * nz(src[2]) + nz(src[3])) / 10
detrender = 0.0
detrender := computeComponent(smooth, mesaPeriodMult)
I1 = nz(detrender[3])
Q1 = computeComponent(detrender, mesaPeriodMult)
jI = computeComponent(I1, mesaPeriodMult)
jQ = computeComponent(Q1, mesaPeriodMult)
I2 = 0.0
Q2 = 0.0
I2 := I1 - jQ
Q2 := Q1 + jI
I2 := 0.2 * I2 + 0.8 * nz(I2[1])
Q2 := 0.2 * Q2 + 0.8 * nz(Q2[1])
Re = I2 * nz(I2[1]) + Q2 * nz(Q2[1])
Im = I2 * nz(Q2[1]) - Q2 * nz(I2[1])
Re := 0.2 * Re + 0.8 * nz(Re[1])
Im := 0.2 * Im + 0.8 * nz(Im[1])
if Re != 0 and Im != 0
mesaPeriod := 2 * PI / atan(Im / Re)
if mesaPeriod > 1.5 * nz(mesaPeriod[1])
mesaPeriod := 1.5 * nz(mesaPeriod[1])
if mesaPeriod < 0.67 * nz(mesaPeriod[1])
mesaPeriod := 0.67 * nz(mesaPeriod[1])
if mesaPeriod < 6
mesaPeriod := 6
if mesaPeriod > 50
mesaPeriod := 50
mesaPeriod := 0.2 * mesaPeriod + 0.8 * nz(mesaPeriod[1])
phase = 0.0
if I1 != 0
phase := (180 / PI) * atan(Q1 / I1)
deltaPhase = nz(phase[1]) - phase
if deltaPhase < 1
deltaPhase := 1
alpha = fastLimit / deltaPhase
if alpha < slowLimit
alpha := slowLimit
[alpha,alpha/2.0]
er = abs(change(src,len)) / sum(abs(change(src)),len)
[a,b] = computeAlpha(src, er, er*0.1)
mama = 0.0
mama := a * src + (1 - a) * nz(mama[1])
fama = 0.0
fama := b * mama + (1 - b) * nz(fama[1])
alpha = pow((er * (b - a)) + a, 2)
kama = 0.0
kama := alpha * src + (1 - alpha) * nz(kama[1])
L_cloud = kama > kama[1]
S_cloud = kama < kama[1]
float ph = pivothigh(prd, prd)
float pl = pivotlow(prd, prd)
var float center = na
float lastpp = ph ? ph : pl ? pl : na
if lastpp
if na(center)
center := lastpp
else
center := (center * 2 + lastpp) / 3
Up = center - (Factor * atr(Pd))
Dn = center + (Factor * atr(Pd))
float TUp = na
float TDown = na
Trend = 0
TUp := close[1] > TUp[1] ? max(Up, TUp[1]) : Up
TDown := close[1] < TDown[1] ? min(Dn, TDown[1]) : Dn
Trend := close > TDown[1] ? 1: close < TUp[1]? -1: nz(Trend[1], 1)
Trailingsl = Trend == 1 ? TUp : TDown
bsignal = Trend == 1 and Trend[1] == -1
ssignal = Trend == -1 and Trend[1] == 1
L_ATR = Trend == 1
S_ATR = Trend == -1
// Strategy logic ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
var bool longCond = na, var bool shortCond = na
var int CondIni_long = 0, var int CondIni_short = 0
var bool _Final_longCondition = na, var bool _Final_shortCondition = na
var float last_open_longCondition = na, var float last_open_shortCondition = na
var int last_longCondition = na, var int last_shortCondition = na
var int last_Final_longCondition = na, var int last_Final_shortCondition = na
var int nLongs = na, var int nShorts = na
Long_MA =L_adx and L_cloud and (SMA1 < close and SMA2 < close and SMA3 < close )
Short_MA =S_adx and S_cloud and (SMA1 > close and SMA2 > close and SMA3 > close )
longCond := Long_MA
shortCond := Short_MA
CondIni_long := longCond[1] ? 1 : shortCond[1] ? -1 : nz(CondIni_long[1] )
CondIni_short := longCond[1] ? 1 : shortCond[1] ? -1 : nz(CondIni_short[1] )
longCondition = (longCond[1] and nz(CondIni_long[1]) == -1 )
shortCondition = (shortCond[1] and nz(CondIni_short[1]) == 1 )
var float sum_long = 0.0, var float sum_short = 0.0
var float Position_Price = 0.0
var bool Final_long_BB = na, var bool Final_short_BB = na
var int last_long_BB = na, var int last_short_BB = na
last_open_longCondition := longCondition or Final_long_BB[1] ? close[1] : nz(last_open_longCondition[1] )
last_open_shortCondition := shortCondition or Final_short_BB[1] ? close[1] : nz(last_open_shortCondition[1] )
last_longCondition := longCondition or Final_long_BB[1] ? time : nz(last_longCondition[1] )
last_shortCondition := shortCondition or Final_short_BB[1] ? time : nz(last_shortCondition[1] )
in_longCondition = last_longCondition > last_shortCondition
in_shortCondition = last_shortCondition > last_longCondition
last_Final_longCondition := longCondition ? time : nz(last_Final_longCondition[1] )
last_Final_shortCondition := shortCondition ? time : nz(last_Final_shortCondition[1] )
nLongs := nz(nLongs[1] )
nShorts := nz(nShorts[1] )
if longCondition or Final_long_BB
nLongs := nLongs + 1
nShorts := 0
sum_long := nz(last_open_longCondition) + nz(sum_long[1])
sum_short := 0.0
if shortCondition or Final_short_BB
nLongs := 0
nShorts := nShorts + 1
sum_short := nz(last_open_shortCondition)+ nz(sum_short[1])
sum_long := 0.0
Position_Price := nz(Position_Price[1])
Position_Price := longCondition or Final_long_BB ? sum_long/nLongs : shortCondition or Final_short_BB ? sum_short/nShorts : na
ATR_L_STOP = ssignal and in_longCondition
ATR_S_STOP = bsignal and in_shortCondition
// Plots and colors 010101010101010010101010101010101010101001010101010101001010101001010100101100111100101010010100110110010011100101010101010010101010101001011110011010101010101001010100101100110101010001001010101001010101001110110010101010100101010101010100111110101010101010101010100101010101100
colors = (in_longCondition ? color.green : in_shortCondition ? color.red : color.orange)
bgcolor(color=colors)
//barcolor (color = colors)
plotshape(longCondition, title="Long", style=shape.triangleup, location=location.belowbar, color=color.blue, size=size.small , transp = 0 )
plotshape(shortCondition, title="Short", style=shape.triangledown, location=location.abovebar, color=color.red, size=size.small , transp = 0 )
mama_p = plot(mama, title="Cloud A", style= plot.style_stepline, color=colors )
fama_p = plot(fama, title="Cloud B", style= plot.style_stepline, color=colors )
fill (mama_p,fama_p, color=colors )
plot(SMA1, color=color.white,style= plot.style_stepline, title="5", linewidth=1)
plot(SMA2, color=color.gray,style= plot.style_stepline, title="15", linewidth=2)
plot(SMA3, color=color.black,style= plot.style_stepline, title="55", linewidth=3)
plotshape(ATR_L_STOP, title = "ATR LONG CLOSE", style=shape.arrowdown, location=location.abovebar, color=color.red, size=size.small , text="ATR LONG CLOSE", textcolor=color.red, transp = 0 )
plotshape(ATR_S_STOP, title = "ATR SHORT CLOSE", style=shape.arrowup, location=location.belowbar, color=color.blue, size=size.small, text="ATR SHORT CLOSE", textcolor=color.blue, transp = 0 )
// Strategy -----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
if Long_MA
strategy.entry ("L", strategy.long)
if Short_MA
strategy.entry ("S", strategy.short)
strategy.close_all( when = ATR_L_STOP or ATR_S_STOP)
// By wielkieefPublished by ChaoZhang on the FMZ strategy square · last modified 2022-05-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Sma-BTC-killer.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- ADX Filtered SuperTrend Pivot Trading StrategyPine Script · Trend following · 1d
- Advanced Multi Indicator Trend Confirmation Trading StrategyPine Script · Trend following · 1d