Strategy vault / Trend following
SMA Crossover Trading Strategy 436533
This strategy is designed based on the golden cross and dead cross principles of Simple Moving Average (SMA). The strategy uses two SMAs, namely fast SMA and slow SMA. When the fast SMA crosses above the slow SMA…
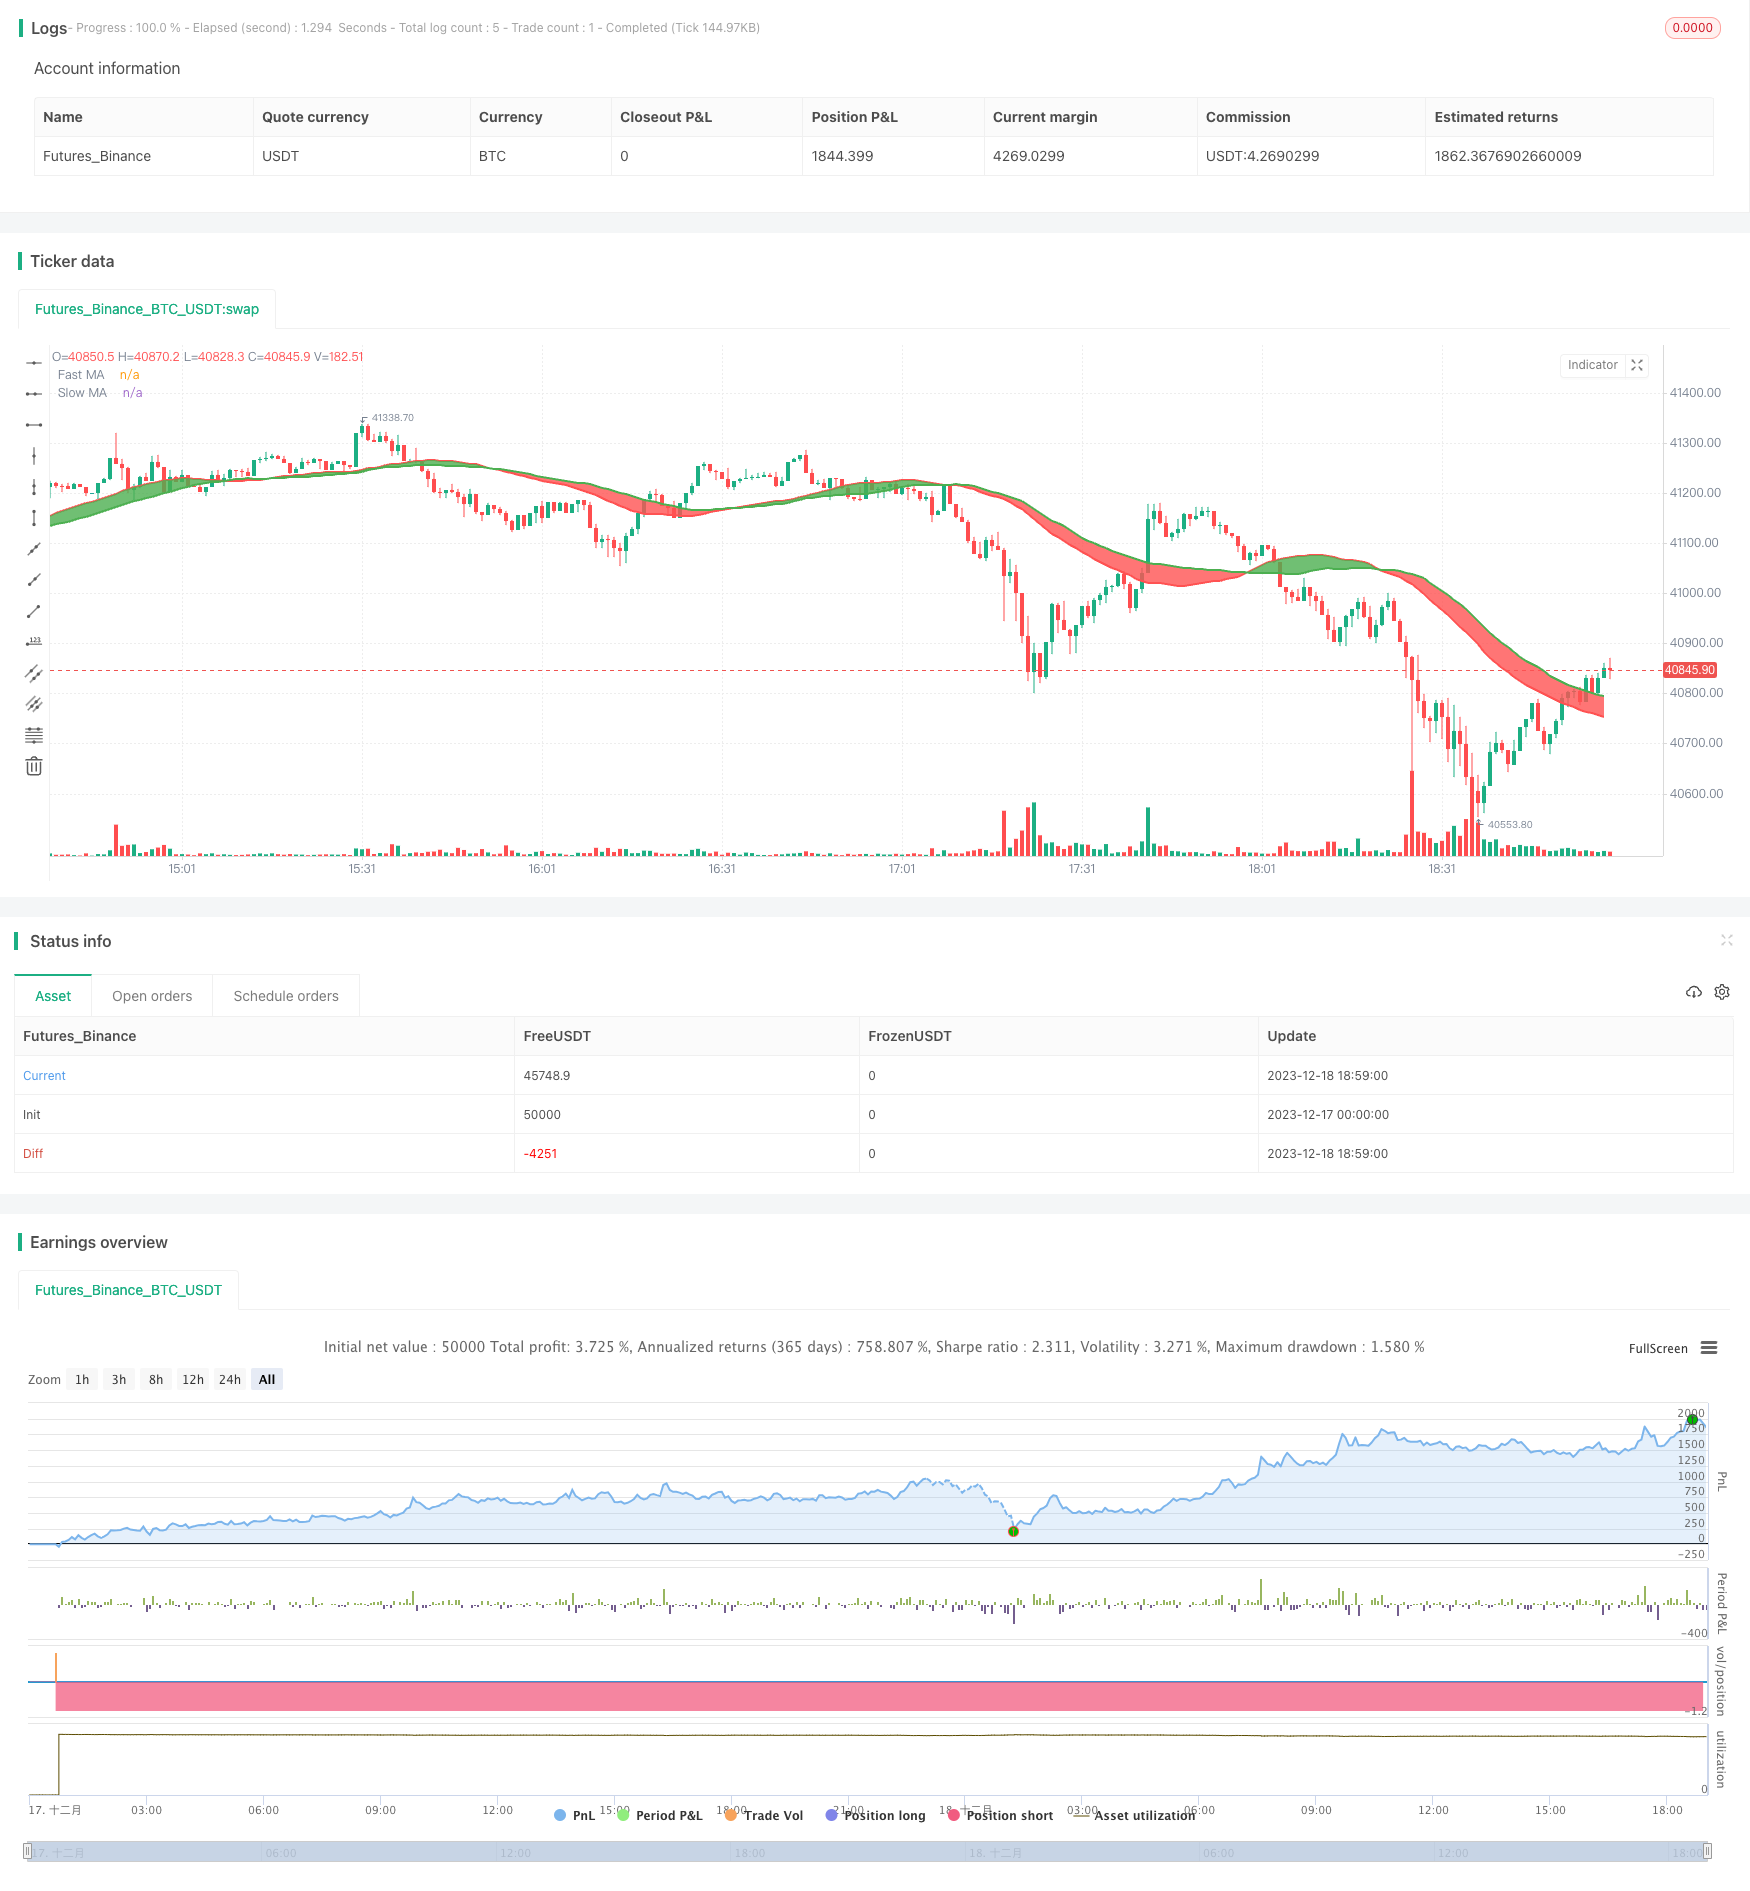
Overview
This strategy is designed based on the golden cross and dead cross principles of Simple Moving Average (SMA). The strategy uses two SMAs, namely fast SMA and slow SMA. When the fast SMA crosses above the slow SMA from below, a buy signal is generated. When the fast SMA crosses below the slow SMA from above, a sell signal is generated.
Strategy Logic
The strategy mainly relies on two SMA indicator lines. The fast SMA has a shorter period and can capture price changes faster. The slow SMA has a longer period and can filter out some noise. When the fast SMA crosses above the slow SMA from below, it indicates that the short-term rising speed is faster and generates a buy signal. When the fast SMA crosses below the slow SMA from above, it indicates that the short-term falling speed is faster and generates a sell signal.
By setting different SMA period parameters, the strategy parameters can be adjusted to some extent to adapt to different market environments. At the same time, the strategy also allows setting the backtesting time range for testing the strategy parameters on historical data.
Advantage Analysis
- Uses the well-known SMA indicator with simple logic
- Customizable SMA period parameters with strong adaptability
- Backtesting time range can be set for parameter optimization
- Using crossover to generate signals has a certain filtering effect and can reduce wrong trades
Risk Analysis
- SMA itself has lagging effect and may miss short-term opportunities
- Unable to determine the momentum of the trend, the effectiveness of signal generation may be unstable
- Improper SMA period parameter settings will increase false signals
To address the above risks, the following measures can be taken:
- Appropriately shorten the SMA cycle to improve sensitivity
- Incorporate other indicators to determine trend momentum
- Find the optimal parameter combination using parameter optimization tools
Optimization Directions
- Add stop loss strategy to control single loss
- Add position management mechanism
- Combine with other technical indicators
- Add machine learning algorithms to achieve dynamic parameter optimization
Summary
This is a typical trend following strategy. By applying the simple principle of double moving average crossover, it can obtain good tracking results when the parameters are set appropriately. However, SMA itself has a certain lagging effect and cannot determine the momentum of the trend. Therefore, in actual application, other auxiliary tools need to be introduced to form an indicator combination, and supplemented with automated parameter optimization and risk control means, in order to make the strategy steadily profitable.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_open | 0 | Fast MA Source: open | high | low | close | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 36 | Fast MA Period |
| v_input_3_open | 0 | Slow MA Source: open | high | low | close | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 46 | Slow MA Period |
| v_input_5 | 9 | From Month |
| v_input_6 | true | From Day |
| v_input_7 | 2018 | From Year |
| v_input_8 | true | To Month |
| v_input_9 | true | To Day |
| v_input_10 | 9999 | To Year |
Source Pine Script
/*backtest
start: 2023-12-17 00:00:00
end: 2023-12-18 19:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//strategy(title="MA Cross Entry & Exit w/Date Range", overlay=true, initial_capital=10000, currency='USD')

strategy(title="SMA Cross Entry & Exit Strategy", overlay=true)

// Credit goes to this developer for the "Date Range Code"
// https://www.tradingview.com/script/62hUcP6O-How-To-Set-Backtest-Date-Range/


// === GENERAL INPUTS ===
// short ma
maFastSource   = input(defval = open, title = "Fast MA Source")
maFastLength   = input(defval = 36, title = "Fast MA Period", minval = 1)
// long ma
maSlowSource   = input(defval = open , title = "Slow MA Source")
maSlowLength   = input(defval = 46, title = "Slow MA Period", minval = 1)

// === SERIES SETUP ===
// a couple of ma's..
maFast = sma(maFastSource, maFastLength)
maSlow = sma(maSlowSource, maSlowLength)


// === PLOTTING ===
fast = plot(maFast, title = "Fast MA", color = red, linewidth = 2, style = line, transp = 30)
slow = plot(maSlow, title = "Slow MA", color = green, linewidth = 2, style = line, transp = 30)

// === INPUT BACKTEST RANGE ===
FromMonth = input(defval = 9, title = "From Month", minval = 1, maxval = 12)
FromDay   = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
FromYear  = input(defval = 2018, title = "From Year", minval = 2017)
ToMonth   = input(defval = 1, title = "To Month", minval = 1, maxval = 12)
ToDay     = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
ToYear    = input(defval = 9999, title = "To Year", minval = 2017)

// === FUNCTION EXAMPLE ===
start     = timestamp(FromYear, FromMonth, FromDay, 00, 00)  // backtest start window
finish    = timestamp(ToYear, ToMonth, ToDay, 23, 59)        // backtest finish window
window()  => time >= start and time <= finish ? true : false // create function "within window of time"

// === LOGIC ===
//enterLong = crossover(maFast, maSlow)
//exitLong = crossover(maSlow, maFast)
enterLong = crossover(maSlow, maFast)
exitLong = crossover(maFast, maSlow)


// Entry //
strategy.entry(id="Long Entry", long=true, when=window() and enterLong)
strategy.entry(id="Short Entry", long=false, when=window() and exitLong)

// === FILL ====

fill(fast, slow, color = maFast > maSlow ? green : red)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/SMA-Crossover-Trading-Strategy-436533.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m