Strategy vault / Mean reversion
SMART Professional Quantitative Trading Strategy
This strategy is based on the Smart Money concept using the On-Balance Volume (OBV) indicator to identify institutional fund accumulation and distribution to capture market trends. It goes long when smart money is…
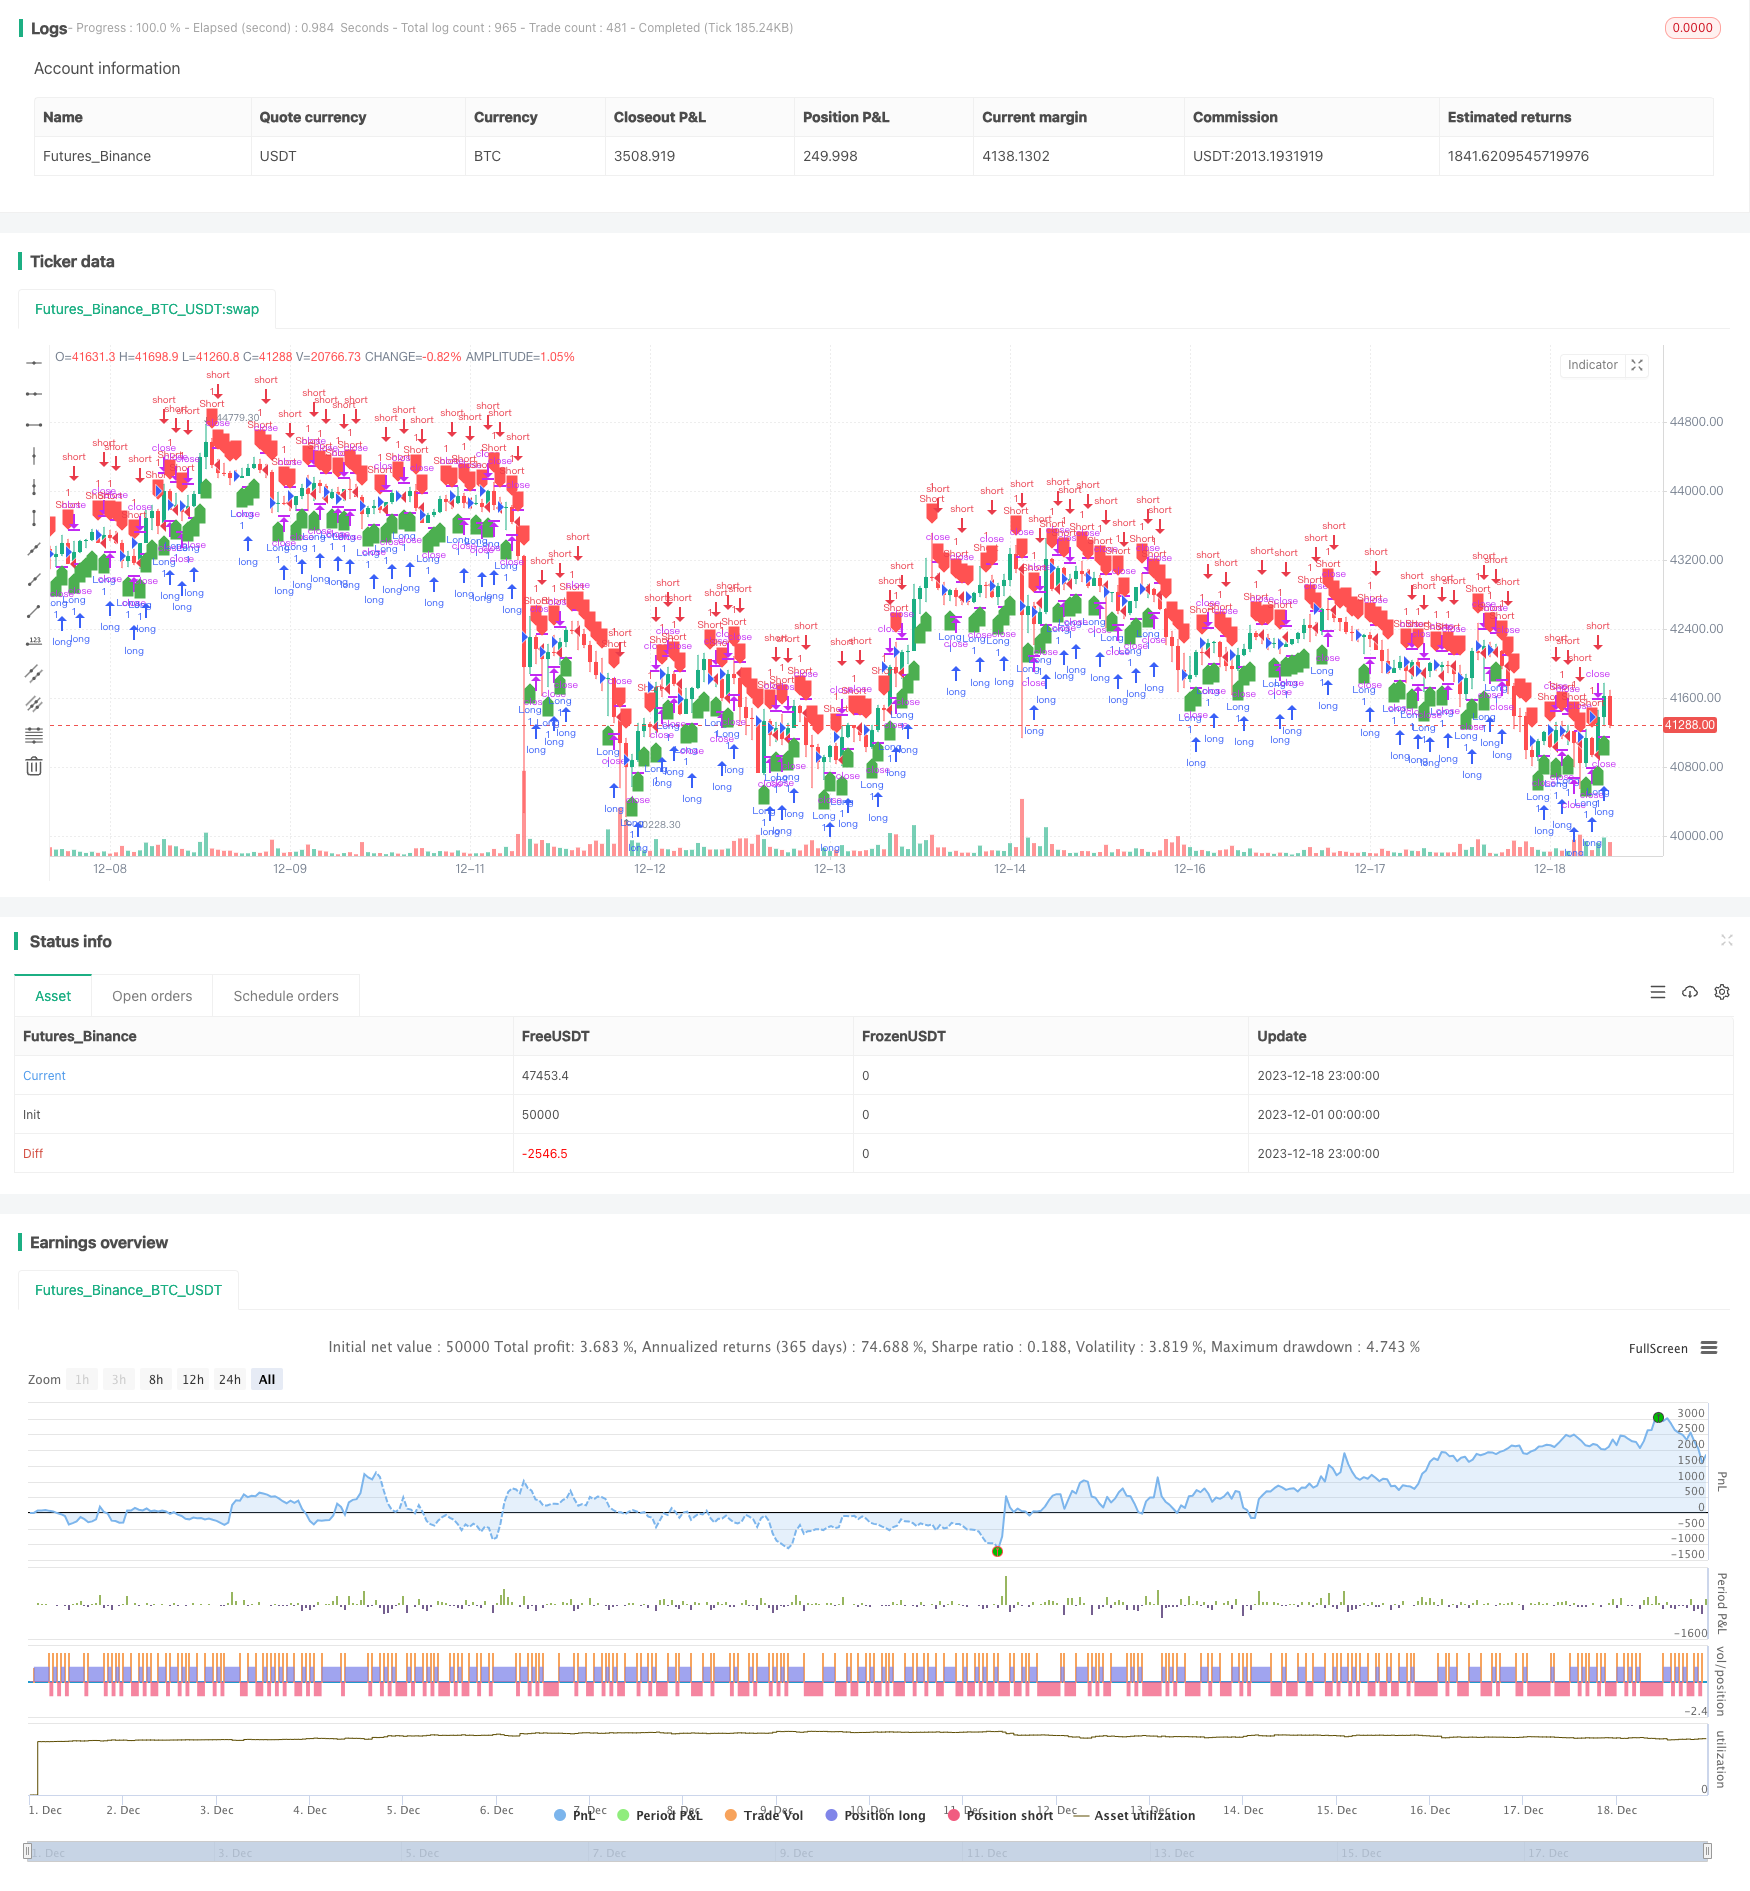
Overview
This strategy is based on the Smart Money concept using the On-Balance Volume (OBV) indicator to identify institutional fund accumulation and distribution to capture market trends. It goes long when smart money is accumulating and goes short when smart money is distributing.
Strategy Logic
On-Balance Volume (OBV)
OBV is a momentum indicator that relates volume to price change. It accumulates volume on up days and subtracts volume on down days.
The strategy uses daily OBV.
Smart Money Conditions
The strategy identifies two main conditions based on OBV slope:
Smart Money Buy Condition: OBV slope > 0, indicating potential smart money accumulation.
Smart Money Sell Condition: OBV slope < 0, indicating potential smart money distribution.
Plotting Signals
Green up arrows and red down arrows represent buy and sell signals.
Entry Logic
Go long when smart money buy condition is met. Go short when smart money sell condition is met.
Exit Logic
When long, if smart money sell signal occurs, close long position. When short, if smart money buy signal occurs, close short position.
Advantage Analysis
Identify market trends using OBV, filtering out market noise.
Precisely capture trend reversals based on institutional fund behavior .
Clear signal rules, easy to implement.
Applicable for any symbol and timeframe.
Risk Analysis
OBV may generate false signals, missing entry/exit timing. Verify signals using other indicators.
Cannot predict extreme events. Use stop loss to control risk.
Difficult to accurately determine institutional behavior, leading to signal deviation. Relax buy/sell conditions.
Optimization
Add other indicators to verify signal reliability e.g. candlestick patterns, Stochastics etc.
Use dynamic or trailing stop loss to control loss per trade.
Test different timeframes and parameter settings to find optimal combination.
Incorporate volume pressure indicator to judge strength of funds inflow/outflow.
Conclusion
The SMART professional quantitative trading strategy identifies institutional fund behavior using OBV to determine market structure and accurately capture trend reversals. Simple and clear signal rules make it easy to implement across any symbol and timeframe. Combining signal verification and appropriate risk control improves strategy robustness and profit factor.
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-18 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Smart Money Concept Strategy", overlay=true)

// Smart Money Concept: On-Balance Volume (OBV)
obv_value = request.security(syminfo.tickerid, "D", close)
obv_slope = obv_value - obv_value[1]

// Define conditions for smart money accumulation/distribution
smart_money_buy_condition = obv_slope > 0
smart_money_sell_condition = obv_slope < 0

// Plot signals
plotshape(series=smart_money_buy_condition, title="Buy Signal", color=color.green, style=shape.labelup, location=location.belowbar)
plotshape(series=smart_money_sell_condition, title="Sell Signal", color=color.red, style=shape.labeldown, location=location.abovebar)

// Strategy Logic
if (smart_money_buy_condition)
    strategy.entry("Long", strategy.long)

if (smart_money_sell_condition)
    strategy.entry("Short", strategy.short)

// Strategy Exit Logic
strategy.close("ExitLong")
strategy.close("ExitShort")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/SMART-Professional-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator EMA StrategyPine Script · Mean reversion · 4h
- Multi factor Quantitative Trading Strategy 440526Pine Script · Mean reversion · 4h
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Automated Market Reversal Trading Strategy Based on Stochastic Indicator and Candlestick PatternsPine Script · Mean reversion · 2m
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h