SMC Market High Low Breakout Strategy
The SMC Market High-Low Breakout Strategy is a quantitative trading strategy based on the principles of Superior Market Concepts (SMC). It identifies significant buying/selling pressure areas (order blocks) on higher…
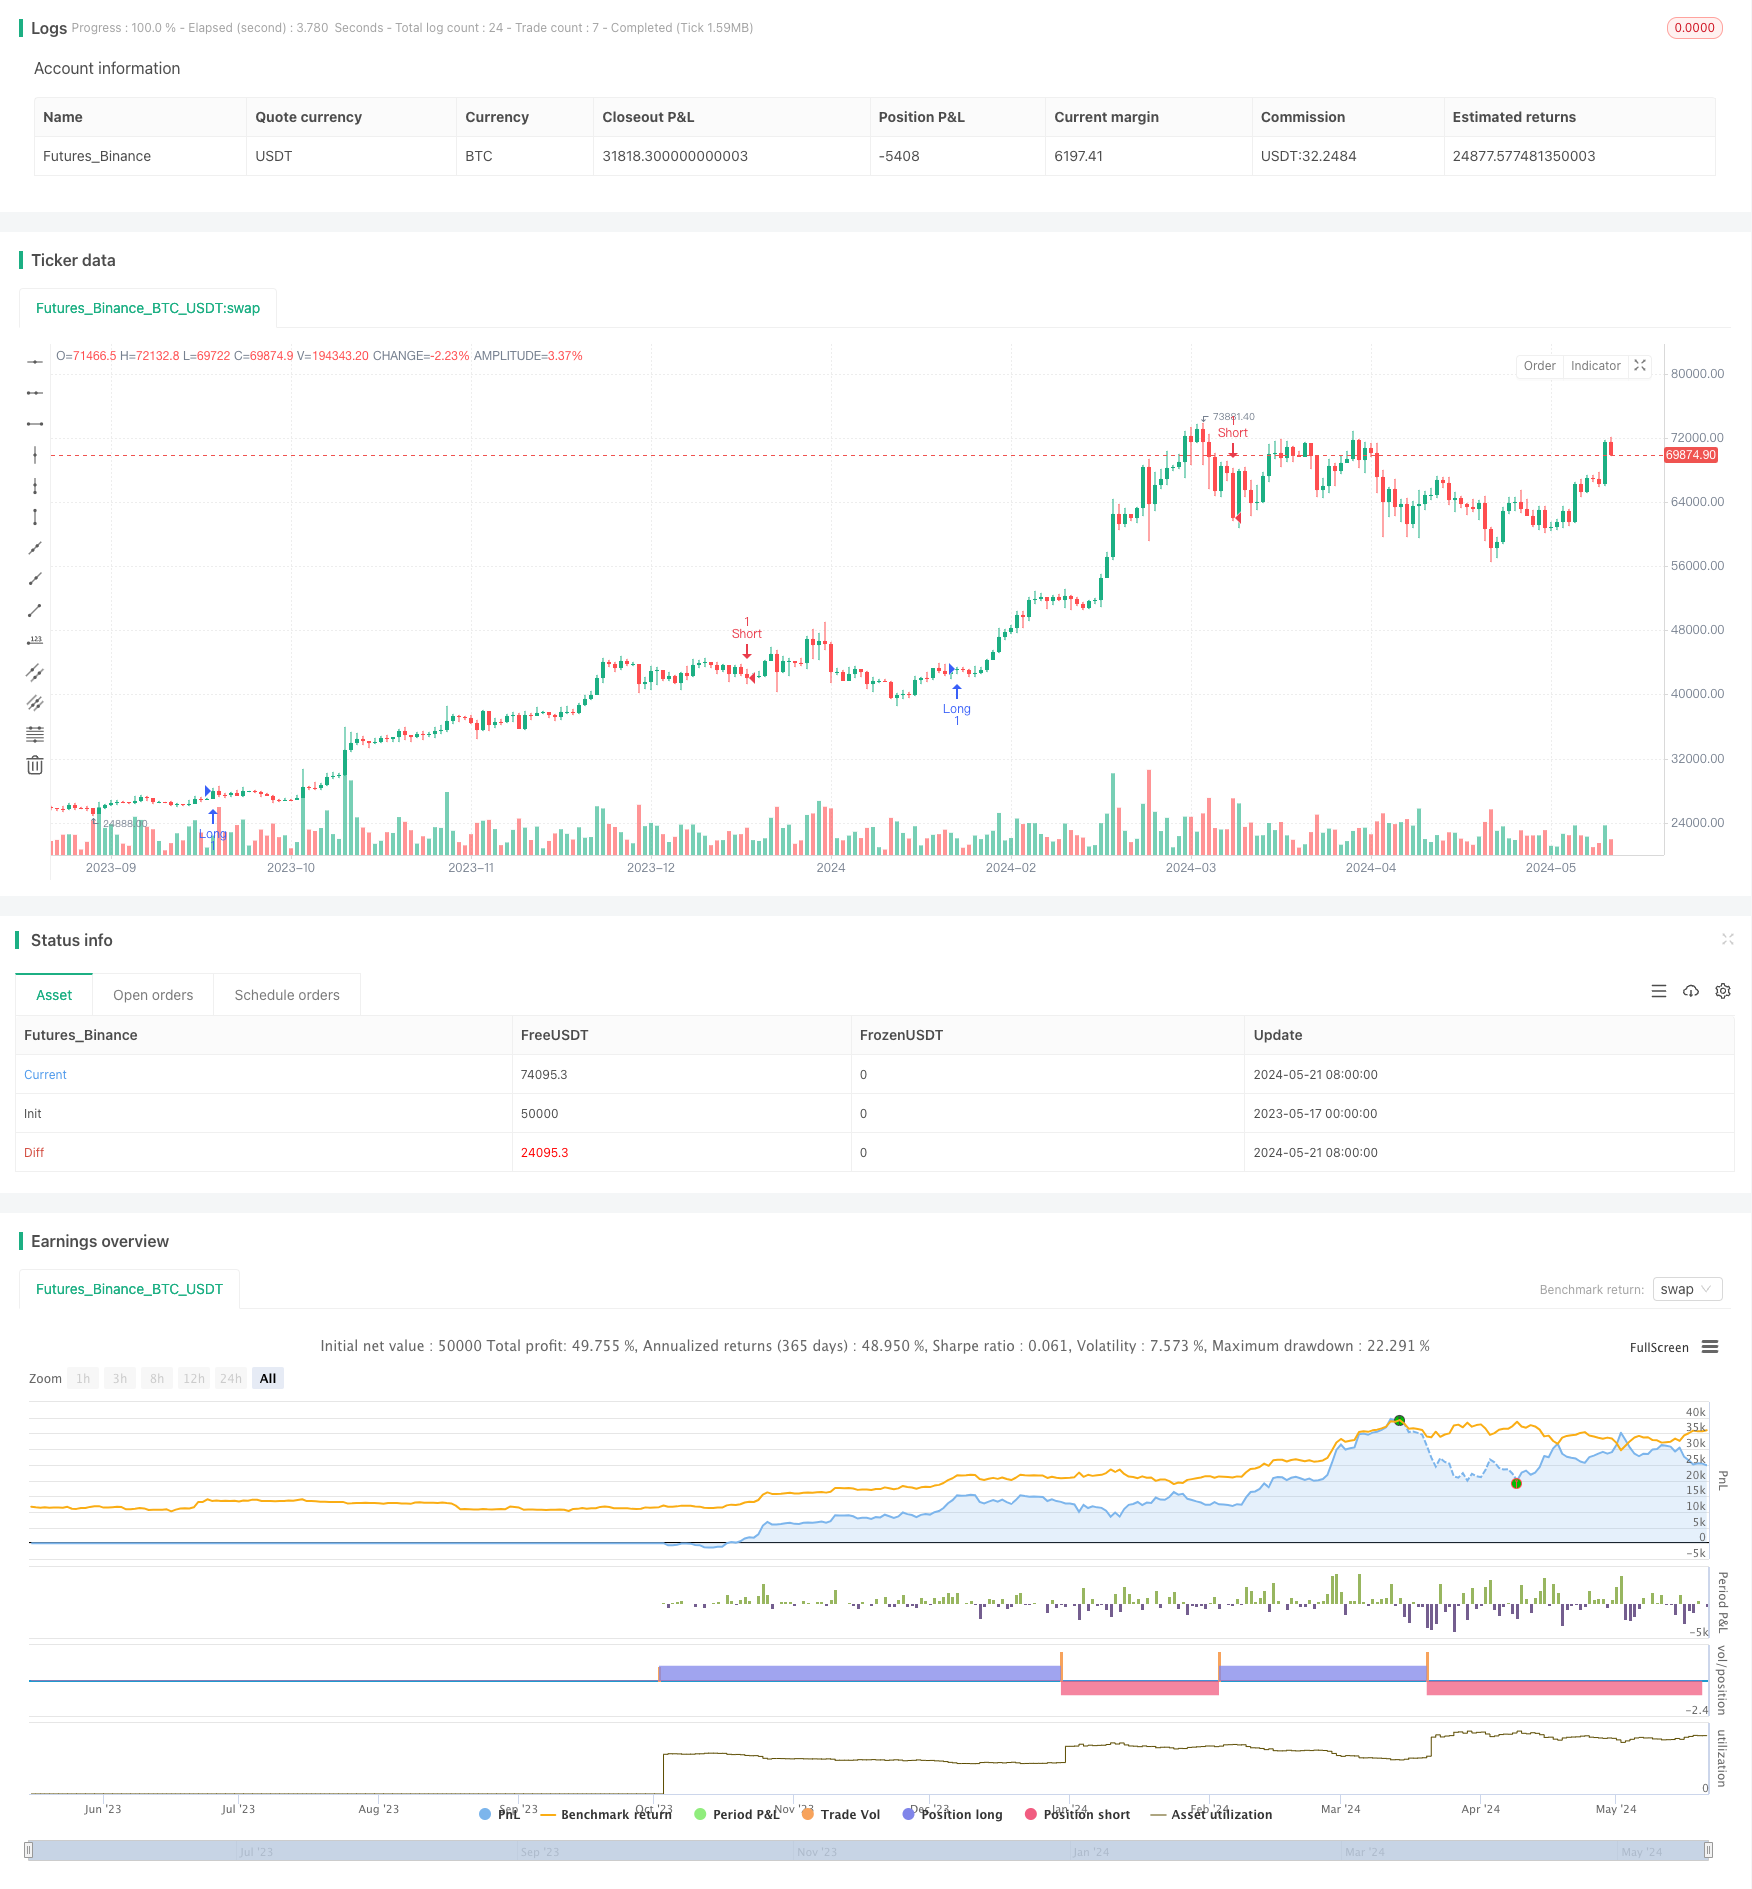
Overview
The SMC Market High-Low Breakout Strategy is a quantitative trading strategy based on the principles of Superior Market Concepts (SMC). It identifies significant buying/selling pressure areas (order blocks) on higher timeframes and seeks optimal breakout entry points on the current timeframe. This aligns with the SMC principle that these blocks often act as support or resistance levels. The strategy considers trend direction, inducement patterns, and risk-reward ratio to optimize entry levels and profit targets.
Strategy Principles
- Identify uptrends and downtrends on the higher timeframe (e.g., 1-hour chart). An uptrend is defined as a higher close and higher low compared to the previous period. A downtrend is the opposite.
- Look for inducement patterns on the higher timeframe. A bullish inducement occurs in an uptrend when the previous high is higher than the highs of the past two and three periods. A bearish inducement occurs in a downtrend when the previous low is lower than the lows of the past two and three periods.
- Identify order blocks on the higher timeframe. After a bullish inducement, the high and low of that period define the upper and lower boundaries of the order block. The opposite applies to a bearish inducement.
- Find optimal entry points on the current timeframe (e.g., 15-minute chart). A long entry occurs when the current close breaks above the lower boundary of the order block, and the previous close is within the block. A short entry occurs when the close breaks below the upper boundary.
- Set stop-loss and take-profit levels. The stop-loss is placed at the boundary of the order block, while the take-profit is calculated based on the set risk-reward ratio (e.g., 1:1.5).
Strategy Advantages
- Based on SMC principles, it captures major trends and key support/resistance levels on higher timeframes, avoiding noise interference on lower timeframes.
- Identifying inducement patterns helps gauge trend strength and sustainability, providing more basis for entry.
- Precise breakout entries on the current timeframe reduce false signals and drawdown risks.
- Flexible risk-reward ratio settings can be adjusted according to individual risk preferences.
Strategy Risks
- During market consolidation or early trend reversals, the strategy may face drawdown risks.
- In extreme market conditions (e.g., sharp rises or falls), order blocks may become invalid, leading to overly loose stop-losses.
- Considering only price action and ignoring other important indicators like volume may lead to biased judgments.
Strategy Optimization Directions
- Introduce more higher timeframes (e.g., daily, weekly) for filtering to ensure capturing long-term trends.
- Combine moving average systems, momentum indicators, etc., to improve the accuracy of trend and inducement pattern identification.
- Dynamically optimize order block boundaries, such as considering Average True Range (ATR) or channel width, to adapt to different market conditions.
- Implement trailing stop-losses after entry, such as tracking ATR or Parabolic SAR, to reduce holding risks.
- Consider market sentiment indicators (e.g., VIX) or macroeconomic data to identify potential trend reversals or black swan events.
Summary
The SMC Market High-Low Breakout Strategy is a quantitative trading strategy based on SMC principles. It identifies key pressure areas on higher timeframes and seeks optimal breakout entry points on the current timeframe. The strategy comprehensively considers trend direction, inducement patterns, and risk-reward ratio to optimize entry levels and profit targets. Its advantages lie in filtering out noise based on higher timeframes, precisely capturing trends, and providing flexible risk management features. However, the strategy may face drawdown risks during market consolidation or early trend reversals. Future optimizations can introduce more timeframes, optimize order block boundaries, implement dynamic stop-losses, and consider market sentiment to improve the strategy's robustness and adaptability.
Source Pine Script
//@version=5
strategy("SMC Indian Market Strategy", overlay=true)

// Input Parameters
htf = input.timeframe("60", title="Higher Timeframe")  // For Inducement & Order Block
riskRewardRatio = input.float(1.5, title="Risk:Reward Ratio", minval=0.1)

// Higher Timeframe Data
[htfOpen, htfHigh, htfLow, htfClose] = request.security(syminfo.tickerid, htf, [open, high, low, close])

// Trend Identification (HTF)
bool htfUptrend = htfClose > htfClose[1] and htfLow > htfLow[1]  // Price action
bool htfDowntrend = htfClose < htfClose[1] and htfHigh < htfHigh[1]

// Inducement Identification (HTF)
bool htfInducementHigh = htfUptrend and high[1] > high[2] and high[1] > high[3]
bool htfInducementLow = htfDowntrend and low[1] < low[2] and low[1] < low[3]
float inducementLevel = htfInducementHigh ? high[1] : htfInducementLow ? low[1] : na

// Order Block Identification (HTF)
var float htfOBHigh = na // Highest high within the order block
var float htfOBLow = na  // Lowest low within the order block

if htfInducementHigh
    htfOBHigh := htfHigh
    htfOBLow := htfLow
else if htfInducementLow
    htfOBHigh := htfHigh
    htfOBLow := htfLow

// Optimal Entry (Current Timeframe)
bool longEntry = htfUptrend and close > htfOBLow and close[1] < htfOBLow  // Break of OB low
bool shortEntry = htfDowntrend and close < htfOBHigh and close[1] > htfOBHigh  // Break of OB high

// Stop Loss and Take Profit
float longSL = htfOBLow
float longTP = close + (close - longSL) * riskRewardRatio
float shortSL = htfOBHigh
float shortTP = close - (shortSL - close) * riskRewardRatio

// Strategy Execution
if longEntry
    strategy.entry("Long", strategy.long, stop=longSL, limit=longTP)
else if shortEntry
    strategy.entry("Short", strategy.short, stop=shortSL, limit=shortTP)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-05-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/SMC-Market-High-Low-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands Breakout Trading StrategyPine Script · Breakout · 1h
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Cross period Value Area Breakout StrategyPine Script · Breakout · 1d
- Donchian Channel Breakout Strategy 442842Pine Script · Breakout · 4h
- Dynamic Support Resistance Breakout Moving Average Crossover StrategyPine Script · Breakout · 1d
- Dynamic Support and Resistance Adaptive Pivot Trading StrategyPine Script · Breakout · 1d