Statistical Dual Standard Deviation VWAP Breakout Trading Strategy
This strategy is a trend breakout system based on VWAP (Volume Weighted Average Price) and standard deviation channels. It constructs a dynamic price range by calculating VWAP and standard deviation bands to capture…
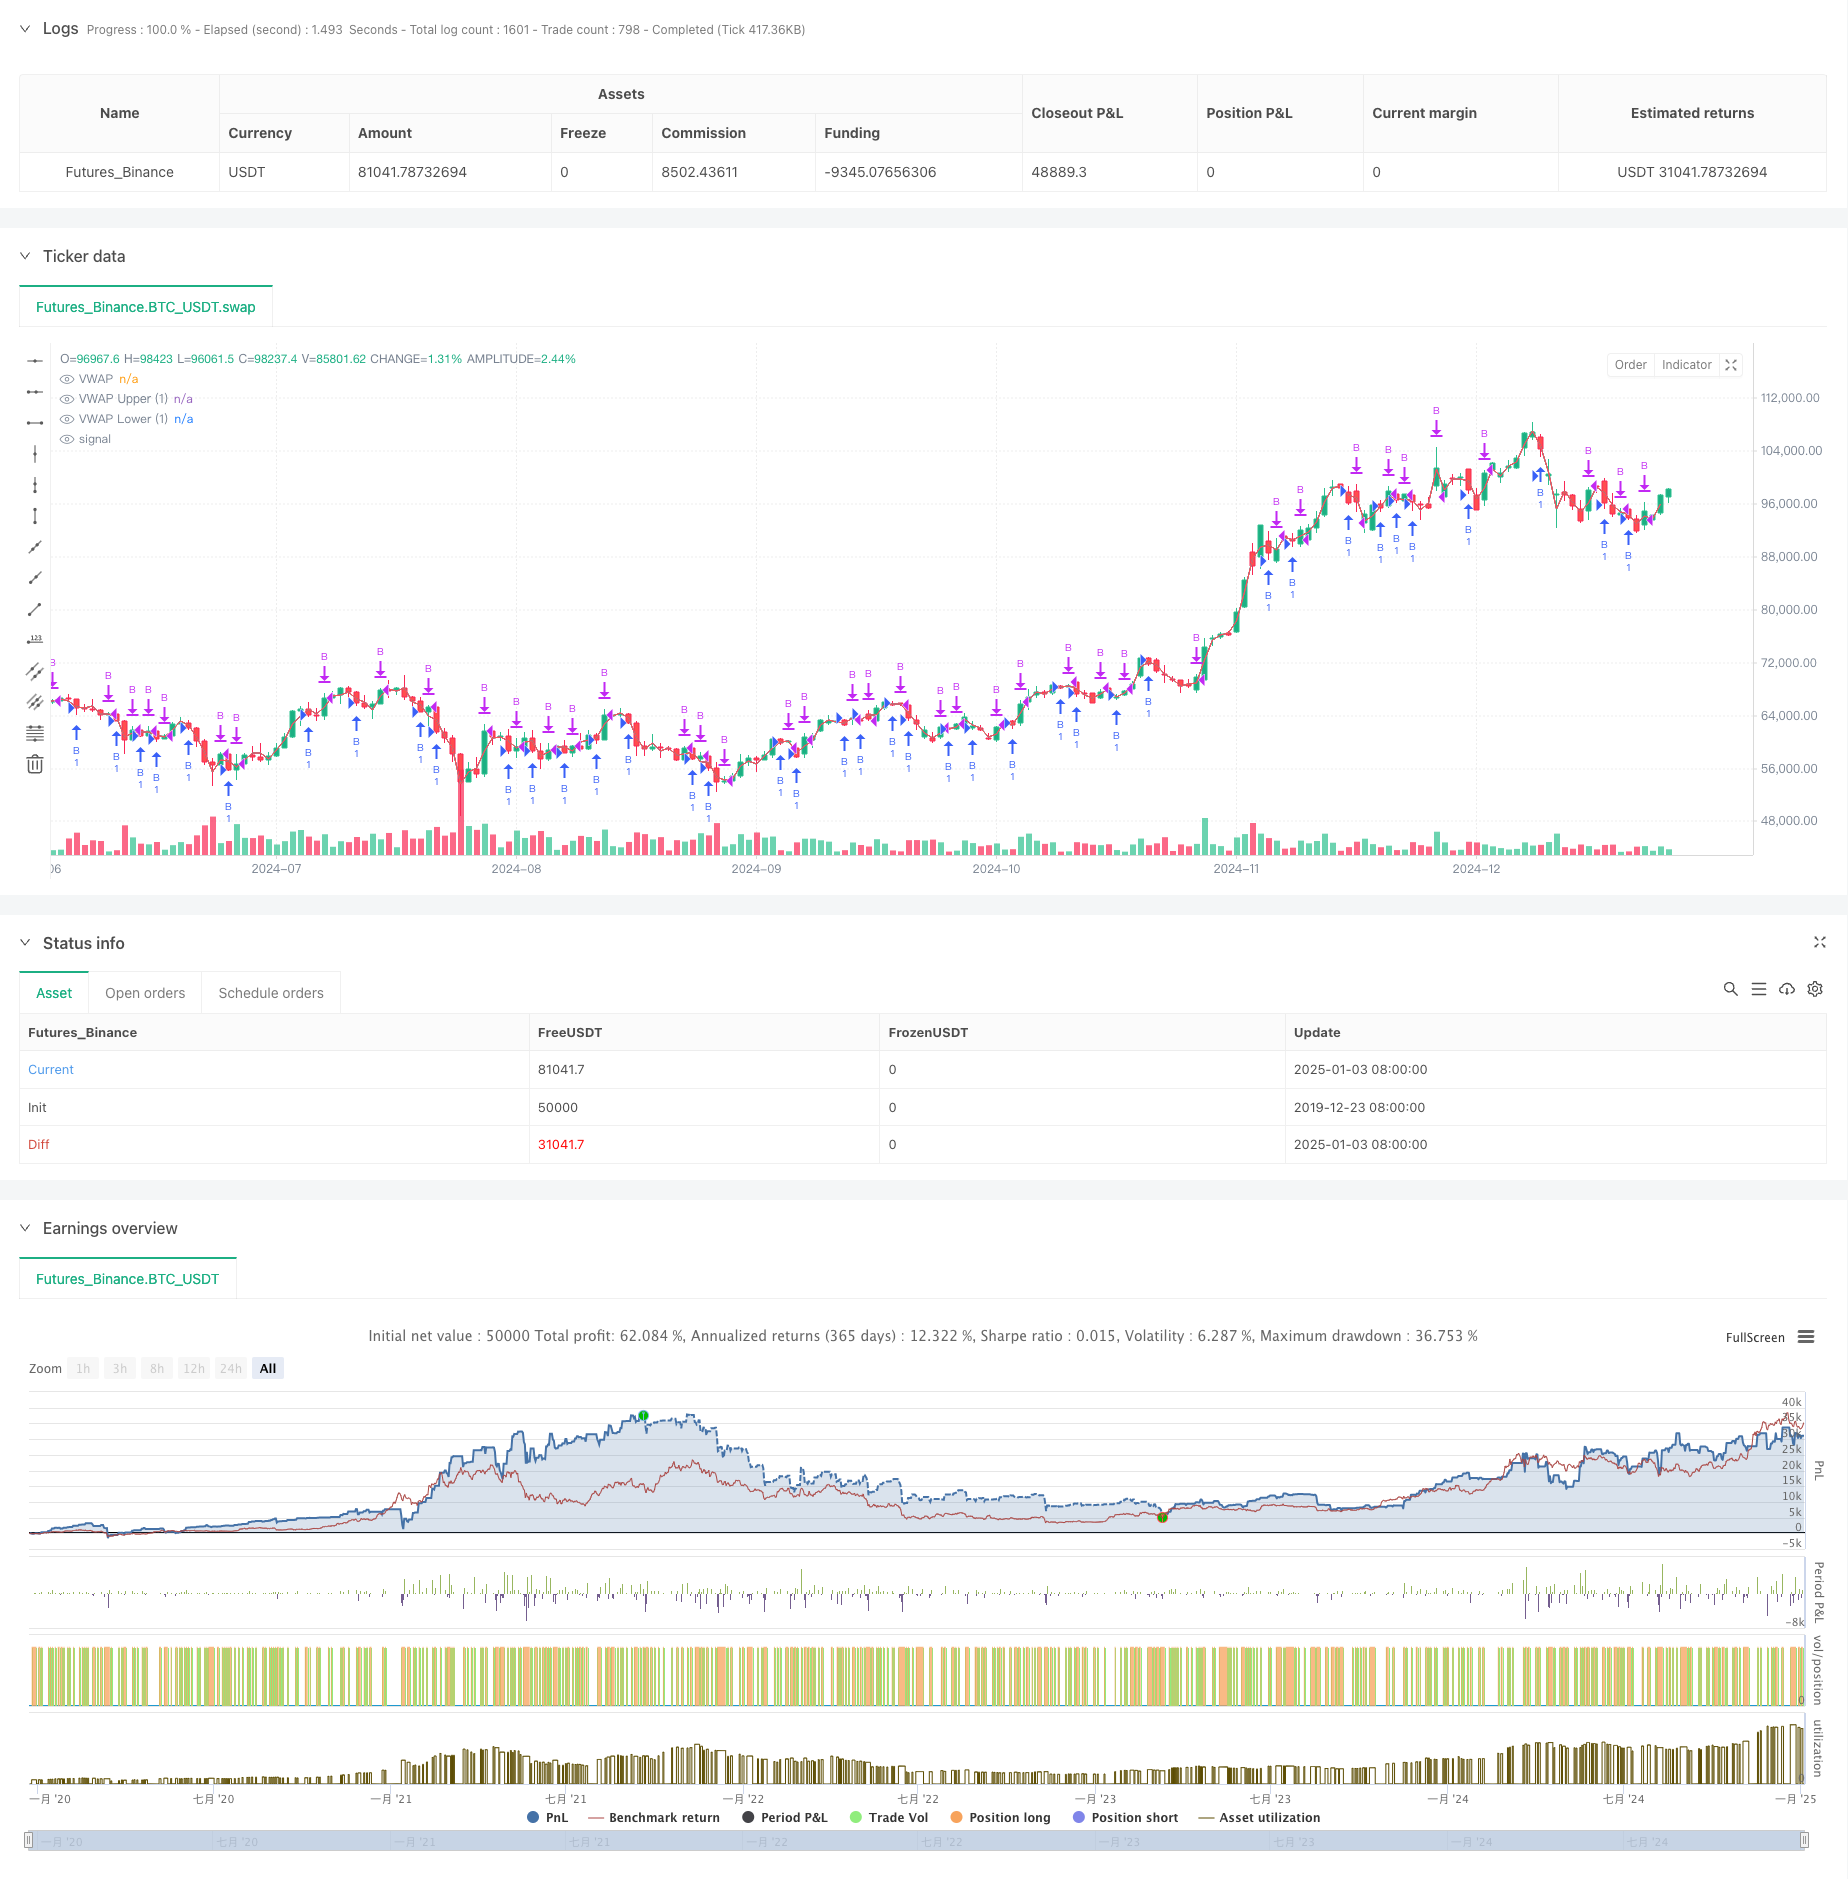
Overview
This strategy is a trend breakout system based on VWAP (Volume Weighted Average Price) and standard deviation channels. It constructs a dynamic price range by calculating VWAP and standard deviation bands to capture upward breakout opportunities. The strategy mainly relies on standard deviation band breakthrough signals for trading, with profit targets and order intervals to control risk.
Strategy Principles
- Core Indicator Calculation:
- Calculate VWAP using intraday HL2 prices and volume
- Compute standard deviation based on price volatility
- Set 1.28 times standard deviation upper and lower bands
- Trading Logic:
- Entry condition: price crosses below lower band then rises above it
- Exit condition: reaches preset profit target
- Minimum order interval to avoid frequent trading
Strategy Advantages
- Statistical Foundation
- VWAP-based price center reference
- Volatility measurement using standard deviation
- Dynamic trading range adjustment
- Risk Control
- Fixed profit target setting
- Trading frequency control
- Long-only strategy reduces risk
Strategy Risks
- Market Risks
- False breakouts during high volatility
- Difficulty in accurately timing trend reversals
- Increased losses in downtrend markets
- Parameter Risks
- Sensitivity to standard deviation multiplier settings
- Profit target optimization needed
- Trading interval affects performance
Optimization Directions
- Signal Optimization
- Add trend filter
- Incorporate volume change confirmation
- Include additional technical indicators
- Risk Management Optimization
- Dynamic stop-loss placement
- Position sizing based on volatility
- Enhanced order management system
Summary
This is a quantitative trading strategy combining statistical principles and technical analysis. Through the combination of VWAP and standard deviation bands, it builds a relatively reliable trading system. The core advantages lie in its scientific statistical foundation and comprehensive risk control mechanisms, but continuous optimization of parameters and trading logic is still needed in practical applications.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-04 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("VWAP Stdev Bands Strategy (Long Only)", overlay=true)

// Standard Deviation Inputs
devUp1 = input.float(1.28, title="Stdev above (1)")
devDn1 = input.float(1.28, title="Stdev below (1)")

// Show Options
showPrevVWAP = input(false, title="Show previous VWAP close?")
profitTarget = input.float(2, title="Profit Target ($)", minval=0) // Profit target for closing orders
gapMinutes = input.int(15, title="Gap before new order (minutes)", minval=0) // Gap for placing new orders

// VWAP Calculation
var float vwapsum = na
var float volumesum = na
var float v2sum = na
var float prevwap = na // Track the previous VWAP
var float lastEntryPrice = na // Track the last entry price
var int lastEntryTime = na // Track the time of the last entry

start = request.security(syminfo.tickerid, "D", time)
newSession = ta.change(start)

vwapsum := newSession ? hl2 * volume : vwapsum[1] + hl2 * volume
volumesum := newSession ? volume : volumesum[1] + volume
v2sum := newSession ? volume * hl2 * hl2 : v2sum[1] + volume * hl2 * hl2

myvwap = vwapsum / volumesum
dev = math.sqrt(math.max(v2sum / volumesum - myvwap * myvwap, 0))

// Calculate Upper and Lower Bands
lowerBand1 = myvwap - devDn1 * dev
upperBand1 = myvwap + devUp1 * dev

// Plot VWAP and Bands with specified colors
plot(myvwap, style=plot.style_line, title="VWAP", color=color.green, linewidth=1)
plot(upperBand1, style=plot.style_line, title="VWAP Upper (1)", color=color.blue, linewidth=1)
plot(lowerBand1, style=plot.style_line, title="VWAP Lower (1)", color=color.red, linewidth=1)

// Trading Logic (Long Only)
longCondition = close < lowerBand1 and close[1] >= lowerBand1 // Price crosses below the lower band

// Get the current time in minutes
currentTime = timestamp("GMT-0", year(timenow), month(timenow), dayofmonth(timenow), hour(timenow), minute(timenow))

// Check if it's time to place a new order based on gap
canPlaceNewOrder = na(lastEntryTime) or (currentTime - lastEntryTime) >= gapMinutes * 60 * 1000

// Close condition based on profit target
if (strategy.position_size > 0)
    if (close - lastEntryPrice >= profitTarget)
        strategy.close("B")
        lastEntryTime := na // Reset last entry time after closing

// Execute Long Entry
if (longCondition and canPlaceNewOrder)
    strategy.entry("B", strategy.long)
    lastEntryPrice := close // Store the entry price
    lastEntryTime := currentTime // Update the last entry time

    // Add label for the entry
    label.new(bar_index, close, "B", style=label.style_label_down, color=color.green, textcolor=color.white, size=size.small)

// Optional: Plot previous VWAP for reference
prevwap := newSession ? myvwap[1] : prevwap[1]
plot(showPrevVWAP ? prevwap : na, style=plot.style_circles, color=close > prevwap ? color.green : color.red)Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Statistical-Dual-Standard-Deviation-VWAP-Breakout-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- LPB Microcycles Adaptive Oscillation Contour Tracking StrategyPine Script · Breakout · 1h
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Multi factor Intelligent Trading StrategyPine Script · Breakout · 1d
- Quantitative Breakout Strategy First Hour ATR Stop Loss with EMA Slope OptimizationPine Script · Breakout · 1h
- RSI VWAP Short term Quant StrategyPine Script · Breakout · 1h
- Dynamic Buying Selling Volume Breakout StrategyPine Script · Breakout · 1d