Stochastic Momentum Strategy
The Stochastic Momentum Strategy is a quantitative trading strategy that combines the Stochastic Momentum Index (SMI) and the Relative Strength Index (RSI). It uses the SMI to identify overbought and oversold areas…
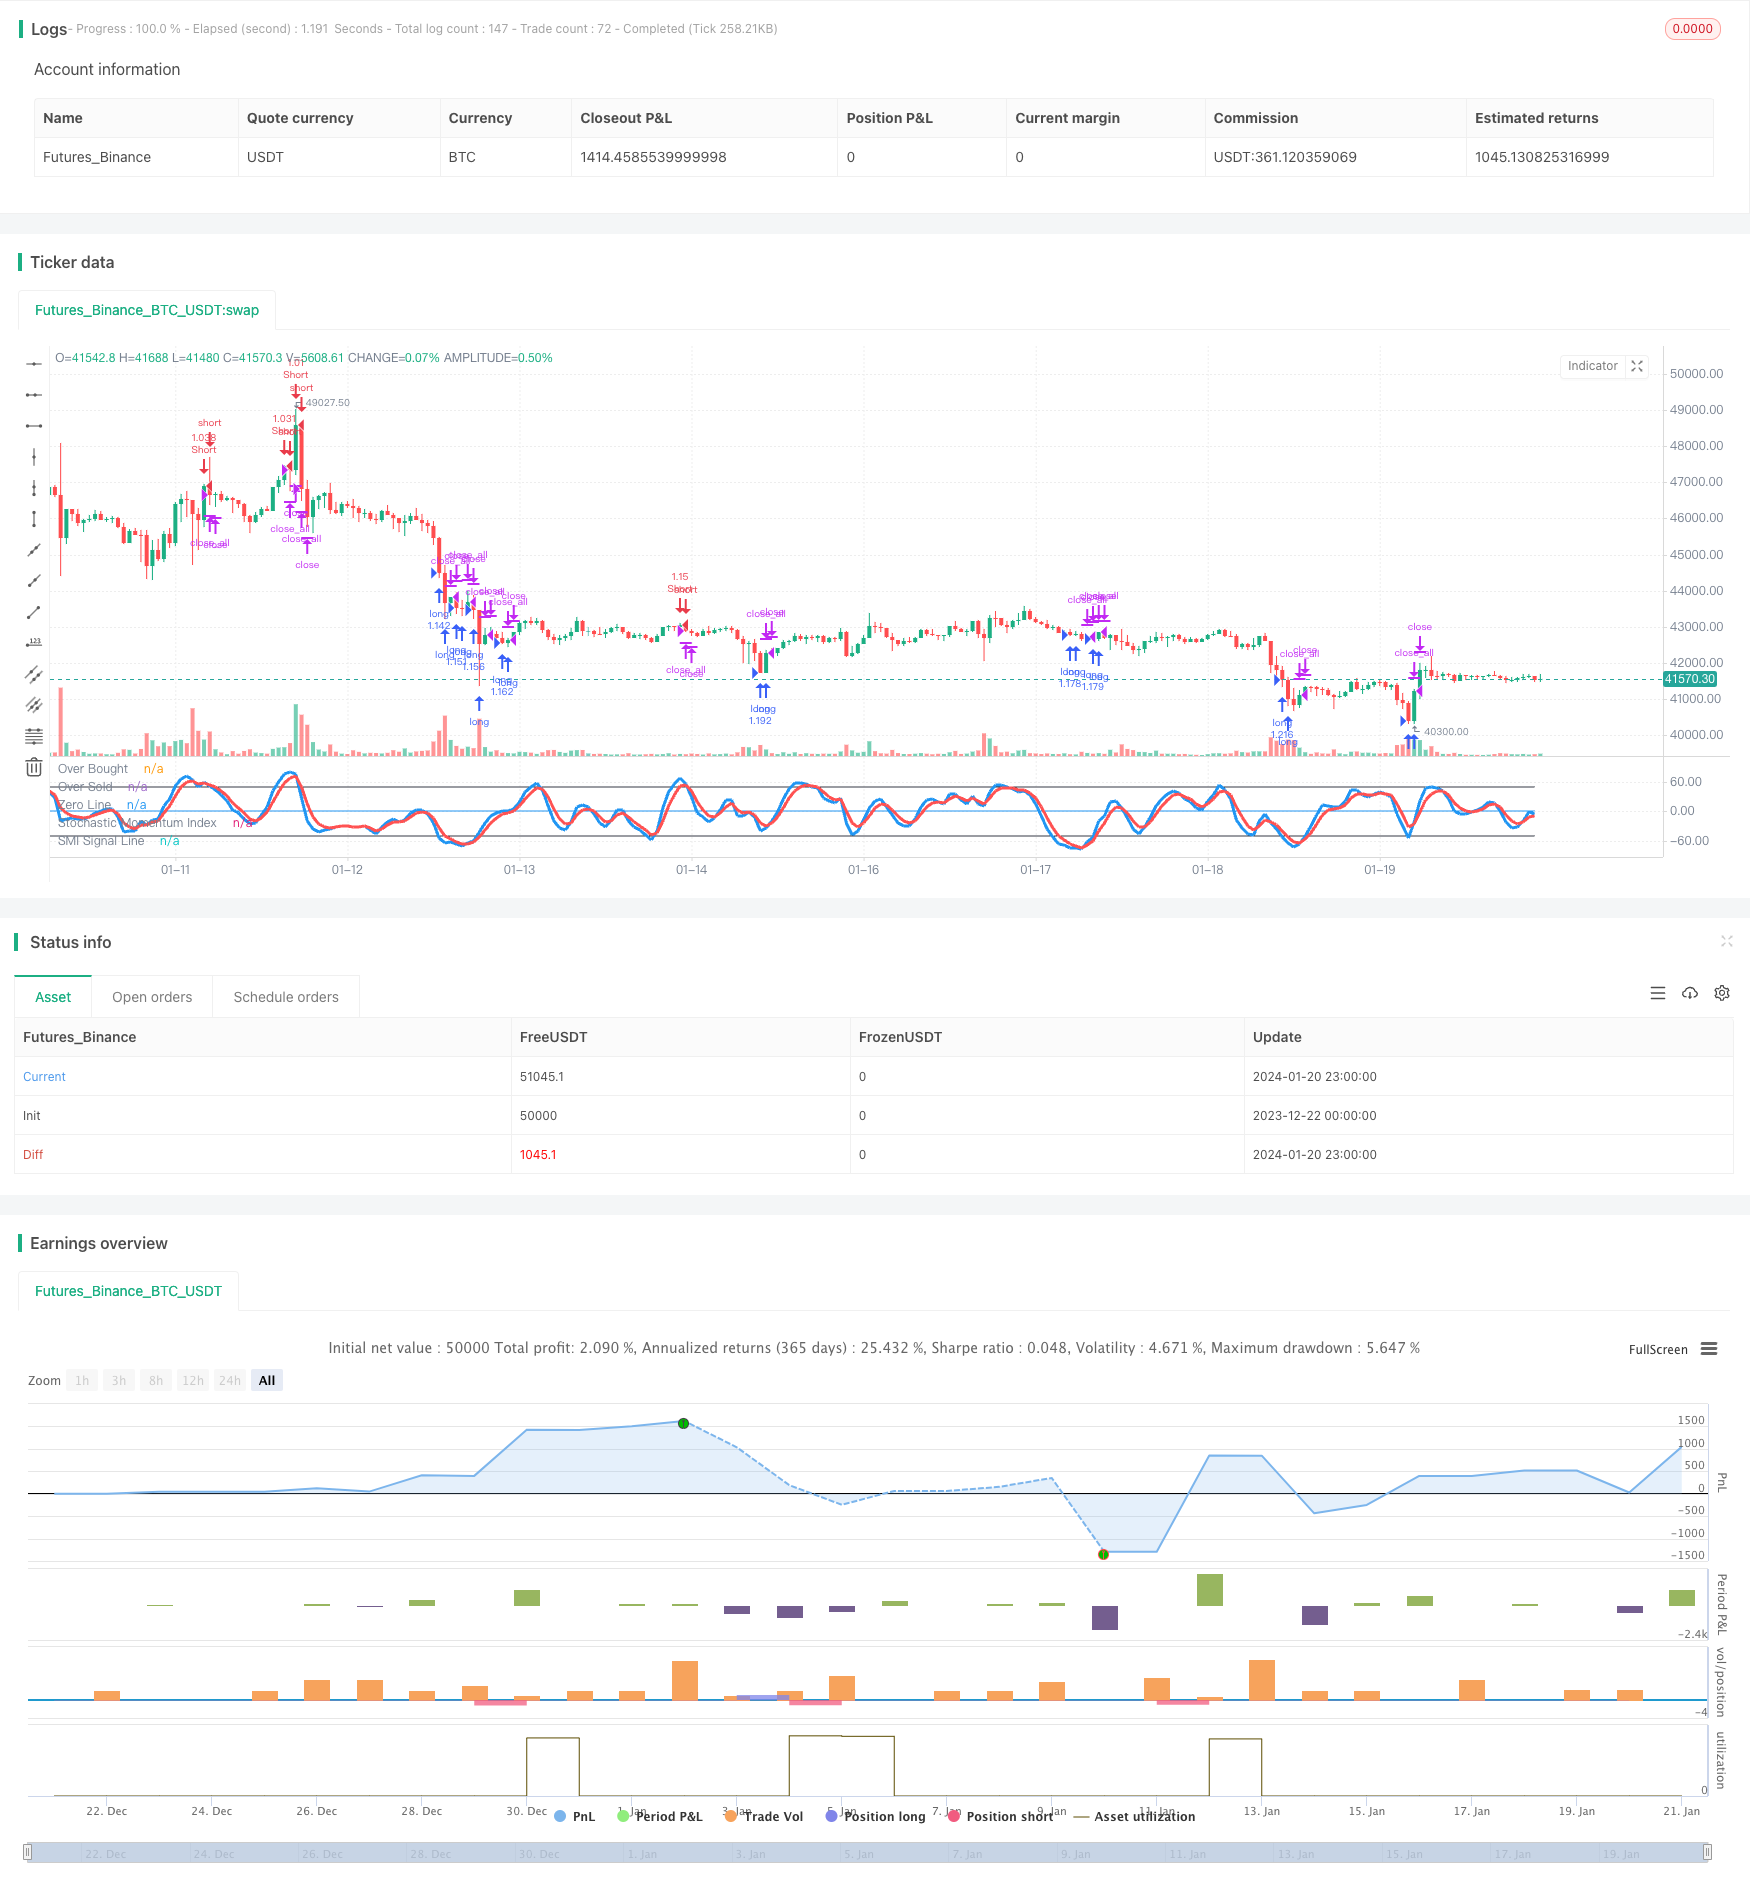
Overview
The Stochastic Momentum Strategy is a quantitative trading strategy that combines the Stochastic Momentum Index (SMI) and the Relative Strength Index (RSI). It uses the SMI to identify overbought and oversold areas in the market, with the fast RSI acting as a signal filter. It also implements a body filter for more reliable signal selection.
Strategy Principles
Stochastic Momentum Index
The Stochastic Momentum Index (SMI) is a common technical indicator used in quantitative trading that combines the strengths of momentum and oscillation indicators.
Specifically, the SMI is calculated as:
SMI = (Close - (HH + LL)/2)/(0.5*(HH - LL)) * 100
where HH is the highest price over the past N days, and LL is the lowest price.
So the SMI incorporates both the trend-following judgment of momentum and the reversal judgment of oscillation. Values above 80 are considered overbought, while values below 20 are oversold. The strategy generates trading signals when SMI reaches these overbought or oversold levels.
Fast RSI
The Relative Strength Index (RSI) is a standard overbought/oversold indicator. This strategy uses a fast RSI with a period of 7 to judge short-term overbought/oversold conditions.
Readings below 20 are considered oversold, while those above 80 are deemed overbought per the fast RSI. Signals are generated when these thresholds are breached.
Body Filter
The strategy also implements a body filter by checking the candlestick body size to filter certain signals. Only bodies exceeding a set threshold will trigger trades.
This filters out some false signals and increases reliability.
Advantages
Multi-Indicator Combo
This approach combines the SMI, fast RSI, and body filter into a robust 3-part system. Using multiple integrated signals improves accuracy and enhances stability.
Overbought/Oversold Detection
Both SMI and fast RSI are excellent for detecting exhausted trends. By trading mean-reversions from these overextended areas, the strategy adheres to buying low and selling high.
Two-Way Trading
The ability to both buy dips and short rallies maximizes opportunities across market conditions.
Risk Control
The body filter avoids whipsaws by rejecting low-conviction signals in choppy conditions.
Risks
Whipsaws
Frequent long/short switching brings whipsaw risk. Optimizing logic could minimize this.
Crowded Trades
Signals may cluster market participants and spur quick reversals upon entry. Fine-tuning parameters could reduce herding risk.
Black Swans
Extreme events can upend all models. Intelligent stop losses are necessary to control systematic risks.
Enhancements
Parameter Optimization
Testing different SMI/RSI periods and body filter thresholds could uncover optimal values for higher returns.
Dynamic Stops
Incorporating volatility-based or ATR stops would better contain position and portfolio risk.
Machine Learning
Models predicting future indicator levels could identify turning points earlier. This would enhance predictive power.
Conclusion
In summary, by integrating the SMI, fast RSI, and body filter, this strategy has created a fairly comprehensive overbought/oversold system. The multi-signal approach improves accuracy, while two-way trade capability and risk controls contribute to balance. With continual parameter and model optimization, it shows promise for capturing gains over the long run.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | false | Use Martingale |
| v_input_4 | 100 | Capital, % |
| v_input_5 | true | Use SMI Strategy |
| v_input_6 | true | Use RSI Strategy |
| v_input_7 | true | Use Body-Filter |
| v_input_8 | 5 | SMI Percent K Length |
| v_input_9 | 3 | SMI Percent D Length |
| v_input_10 | 50 | SMI Limit |
| v_input_11 | 2017 | From Year |
| v_input_12 | 2100 | To Year |
| v_input_13 | true | From Month |
| v_input_14 | 12 | To Month |
| v_input_15 | true | From day |
| v_input_16 | 31 | To day |
Source Pine Script
/*backtest
start: 2023-12-22 00:00:00
end: 2024-01-21 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2018

//@version=2
strategy(title = "Noro's Stochastic Strategy v1.1", shorttitle = "Stochastic str 1.1", overlay = false, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 0)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
usemar = input(false, defval = false, title = "Use Martingale")
capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Capital, %")
usesmi = input(true, defval = true, title = "Use SMI Strategy")
usersi = input(true, defval = true, title = "Use RSI Strategy")
usebod = input(true, defval = true, title = "Use Body-Filter")
a = input(5, "SMI Percent K Length")
b = input(3, "SMI Percent D Length")
limit = input(50, defval = 50, minval = 1, maxval = 100, title = "SMI Limit")
fromyear = input(2017, defval = 2017, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Fast RSI
fastup = rma(max(change(close), 0), 7)
fastdown = rma(-min(change(close), 0), 7)
fastrsi = fastdown == 0 ? 100 : fastup == 0 ? 0 : 100 - (100 / (1 + fastup / fastdown))

//Stochastic Momentum Index
ll = lowest (low, a)
hh = highest (high, a)
diff = hh - ll
rdiff = close - (hh+ll)/2
avgrel = ema(ema(rdiff,b),b)
avgdiff = ema(ema(diff,b),b)
SMI = avgdiff != 0 ? (avgrel/(avgdiff/2)*100) : 0
SMIsignal = ema(SMI,b)

//Lines
plot(SMI, color = blue, linewidth = 3, title = "Stochastic Momentum Index")
plot(SMIsignal, color = red, linewidth = 3, title = "SMI Signal Line")
plot(limit, color = black, title = "Over Bought")
plot(-1 * limit, color = black, title = "Over Sold")
plot(0, color = blue, title = "Zero Line")

//Body Filter
nbody = abs(close - open)
abody = sma(nbody, 10)
body = nbody > abody / 3 or usebod == false

//Signals
up1 = SMIsignal < -1 * limit and close < open and body and usesmi
dn1 = SMIsignal > limit and close > open and body and usesmi
up2 = fastrsi < 20 and close < open and body and usersi
dn2 = fastrsi > 80 and close > open and body and usersi
exit = ((strategy.position_size > 0 and close > open) or (strategy.position_size < 0 and close < open)) and body

//Trading
profit = exit ? ((strategy.position_size > 0 and close > strategy.position_avg_price) or (strategy.position_size < 0 and close < strategy.position_avg_price)) ? 1 : -1 : profit[1]
mult = usemar ? exit ? profit == -1 ? mult[1] * 2 : 1 : mult[1] : 1
lot = strategy.position_size == 0 ? strategy.equity / close * capital / 100 * mult : lot[1]

if up1 or up2
    if strategy.position_size < 0
        strategy.close_all()

    strategy.entry("long", strategy.long, needlong == false ? 0 : lot, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if dn1 or dn2
    if strategy.position_size > 0
        strategy.close_all()

    strategy.entry("Short", strategy.short, needshort == false ? 0 : lot, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if time > timestamp(toyear, tomonth, today, 23, 59) or exit
strategy.close_all()Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Stochastic-Momentum-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h
- Multi factor Adaptive Momentum Tracking StrategyPine Script · Momentum · 3m
- Stochastic Momentum Index and RSI Based Quant Trading StrategyPine Script · Momentum · 5m
- Dual Momentum Oscillator Smart Timing Trading StrategyPine Script · Momentum · 1h
- Momentum Trading Strategy Based on Multi factor ModelPine Script · Momentum · 1d