Strategy vault / Mean reversion
Stochastic OTT Trading Strategy
This strategy combines stochastic oscillator and OTT indicators to generate trading signals. It will trigger orders when fast and slow OTT lines cross. To filter fake signals, stochastic oscillator is used for…
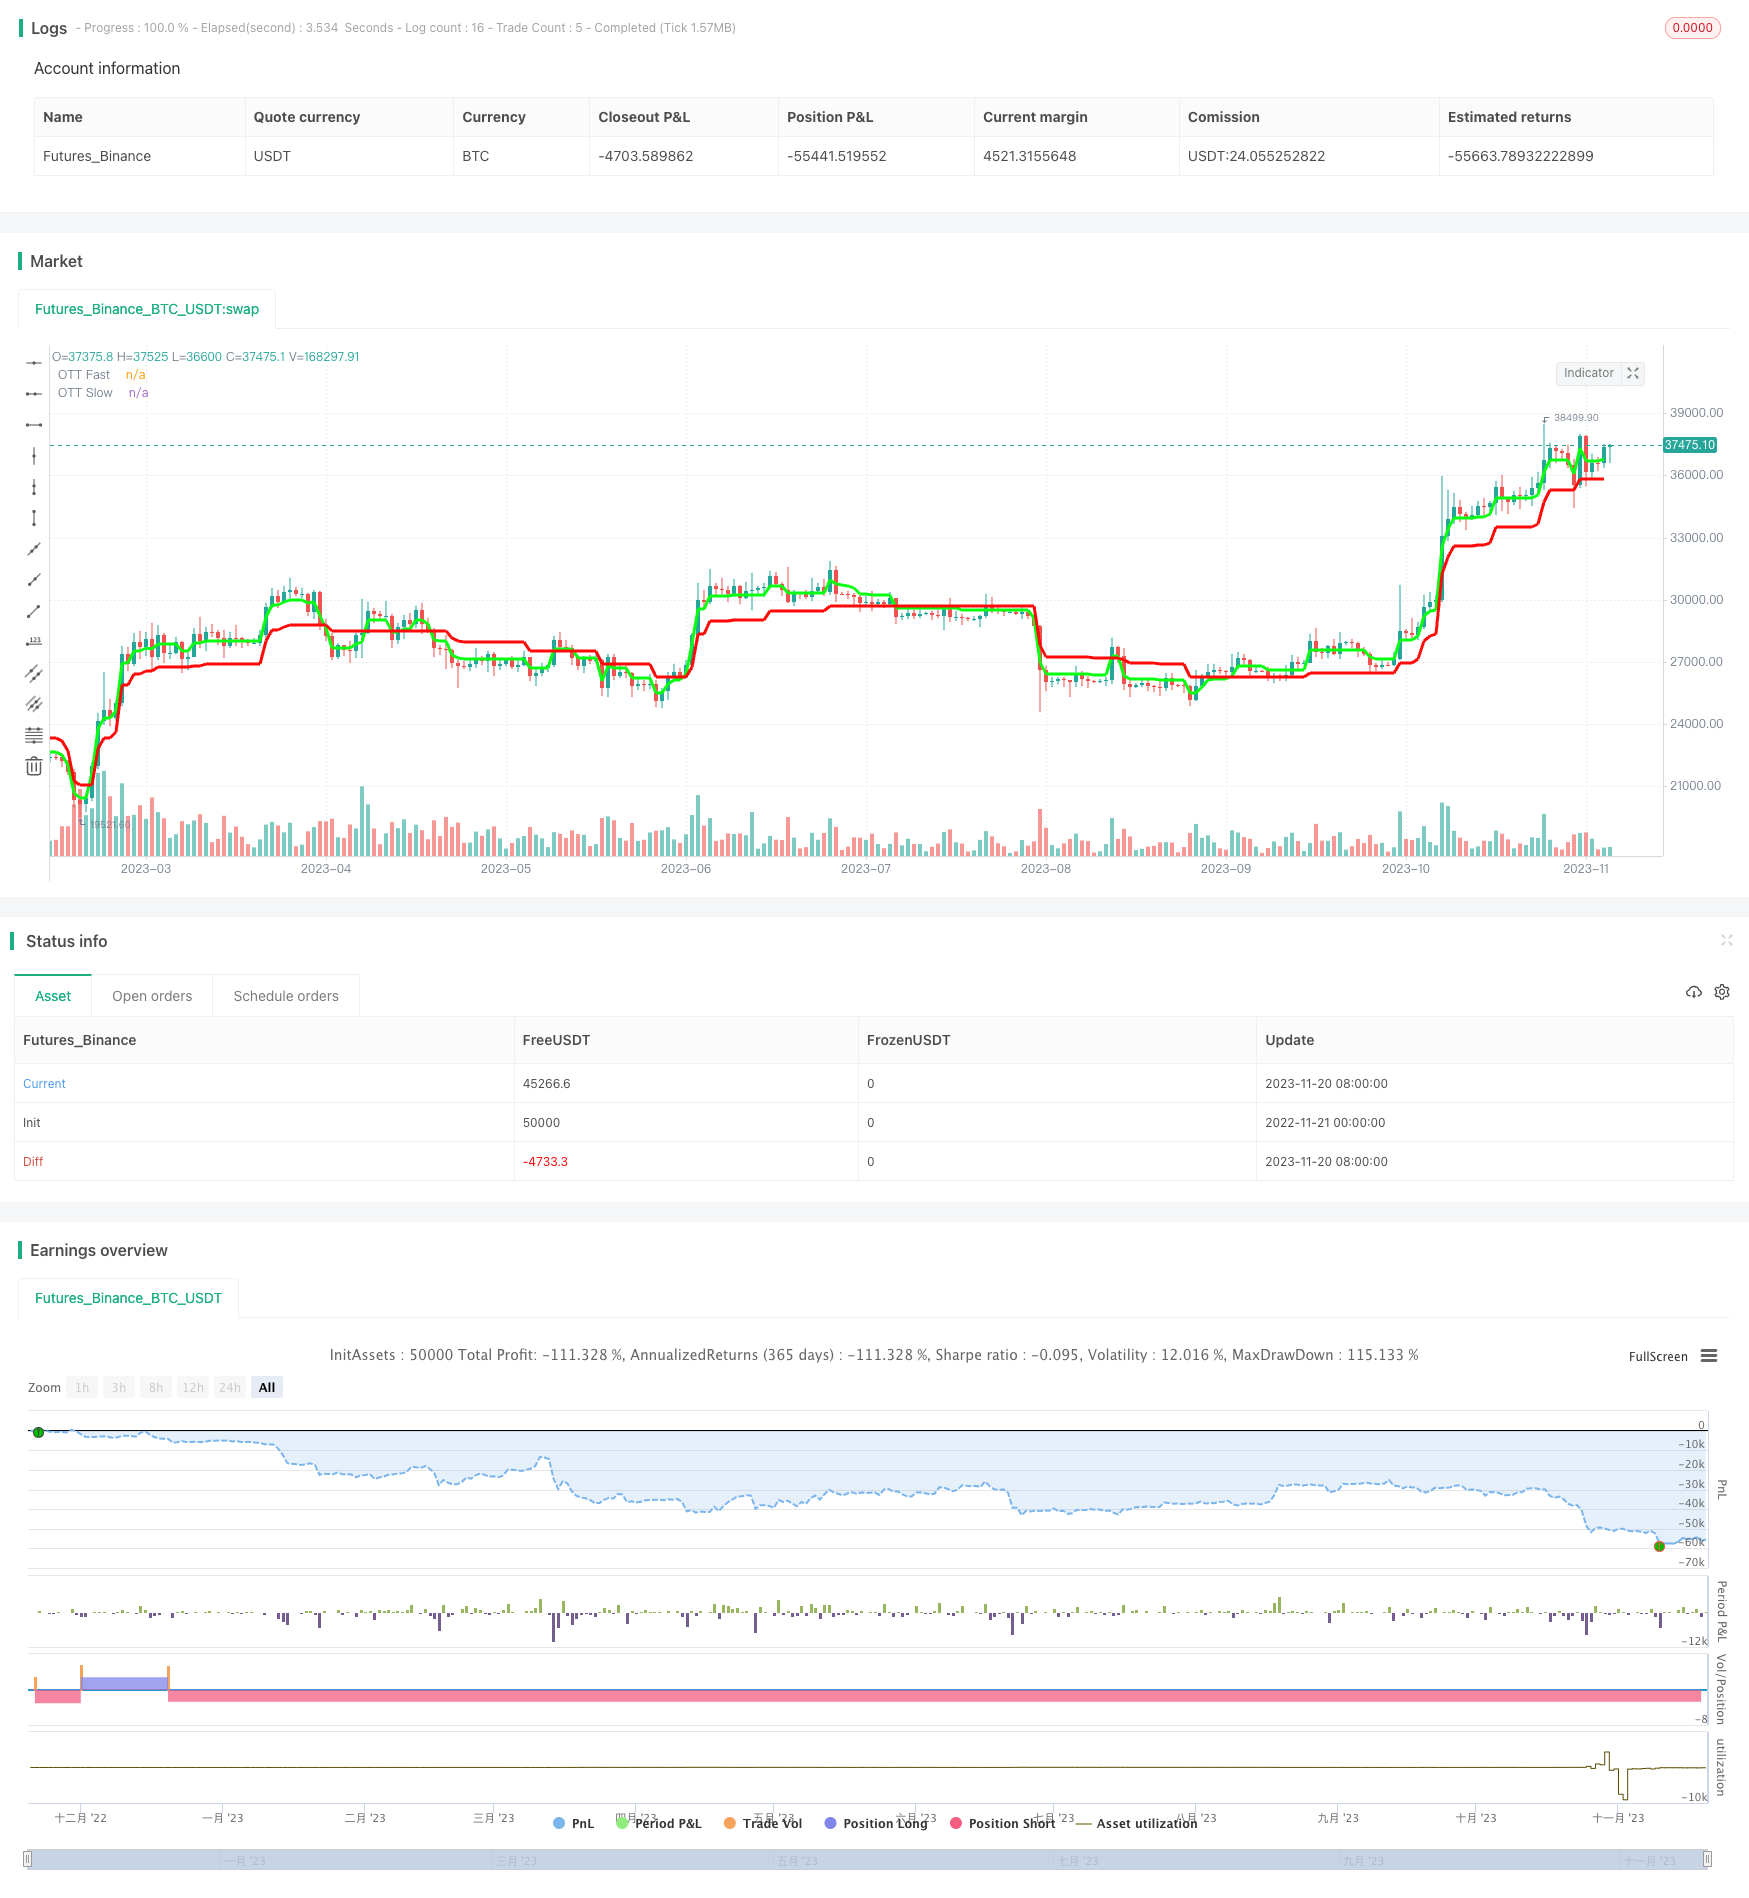
Overview
This strategy combines stochastic oscillator and OTT indicators to generate trading signals. It will trigger orders when fast and slow OTT lines cross. To filter fake signals, stochastic oscillator is used for validation.
Strategy Logic
- Calculate fast and slow OTT lines based on moving averages and stop loss percentage.
- Compute stochastic oscillator based on high, low and close prices.
- Judge long or short direction when fast and slow OTT lines cross. Check stochastic for verification.
- Enter orders according to crossover and directions.
Advantage Analysis
- OTT itself has good reversal effect and is sensitive to turning points.
- Stochastic filters fake signals and avoids getting trapped in consolidation.
- Customizable average types for flexibility facing different markets.
- Profit taking and stop loss for risk control.
Risk Analysis
- Improper parameter tuning might lead to overtrading or bias.
- OTT may generate wrong signals in trending markets.
- Overall market cycle should also be considered.
Optimization Directions
- Optimize parameter combination for best performance.
- Judge effective periods combining trend indicators.
- Introduce money management module.
Summary
This strategy integrates OTT's reversal and stochastic's filtering ability to control risk effectively. It works well for reversal or ranging markets. But market cycle and tunings require attention. Further improvements can be made in parameter optimization and money management.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | OTT source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2_close | 0 | Stoch OTT source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_float_1 | 3 | OTT Fast Percent(%): |
| v_input_float_2 | 10 | OTT Slow Percent(%): |
| v_input_int_1 | true | OTT Fast Length: |
| v_input_int_2 | true | OTT Slow Length: |
| v_input_int_3 | 500 | %K Length |
| v_input_int_4 | 200 | %K Smoothing |
| v_input_int_5 | 2 | Stoch OTT Period |
| v_input_float_3 | 0.5 | Stoch OTT Percent |
| v_input_string_1 | 0 | Moving Average Type: SMA | EMA | WMA | TMA | VAR | WWMA | ZLEMA | TSF |
| v_input_float_4 | false | Take Profit: |
| v_input_float_5 | false | Stop Loss: |
| v_input_bool_1 | false | evaluate Stoch OTT |
| v_input_bool_2 | true | Long Entry |
| v_input_bool_3 | true | Short Entry |
| v_input_int_6 | true | From Day |
| v_input_int_7 | true | From Month |
| v_input_int_8 | 2021 | From Year |
| v_input_int_9 | 30 | To Day |
| v_input_int_10 | 12 | To Month |
| v_input_int_11 | 2022 | To Year |
Source Pine Script
/*backtest
start: 2022-11-21 00:00:00
end: 2023-11-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © BigCoinHunter

//@version=5
strategy(title='OTT-Stoch-TP/SL', overlay=true,
     pyramiding=0, default_qty_type=strategy.percent_of_equity,
     default_qty_value=100, initial_capital=1000,
     currency=currency.USD, commission_value=0.05,
     commission_type=strategy.commission.percent,
     process_orders_on_close=true)

//-------------- fetch user inputs ------------------
src = input(defval=close, title='OTT source')
src1 = input(defval=close, title="Stoch OTT source")

ottFastPercent = input.float(title='OTT Fast Percent(%):', defval=3.0, minval=0.1, maxval=30.0, step=0.1)
ottSlowPercent = input.float(title='OTT Slow Percent(%):', defval=10.0, minval=0.1, maxval=30.0, step=0.1)

ottFastLength = input.int(title="OTT Fast Length:", defval=1, minval=1)
ottSlowLength = input.int(title="OTT Slow Length:", defval=1, minval=1)

periodK = input.int(defval=500, title="%K Length", minval=1, step=10)
smoothK = input.int(defval=200, title="%K Smoothing", minval=1, step=10)
stochLength=input.int(defval=2, title="Stoch OTT Period", minval=1)
stochPercent=input.float(defval=0.5, title="Stoch OTT Percent", step=0.1, minval=0)

mav = input.string(title="Moving Average Type", defval="SMA", options=["SMA", "EMA", "WMA", "TMA", "VAR", "WWMA", "ZLEMA", "TSF"])

tp = input.float(title="Take Profit:", defval=0.0, minval=0.0, maxval=100.0, step=0.1) * 0.01
sl = input.float(title="Stop Loss:  ", defval=0.0, minval=0.0, maxval=100.0, step=0.1) * 0.01

//showsupport = input.bool(title="Show Support Line?", defval=true)
stoch = input.bool(title="evaluate Stoch OTT", defval=false)

longEntry = input.bool(defval=true, title= 'Long Entry', inline="11")
shortEntry = input.bool(defval=true, title='Short Entry', inline="11")


//---------- backtest range setup ------------
fromDay   = input.int(defval = 1, title = "From Day", minval = 1, maxval = 31)
fromMonth = input.int(defval = 1, title = "From Month", minval = 1, maxval = 12)
fromYear  = input.int(defval = 2021, title = "From Year", minval = 2010)
toDay     = input.int(defval = 30, title = "To Day", minval = 1, maxval = 31)
toMonth   = input.int(defval = 12, title = "To Month", minval = 1, maxval = 12)
toYear    = input.int(defval = 2022, title = "To Year", minval = 2010)


//------------ time interval setup -----------
start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)  // backtest start window
finish    = timestamp(toYear, toMonth, toDay, 23, 59)        // backtest finish window
window()  => time >= start and time <= finish ? true : false // create function "within window of time"


//-------- calculate the OTT lines ----------
Var_Func(src,length)=>
    valpha=2/(length+1)
    vud1=src>src[1] ? src-src[1] : 0
    vdd1=src<src[1] ? src[1]-src : 0
    vUD=math.sum(vud1,9)
    vDD=math.sum(vdd1,9)
    vCMO=nz((vUD-vDD)/(vUD+vDD))
    VAR=0.0
    VAR:=nz(valpha*math.abs(vCMO)*src)+(1-valpha*math.abs(vCMO))*nz(VAR[1])

//VAR=Var_Func(src,length)

Wwma_Func(src,length)=>
    wwalpha = 1/ length
    WWMA = 0.0
    WWMA := wwalpha*src + (1-wwalpha)*nz(WWMA[1])

//WWMA=Wwma_Func(src,length)

Zlema_Func(src,length)=>
    zxLag = length/2==math.round(length/2) ? length/2 : (length - 1) / 2
    zxEMAData = (src + (src - src[zxLag]))
    ZLEMA = ta.ema(zxEMAData, length)

//ZLEMA=Zlema_Func(src,length)

Tsf_Func(src,length)=>
    lrc = ta.linreg(src, length, 0)
    lrc1 = ta.linreg(src,length,1)
    lrs = (lrc-lrc1)
    TSF = ta.linreg(src, length, 0)+lrs

//TSF=Tsf_Func(src,length)

getMA(src, length) =>
    ma = 0.0
    if mav == "SMA"
        ma := ta.sma(src, length)
        ma

    if mav == "EMA"
        ma := ta.ema(src, length)
        ma

    if mav == "WMA"
        ma := ta.wma(src, length)
        ma

    if mav == "TMA"
        ma := ta.sma(ta.sma(src, math.ceil(length / 2)), math.floor(length / 2) + 1)
        ma

    if mav == "VAR"
        ma := Var_Func(src,length)
        ma

    if mav == "WWMA"
        ma := Wwma_Func(src,length)
        ma

    if mav == "ZLEMA"
        ma := Zlema_Func(src,length)
        ma

    if mav == "TSF"
        ma := Tsf_Func(src,length)
        ma
    ma

//-------- OTT line calculation --------
MAvg1=getMA(src, ottFastLength)
fark1=MAvg1*ottFastPercent*0.01
longStop1 = MAvg1 - fark1
longStopPrev1 = nz(longStop1[1], longStop1)
longStop1 := MAvg1 > longStopPrev1 ? math.max(longStop1, longStopPrev1) : longStop1
shortStop1 =  MAvg1 + fark1
shortStopPrev1 = nz(shortStop1[1], shortStop1)
shortStop1 := MAvg1 < shortStopPrev1 ? math.min(shortStop1, shortStopPrev1) : shortStop1
dir1 = 1
dir1 := nz(dir1[1], dir1)
dir1 := dir1 == -1 and MAvg1 > shortStopPrev1 ? 1 : dir1 == 1 and MAvg1 < longStopPrev1 ? -1 : dir1
MT1 = dir1==1 ? longStop1: shortStop1

OTTFast=MAvg1>MT1 ? MT1*(200+ottFastPercent)/200 : MT1*(200-ottFastPercent)/200

MAvg2=getMA(src, ottSlowLength)
fark2=MAvg2*ottSlowPercent*0.01
longStop2 = MAvg2 - fark2
longStopPrev2 = nz(longStop2[1], longStop2)
longStop2 := MAvg2 > longStopPrev2 ? math.max(longStop2, longStopPrev2) : longStop2
shortStop2 =  MAvg2 + fark2
shortStopPrev2 = nz(shortStop2[1], shortStop2)
shortStop2 := MAvg2 < shortStopPrev2 ? math.min(shortStop2, shortStopPrev2) : shortStop2
dir2 = 1
dir2 := nz(dir2[1], dir2)
dir2 := dir2 == -1 and MAvg2 > shortStopPrev2 ? 1 : dir2 == 1 and MAvg2 < longStopPrev2 ? -1 : dir2
MT2 = dir2==1 ? longStop2: shortStop2

OTTSlow=MAvg2>MT2 ? MT2*(200+ottSlowPercent)/200 : MT2*(200-ottSlowPercent)/200

//-------- Stoch OTT calculation ----------

Var_Func1(src1,length)=>
    valpha1=2/(length+1)
    vud11=src1>src1[1] ? src1-src1[1] : 0
    vdd11=src1<src1[1] ? src1[1]-src1 : 0
    vUD1=math.sum(vud11,9)
    vDD1=math.sum(vdd11,9)
    vCMO1=nz((vUD1-vDD1)/(vUD1+vDD1))
    VAR1=0.0
    VAR1:=nz(valpha1*math.abs(vCMO1)*src1)+(1-valpha1*math.abs(vCMO1))*nz(VAR1[1])
VAR1=Var_Func1(src1,stochLength)

k = Var_Func1(ta.stoch(close, high, low, periodK), smoothK)
k1=k+1000

VAR2=Var_Func(k1,stochLength)

MAvg3=Var_Func(k1, stochLength)
fark3=MAvg3*stochPercent*0.01
longStop3 = MAvg3 - fark3
longStopPrev3 = nz(longStop3[1], longStop3)
longStop3 := MAvg3 > longStopPrev3 ? math.max(longStop3, longStopPrev3) : longStop3
shortStop3 =  MAvg3 + fark3
shortStopPrev3 = nz(shortStop3[1], shortStop3)
shortStop3 := MAvg3 < shortStopPrev3 ? math.min(shortStop3, shortStopPrev3) : shortStop3
dir3 = 1
dir3 := nz(dir3[1], dir3)
dir3 := dir3 == -1 and MAvg3 > shortStopPrev3 ? 1 : dir3 == 1 and MAvg3 < longStopPrev3 ? -1 : dir3
MT3 = dir3==1 ? longStop3: shortStop3
OTTStoch=MAvg3>MT3 ? MT3*(200+stochPercent)/200 : MT3*(200-stochPercent)/200


//------- define the global variables ------
var bool long = true
var bool stoppedOutLong = false
var bool stoppedOutShort = false

//-------- determine the market direction --------
if OTTFast > OTTSlow
    long := true
else if OTTFast < OTTSlow
    long := false


//--------- calculate the input/output points -----------
longProfitPrice  = strategy.position_avg_price * (1 + tp)     // tp -> take profit percentage
longStopPrice = strategy.position_avg_price * (1 - sl)        // sl -> stop loss percentage

shortProfitPrice  = strategy.position_avg_price * (1 - tp)
shortStopPrice = strategy.position_avg_price * (1 + sl)

//------------------- determine buy and sell points ---------------------
buySignall = false
sellSignall = false

if stoch == false
    buySignall := window() and long  and (not stoppedOutLong)
    sellSignall := window() and (not long)  and (not stoppedOutShort)
else
    buySignall := window() and long  and (not stoppedOutLong) and ( k1 > OTTStoch )
    sellSignall := window() and (not long)  and (not stoppedOutShort) and ( k1 < OTTStoch )

//---------- execute the strategy -----------------
if(longEntry and shortEntry)
    if long
        strategy.entry("LONG", strategy.long, when = buySignall, comment = "ENTER LONG")
        stoppedOutLong := true
        stoppedOutShort := false
    else
        strategy.entry("SHORT", strategy.short, when = sellSignall, comment = "ENTER SHORT")
        stoppedOutLong  := false
        stoppedOutShort := true

else if(longEntry)
    strategy.entry("LONG", strategy.long,  when = buySignall)
    strategy.close("LONG", when = sellSignall)
    if long
        stoppedOutLong := true
    else
        stoppedOutLong  := false

else if(shortEntry)
    strategy.entry("SHORT", strategy.short, when = sellSignall)
    strategy.close("SHORT", when = buySignall)
    if not long
        stoppedOutShort := true
    else
        stoppedOutShort := false


//----------------- take profit and stop loss -----------------
if(tp>0.0 and sl>0.0)
    if ( strategy.position_size > 0 )
        strategy.exit(id="LONG", limit=longProfitPrice, stop=longStopPrice, comment="Long TP/SL Trigger")

    else if ( strategy.position_size < 0 )
        strategy.exit(id="SHORT", limit=shortProfitPrice, stop=shortStopPrice, comment="Short TP/SL Trigger")

else if(tp>0.0)
    if ( strategy.position_size > 0 )
        strategy.exit(id="LONG", limit=longProfitPrice, comment="Long TP Trigger")

    else if ( strategy.position_size < 0 )
        strategy.exit(id="SHORT", limit=shortProfitPrice, comment="Short TP Trigger")

else if(sl>0.0)
    if ( strategy.position_size > 0 )
        strategy.exit(id="LONG",  stop=longStopPrice, comment="Long SL Trigger")

    else if ( strategy.position_size < 0 )
        strategy.exit(id="SHORT",  stop=shortStopPrice, comment="Short SL Trigger")


//------------- plot charts ---------------------
lineColor1 = long ? color.green : color.red
lineColor2 = long ? color.aqua : color.fuchsia

light_green=#08ff12
light_red=#fe0808

plot(nz(OTTFast), color=light_green, linewidth=3, title="OTT Fast")
plot(nz(OTTSlow), color=light_red, linewidth=3, title="OTT Slow")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Stochastic-OTT-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Multi Strategy Technical Analysis Trading SystemPine Script · Mean reversion · 1d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- Stochastic Moving Average StrategyPine Script · Mean reversion · 1h
- 3EMA with Stochastic RSI StrategyPine Script · Mean reversion · 1h