Strategy vault / Trend following
Supertrend and Moving Average Crossover Strategy
The strategy is named "Supertrend and Moving Average Crossover Strategy". It combines the Supertrend indicator and moving averages, going long when the supertrend indicates an uptrend and 10-day EMA is above 20-day…
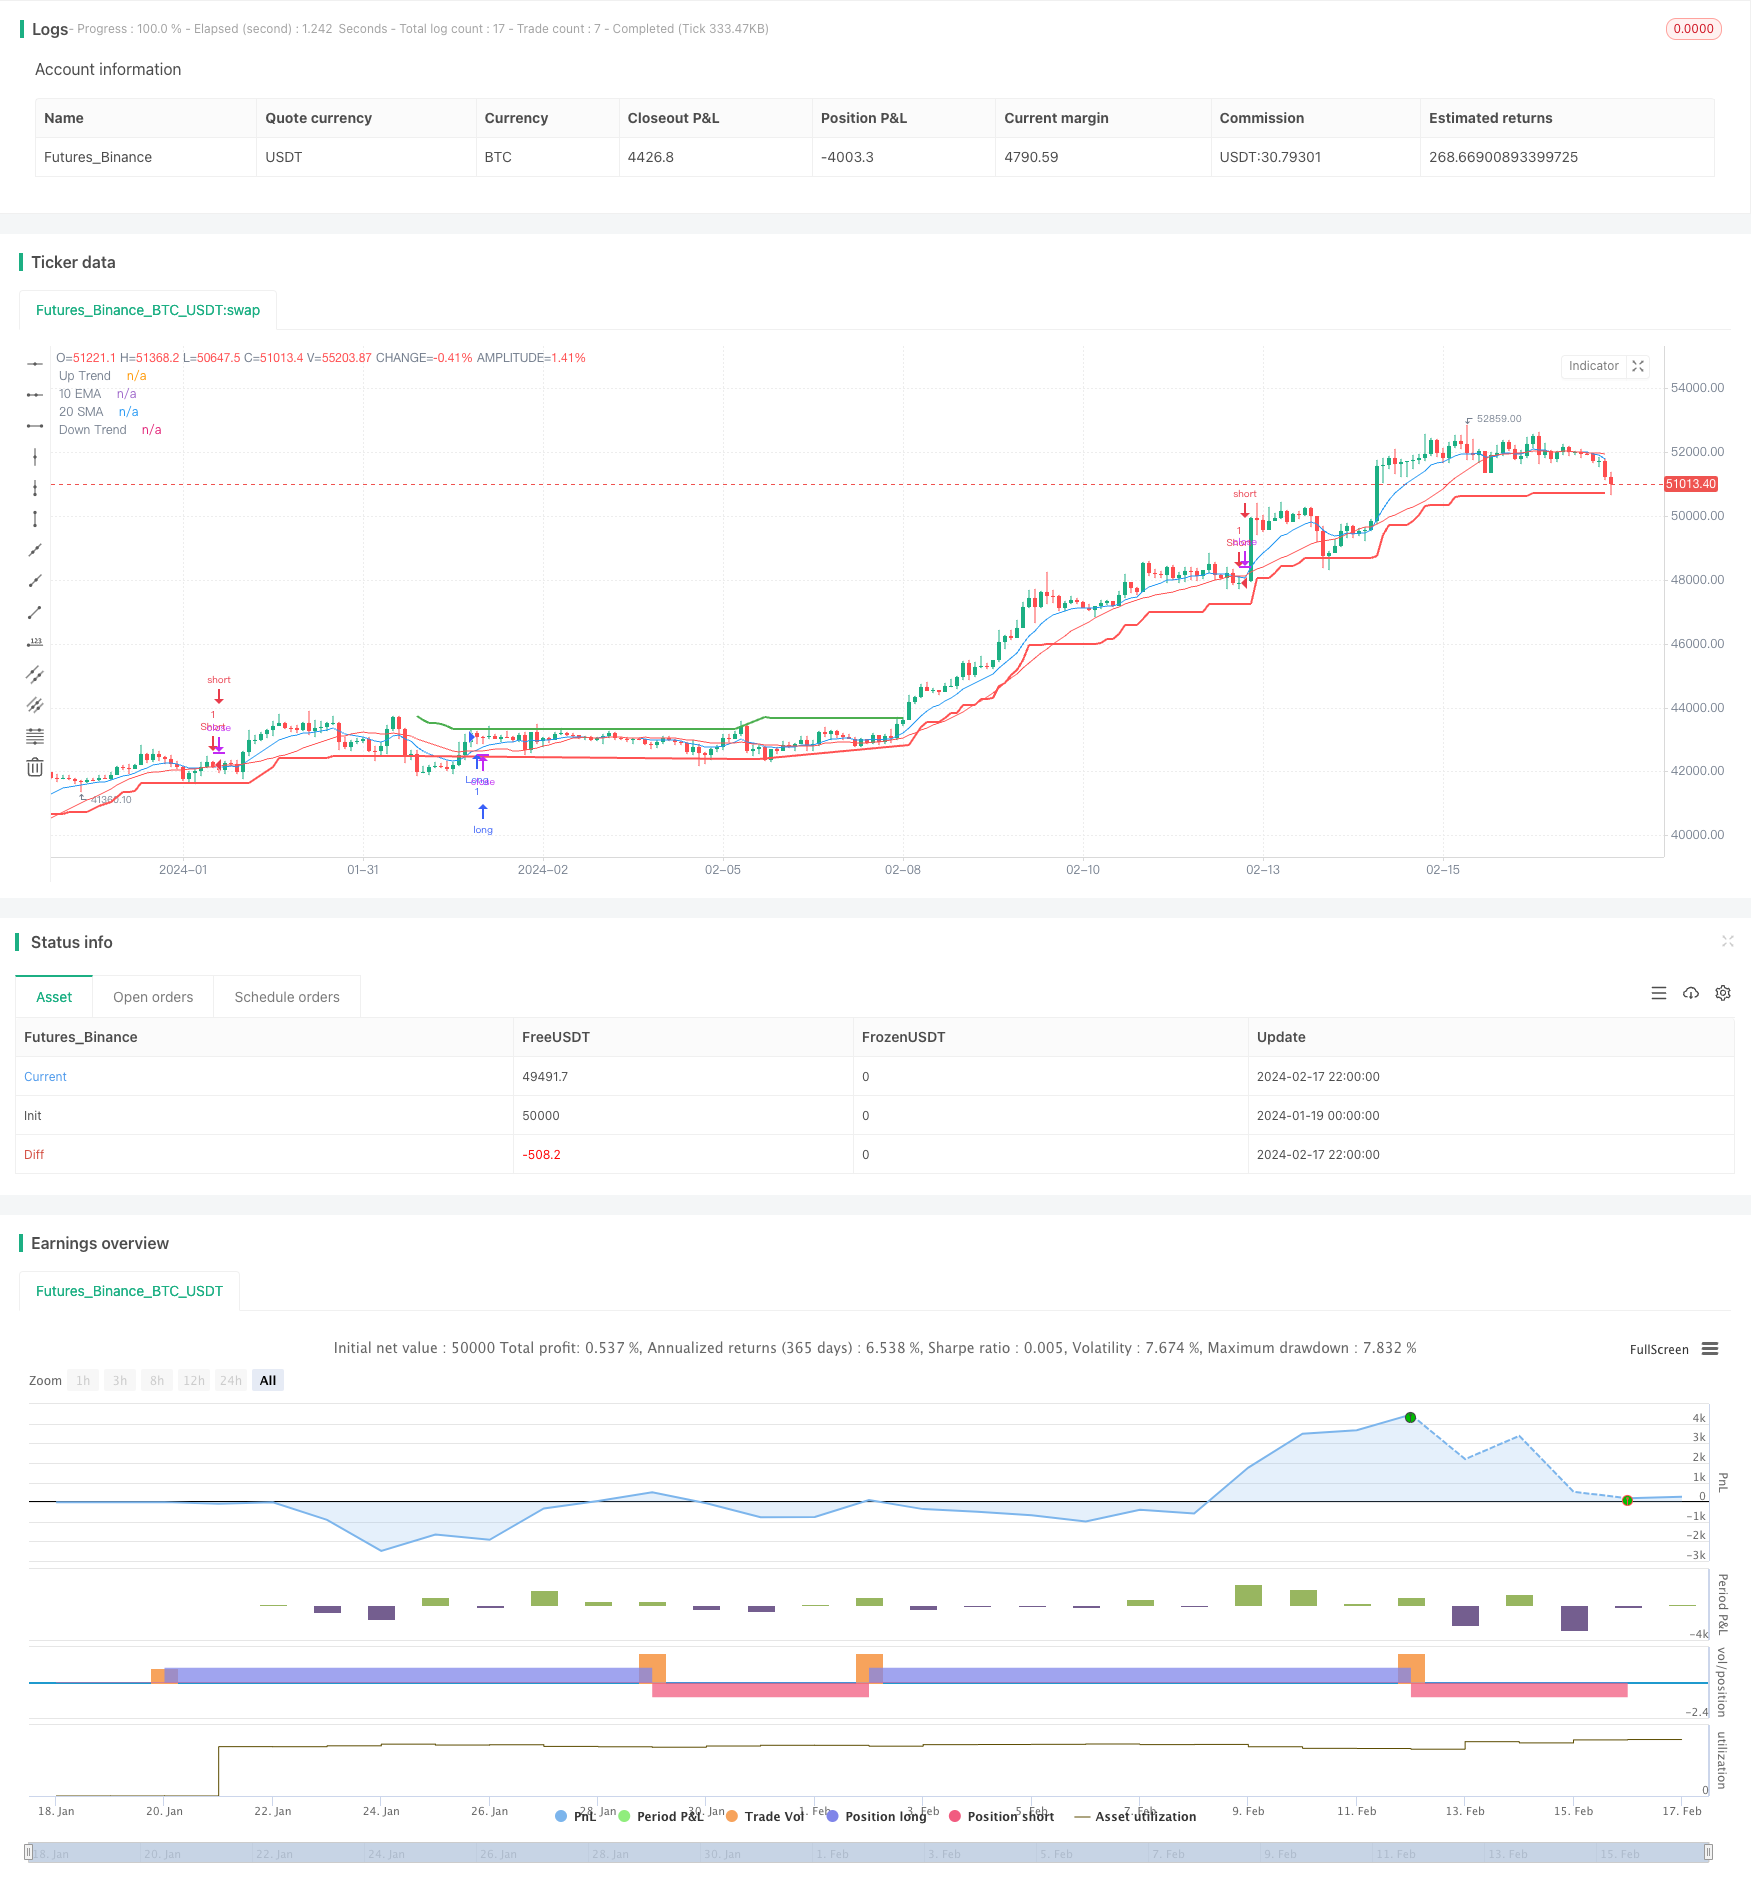
Overview
The strategy is named "Supertrend and Moving Average Crossover Strategy". It combines the Supertrend indicator and moving averages, going long when the supertrend indicates an uptrend and 10-day EMA is above 20-day SMA, and going short when the supertrend indicates a downtrend and 10-day EMA is below 20-day SMA. It's a typical trend following strategy.
Strategy Logic
The strategy uses the Supertrend indicator to determine the market trend direction. Supertrend is calculated based on Average True Range and a Factor. When the price is above Supertrend line, it's an uptrend; when the price is below Supertrend line, it's a downtrend. In this strategy, the Factor is set to 3.0 and ATR length is 10.
In addition, the strategy uses 10-day EMA and 20-day SMA to construct moving averages. EMA (Exponential Moving Average) assigns higher weight to recent prices, while SMA (Simple Moving Average) considers all data with equal weight. When the shorter-term EMA is above the longer-term SMA, it's considered a buy signal.
In summary, the trade signal generation logic is:
Long entry: Supertrend > 0 (uptrend) AND 10-day EMA > 20-day SMA Short entry: Supertrend < 0 (downtrend) AND 10-day EMA < 20-day SMA
So it determines the trend direction with Supertrend and uses the moving average crossover for additional confirmation, to construct this trend following strategy.
Advantage Analysis
The biggest advantage of this strategy is combining Supertrend and moving averages, which improves both reliability and sensitivity. The main advantages are:
- Supertrend clearly identifies the main trend, reducing false signals
- EMA+SMA crossover improves sensitivity to trend changes
- Judging multiple factors improves reliability
- Simple and clear indicators, easy to understand and optimize
- High flexibility to adjust parameters of Supertrend and MAs
Risk Analysis
There are some risks in this strategy:
- Improper Supertrend parameters may miss turn points
- Improper MA parameters may generate false signals
- Improper backtest period selection may overestimate performance
- No consideration of trading costs
We can test different ATR and Factor values for Supertrend, and different length values for MAs. Also the backtest period should cover different market environments. Trading costs should be added in live trading.
Optimization Directions
There is large room for optimization:
- Adjust ATR length and Factor in Supertrend
- Adjust length of EMA and SMA
- Add other indicators like RSI, MACD for signal filtering
- Buy when Supertrend turns up and EMA crosses over SMA after some duration
- Add stop loss strategy
This can further improve performance and stability. Also stop loss configuration is important for risk control.
Conclusion
The strategy combines Supertrend for trend direction and EMA+SMA crossovers to generate signals, a typical trend following system. It has high reliability and much flexibility for optimization, worth verifying in live trading. But we should also control risks and prevent excessive optimization.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 10 | ATR Length |
| v_input_float_1 | 3 | Factor |
| v_input_1 | 10 | Length of EMA |
| v_input_2 | 20 | Length of SMA |
Source Pine Script
/*backtest
start: 2024-01-19 00:00:00
end: 2024-02-18 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Supertrend and Moving Averages Strategy", overlay=true)

// Supertrend parameters
atrLength = input.int(10, title="ATR Length", minval=1)
factor = input.float(3.0, title="Factor", minval=0.01, step=0.01)
[supertrend, direction] = ta.supertrend(factor, atrLength)

// Moving Averages parameters
length_ema = input(10, title="Length of EMA")
length_sma = input(20, title="Length of SMA")

// Calculate EMAs and SMAs
ema_10 = ta.ema(close, length_ema)
sma_20 = ta.sma(close, length_sma)

// Strategy logic
longCondition = ema_10 > sma_20 and direction > 0
shortCondition = ema_10 < sma_20 and direction < 0

strategy.entry("Long", strategy.long, when=longCondition)
strategy.entry("Short", strategy.short, when=shortCondition)

// Plot Supertrend
plot(direction > 0 ? supertrend : na, color=color.green, style=plot.style_line, linewidth=2, title="Up Trend")
plot(direction < 0 ? supertrend : na, color=color.red, style=plot.style_line, linewidth=2, title="Down Trend")

// Plot Moving Averages
plot(ema_10, color=color.blue, title="10 EMA")
plot(sma_20, color=color.red, title="20 SMA")

// Alerts for Supertrend
alertcondition(direction[1] > direction, title='Downtrend to Uptrend', message='The Supertrend value switched from Downtrend to Uptrend ')
alertcondition(direction[1] < direction, title='Uptrend to Downtrend', message='The Supertrend value switched from Uptrend to Downtrend')
alertcondition(direction[1] != direction, title='Trend Change', message='The Supertrend value switched from Uptrend to Downtrend or vice versa')
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Supertrend-and-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Supertrend Advance StrategyPine Script · Trend following · 5m
- Mini Pullback Supertrend StrategyPine Script · Trend following · 1h
- Intelligent Multi Dimensional Adaptive Trend Trading SystemPine Script · Trend following · 1h
- Dual Moving Average Crossover Intraday Futures Trading StrategyPine Script · Trend following · 1h
- SuperTrend Trading Strategy with Multiple FiltersPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h