Strategy vault / Trend following
Supertrend Tracking Strategy
This strategy is named "Supertrend Tracking Strategy". It develops an automated trading system for both long and short positions based on the Supertrend indicator, which can automatically identify the trend direction…
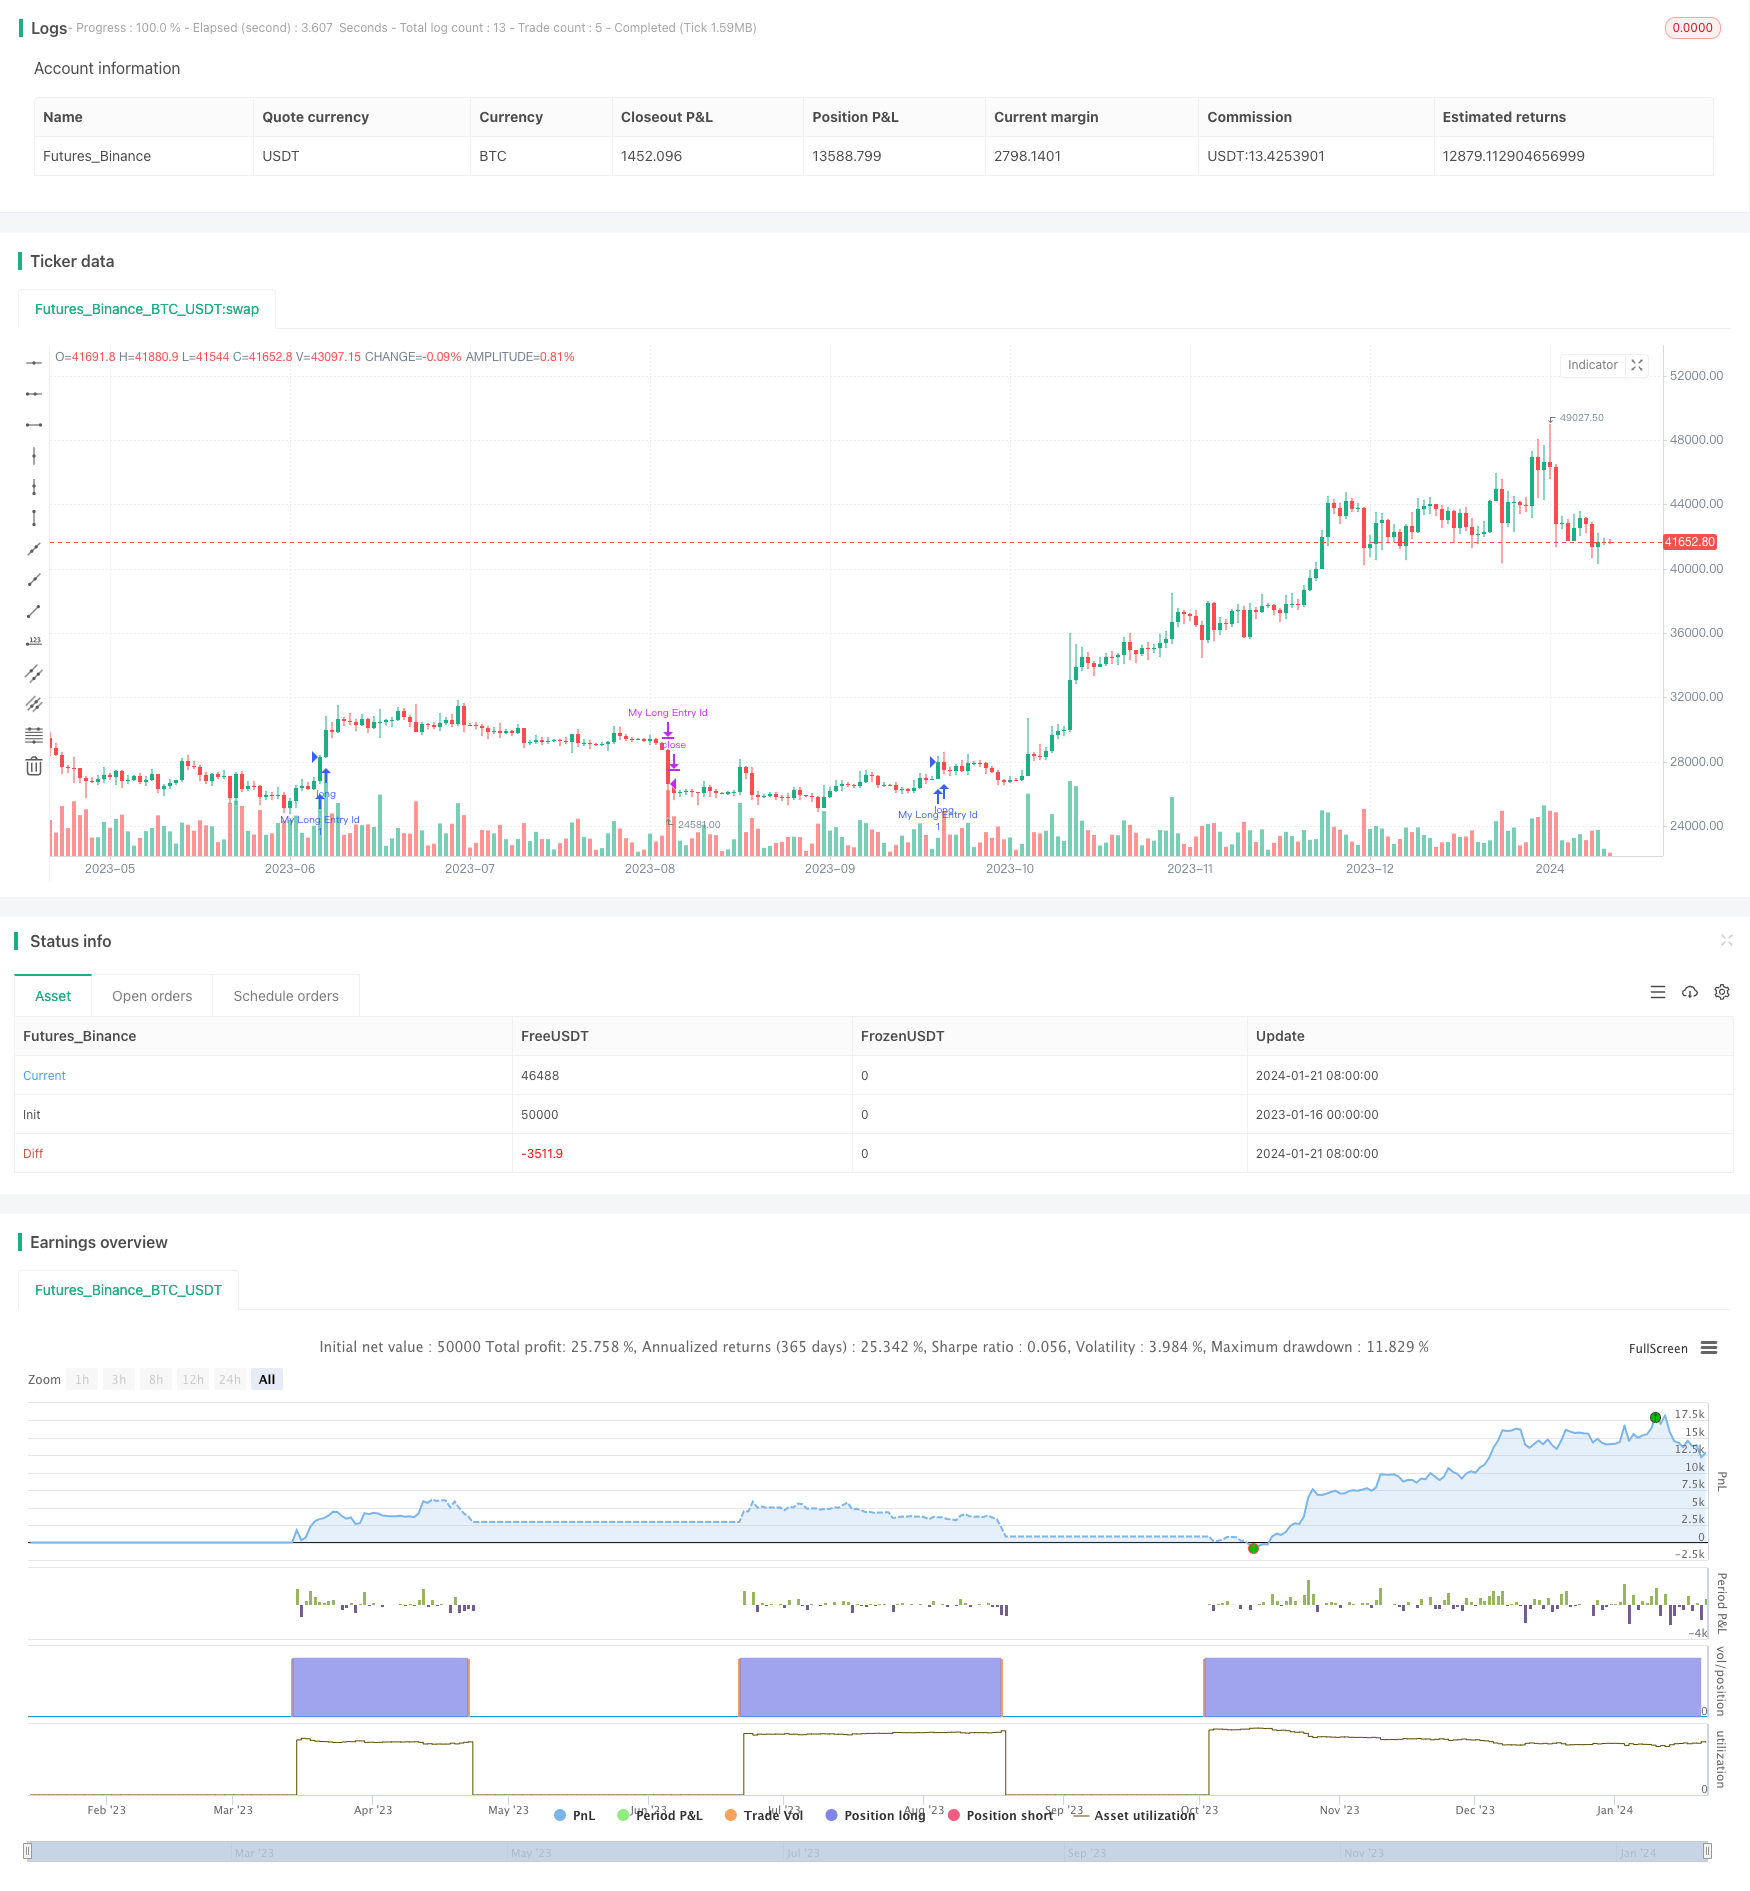
Overview
This strategy is named "Supertrend Tracking Strategy". It develops an automated trading system for both long and short positions based on the Supertrend indicator, which can automatically identify the trend direction and make entries and exits combined with the RSI and ADX indicators.
Principles
The core of this strategy is using the Supertrend indicator to determine the current price trend. The Supertrend combines moving averages and ATR, which is effective in judging the direction of price trends. When the direction of the Supertrend makes a reversal, it signals that the price trend is changing.
Specifically, this strategy first calculates the Supertrend direction, RSI and ADX. When the Supertrend turns down, and the RSI shows that the uptrend is fading, it makes short entry. When the Supertrend turns up again, it closes the short position.
Advantages
The biggest advantage of this strategy is that it can automatically identify price trends and make entries and exits based on the trends, without manual judgment. In addition, using RSI and ADX as filters can effectively avoid false breakouts and improve profitability.
Risks
The biggest risk is that the Supertrend itself is not highly accurate in judging price trends, which may generate incorrect signals. Also, no stop loss is set, so the loss per trade can be significant.
Optimization can be made by adjusting Supertrend parameters and adding trailing stop loss to reduce risks.
Optimization
Several aspects of this strategy can be optimized:
Optimize Supertrend parameters to improve accuracy
Add trailing stop loss to control per trade loss
Add more filters like Bollinger Bands, KDJ to improve profitability
Develop similar long entry and exit rules to make the strategy complete
Conclusion
In conclusion, this is an automated trading strategy that judges trends based on the Supertrend. The advantage is high degree of automatization and auto trend detection. The disadvantage is the low accuracy of Supertrend itself and no stop loss. Parameter tuning, adding filters, and stop loss can enhance profitability and risk control.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | ATR Length |
| v_input_float_1 | 3 | Factor |
| v_input_2 | 7 | ADX Smoothing |
| v_input_3 | 7 | DI Length |
Source Pine Script
/*backtest
start: 2023-01-16 00:00:00
end: 2024-01-22 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Supertrend Strategy", overlay=true)

atrPeriod = input(10, "ATR Length")
factor = input.float(3.0, "Factor", step = 0.01)

[_, direction] = ta.supertrend(factor, atrPeriod)

adxlen = input(7, title="ADX Smoothing")
dilen = input(7, title="DI Length")
dirmov(len) =>
    up = ta.change(high)
    down = -ta.change(low)
    plusDM = na(up) ? na : (up > down and up > 0 ? up : 0)
    minusDM = na(down) ? na : (down > up and down > 0 ? down : 0)
    truerange = ta.rma(ta.tr, len)
    plus = fixnan(100 * ta.rma(plusDM, len) / truerange)
    minus = fixnan(100 * ta.rma(minusDM, len) / truerange)
    [plus, minus]

adx(dilen, adxlen) =>
    [plus, minus] = dirmov(dilen)
    sum = plus + minus
    adx = 100 * ta.rma(math.abs(plus - minus) / (sum == 0 ? 1 : sum), adxlen)
    adx

sig = adx(dilen, adxlen)

if ta.change(direction) < 0 and ta.rsi(close, 21) < 66 and ta.rsi(close, 3) > 80 and ta.rsi(close, 28) > 49 and sig > 20
    strategy.entry("My Long Entry Id", strategy.long)

if ta.change(direction) > 0
    strategy.close("My Long Entry Id")

//plot(strategy.equity, title="equity", color=color.red, linewidth=2, style=plot.style_areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Supertrend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual directional Trailing Stop Moving Average Trend StrategyPine Script · Trend following · 1m
- Solid Trend Following StrategyPine Script · Trend following · 1h
- Adaptive Multi Indicator Strategy Combining Trend Following and Range TradingPine Script · Trend following · 1h
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- Advanced Quantitative Trading Strategy Multi Dimensional Super Trend ATR Dynamic Tracking SystemPine Script · Trend following · 1h
- Dual Timeframe Supertrend with RSI Optimization SystemPine Script · Trend following · 1h