Strategy vault / Trend following
T3 CCI Trend Tracking Strategy
This is a quantitative strategy that utilizes the T3 smoothed moving average line and CCI indicator to track trends. The strategy identifies trends by calculating the T3-CCI indicator and enters the market after…
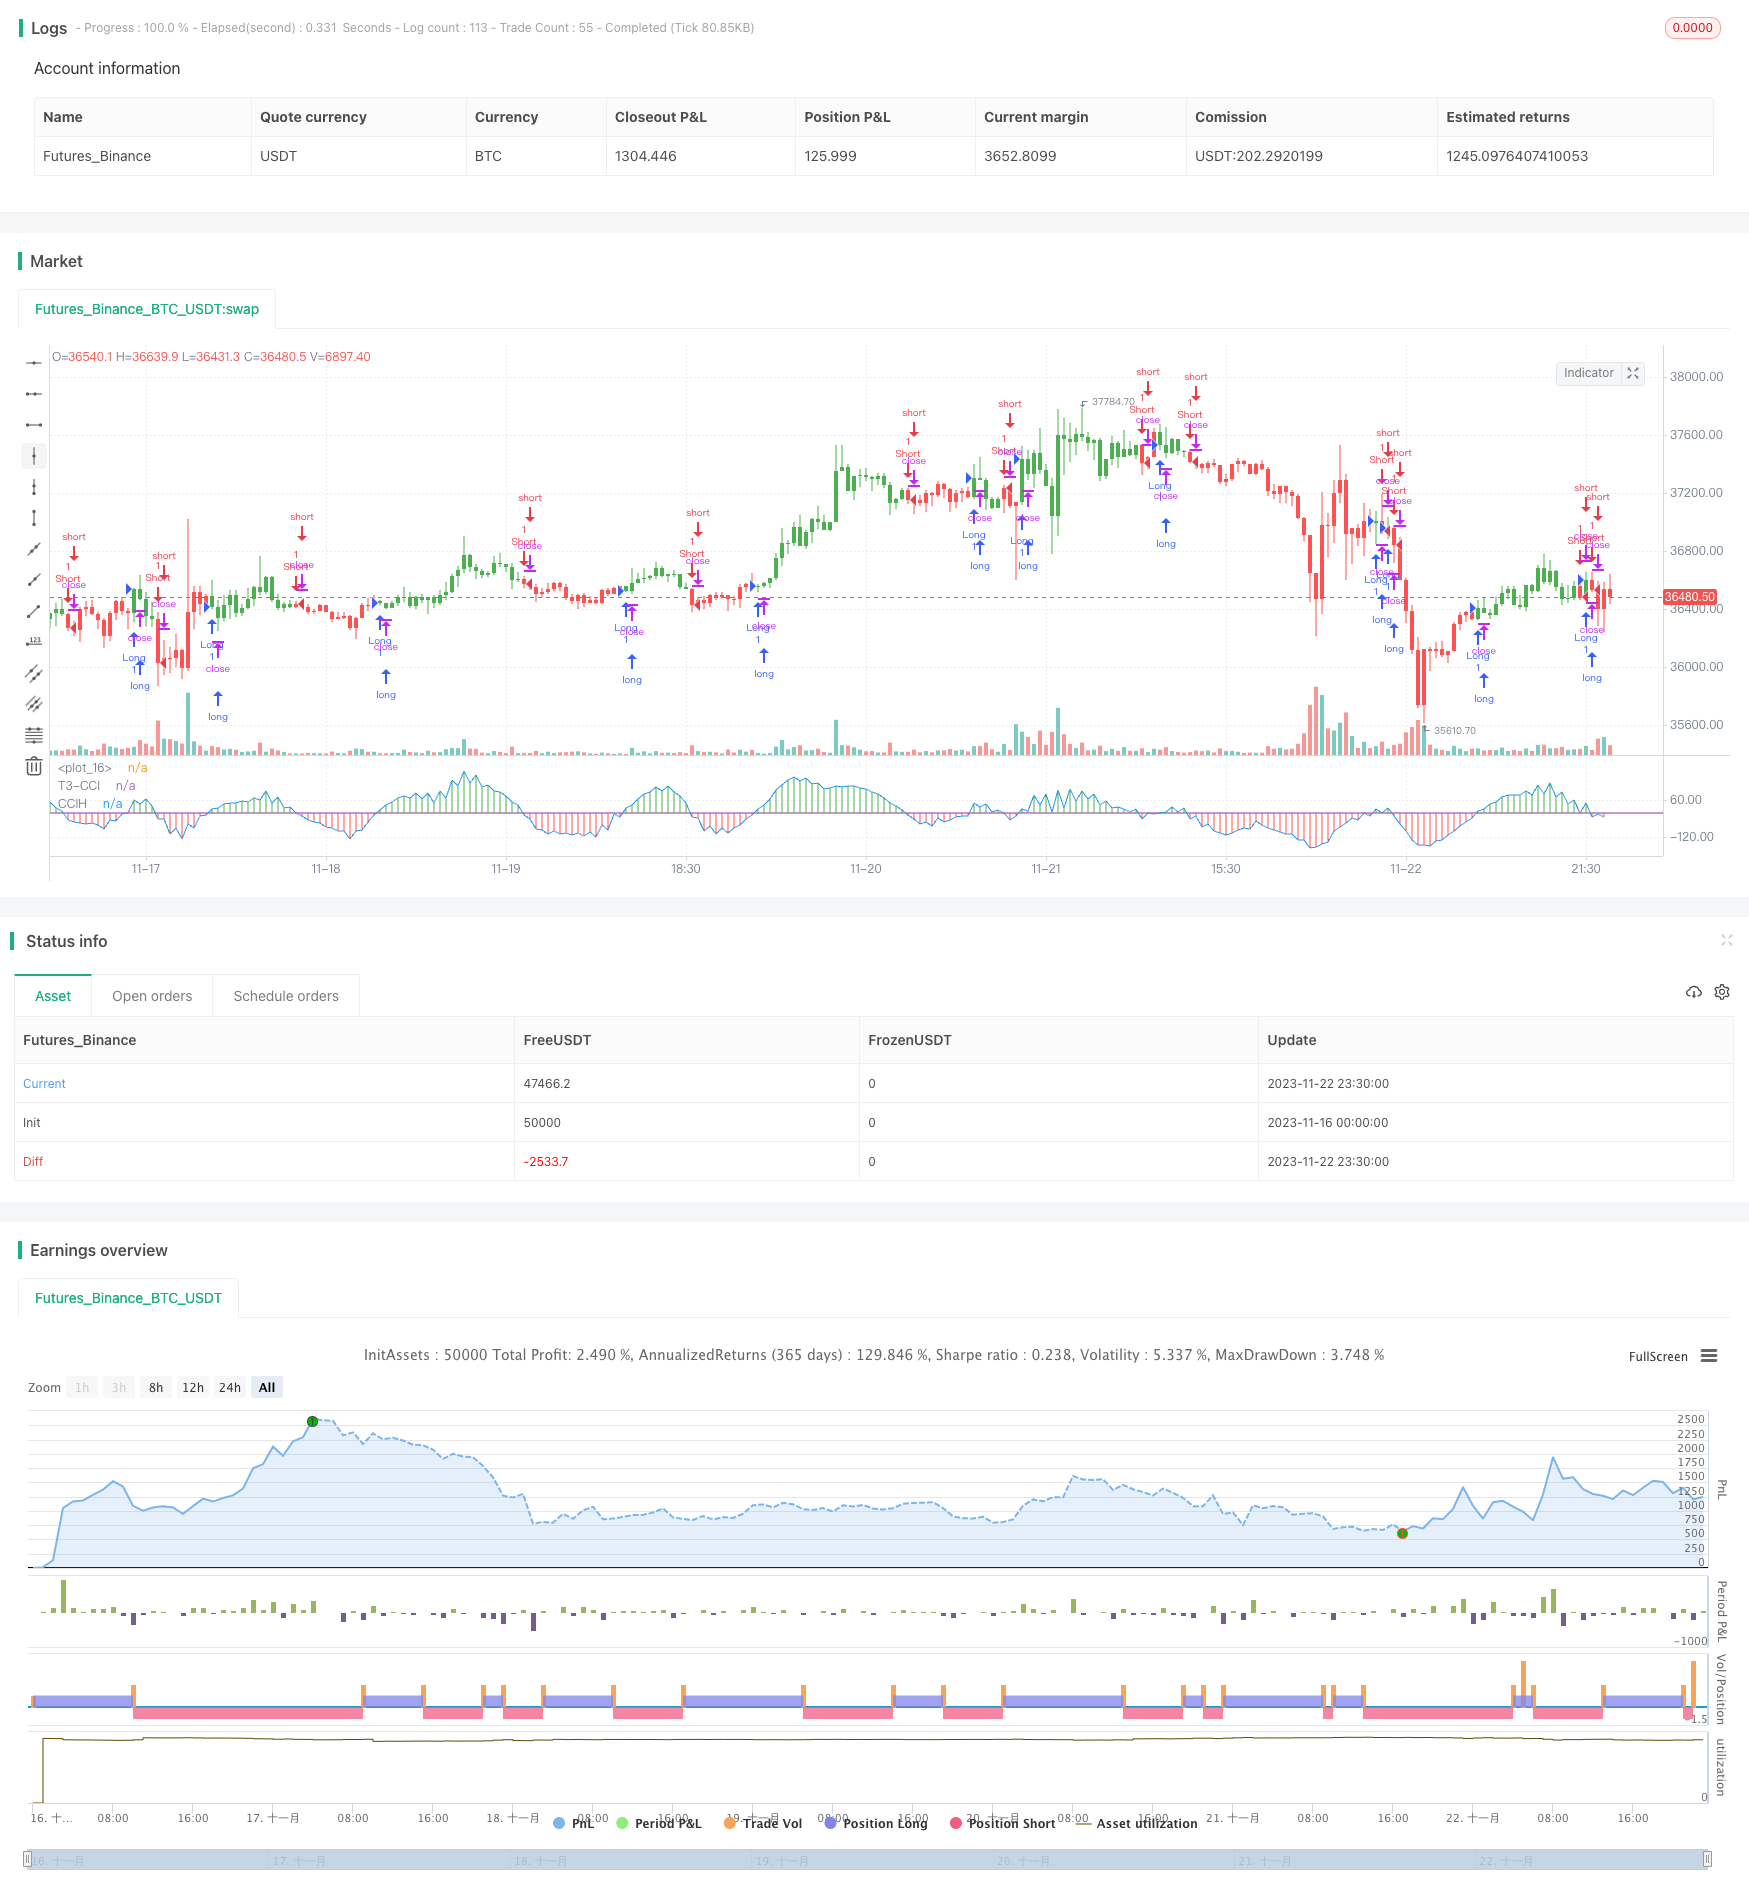
Overview
This is a quantitative strategy that utilizes the T3 smoothed moving average line and CCI indicator to track trends. The strategy identifies trends by calculating the T3-CCI indicator and enters the market after obtaining double confirmation signals to follow trends.
Strategy Principle
The strategy first calculates the T3 smoothed moving average line and CCI indicator. It then converts the CCI indicator into the T3-CCI indicator through a series of filtering calculations. It generates a buy signal when the T3-CCI indicator crosses above the 0 axis and a sell signal when crossing below the 0 axis. To filter out false signals, the strategy requires the T3-CCI indicator to maintain the same signal for two consecutive periods before placing an order.
Specifically, the strategy takes the following steps:
- Calculate the CCI indicator and T3 indicator
- Convert the CCI indicator into the T3-CCI indicator through a series of digital filters
- Judge the long/short state of the T3-CCI indicator
- Wait for persistent signals over two bars as entry signals
Advantage Analysis
The strategy has the following advantages:
- Effectively smooths the CCI indicator using the T3 indicator to filter out market noise
- Adopts a double confirmation mechanism to avoid false signals
- Tracks medium-to-long-term trends and avoids short-term pullbacks
Risk Analysis
The strategy also has some risks:
- It is prone to generating false signals in range-bound markets
- The double confirmation mechanism may miss short-term opportunities
- High risk of stop loss in major trend reversals
Countermeasures:
- Adjust CCI and T3 parameters to optimize indicator performance
- Appropriately shorten confirmation periods or run fast/slow parameter combinations simultaneously
- Adopt moving stop loss or timely stop loss to control single transaction loss
Optimization Directions
The strategy can be optimized in the following directions:
- Adjust CCI and T3 parameters to suit different cycles and markets
- Increase trend judgment indicators to improve signal quality
- Automatically adjust stop loss position based on volatility
- Dynamically optimize parameters using machine learning methods
Summary
Overall, this is a reliable medium-to-long-term trend tracking strategy. It controls risks with double confirmation and trend tracking features, and can serve as a basic trend trading strategy. Further performance improvement can be achieved through parameter and rule optimization.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | CCI_Period |
| v_input_2 | 5 | T3_Period |
| v_input_3 | 0.618 | b |
| v_input_4 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-11-16 00:00:00
end: 2023-11-23 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version = 2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 19/12/2016
// This simple indicator gives you a lot of useful information - when to enter, when to exit
// and how to reduce risks by entering a trade on a double confirmed signal.
//
// You can use in the xPrice any series: Open, High, Low, Close, HL2, HLC3, OHLC4 and ect...
// You can change long to short in the Input Settings
// Please, use it only for learning or paper trading. Do not for real trading.
////////////////////////////////////////////////////////////
strategy(title="FX Sniper:  T3-CCI Strategy", shorttitle="T3-CCI")
CCI_Period = input(14, minval=1)
T3_Period = input(5, minval=1)
b = input(0.618)
reverse = input(false, title="Trade reverse")
hline(0, color=purple, linestyle=line)
xPrice = close
b2 = b*b
b3 = b2*b
c1 = -b3
c2 = (3*(b2 + b3))
c3 = -3*(2*b2 + b + b3)
c4 = (1 + 3*b + b3 + 3*b2)
nn = iff(T3_Period < 1, 1, T3_Period)
nr = 1 + 0.5*(nn - 1)
w1 = 2 / (nr + 1)
w2 = 1 - w1
xcci = cci(xPrice, CCI_Period)
e1 = w1*xcci + w2*nz(e1[1])
e2 = w1*e1 + w2*nz(e2[1])
e3 = w1*e2 + w2*nz(e3[1])
e4 = w1*e3 + w2*nz(e4[1])
e5 = w1*e4 + w2*nz(e5[1])
e6 = w1*e5 + w2*nz(e6[1])
xccir = c1*e6 + c2*e5 + c3*e4 + c4*e3
cciHcolor =  iff(xccir >= 0 , green,
               iff(xccir < 0, red, black))
pos =  iff(xccir > 0, 1,
         iff(xccir < 0, -1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(xccir, color=blue, title="T3-CCI")
plot(xccir, color=cciHcolor, title="CCIH", style = histogram)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/T3-CCI-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic Multi Indicator Trend Recognition Strategy with Triple Sync AnalysisPine Script · Trend following · 1d
- Dynamic Re entry Buy only StrategyPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Supertrend Advance StrategyPine Script · Trend following · 5m
- TSI and CCI Hull Moving Average Trend Tracking StrategyPine Script · Trend following · 1d
- Trend Tracking Strategy Based on Multi factor Model with Adaptive Trailing StoplossPine Script · Trend following · 1d