Strategy vault / Mean reversion
TD Sequential Dual Direction S R Trading Strategy
This strategy identifies support and resistance levels by tracking the consecutive up and down bars of prices, and combines moving averages as entry and stop loss signals to construct long and short trading…
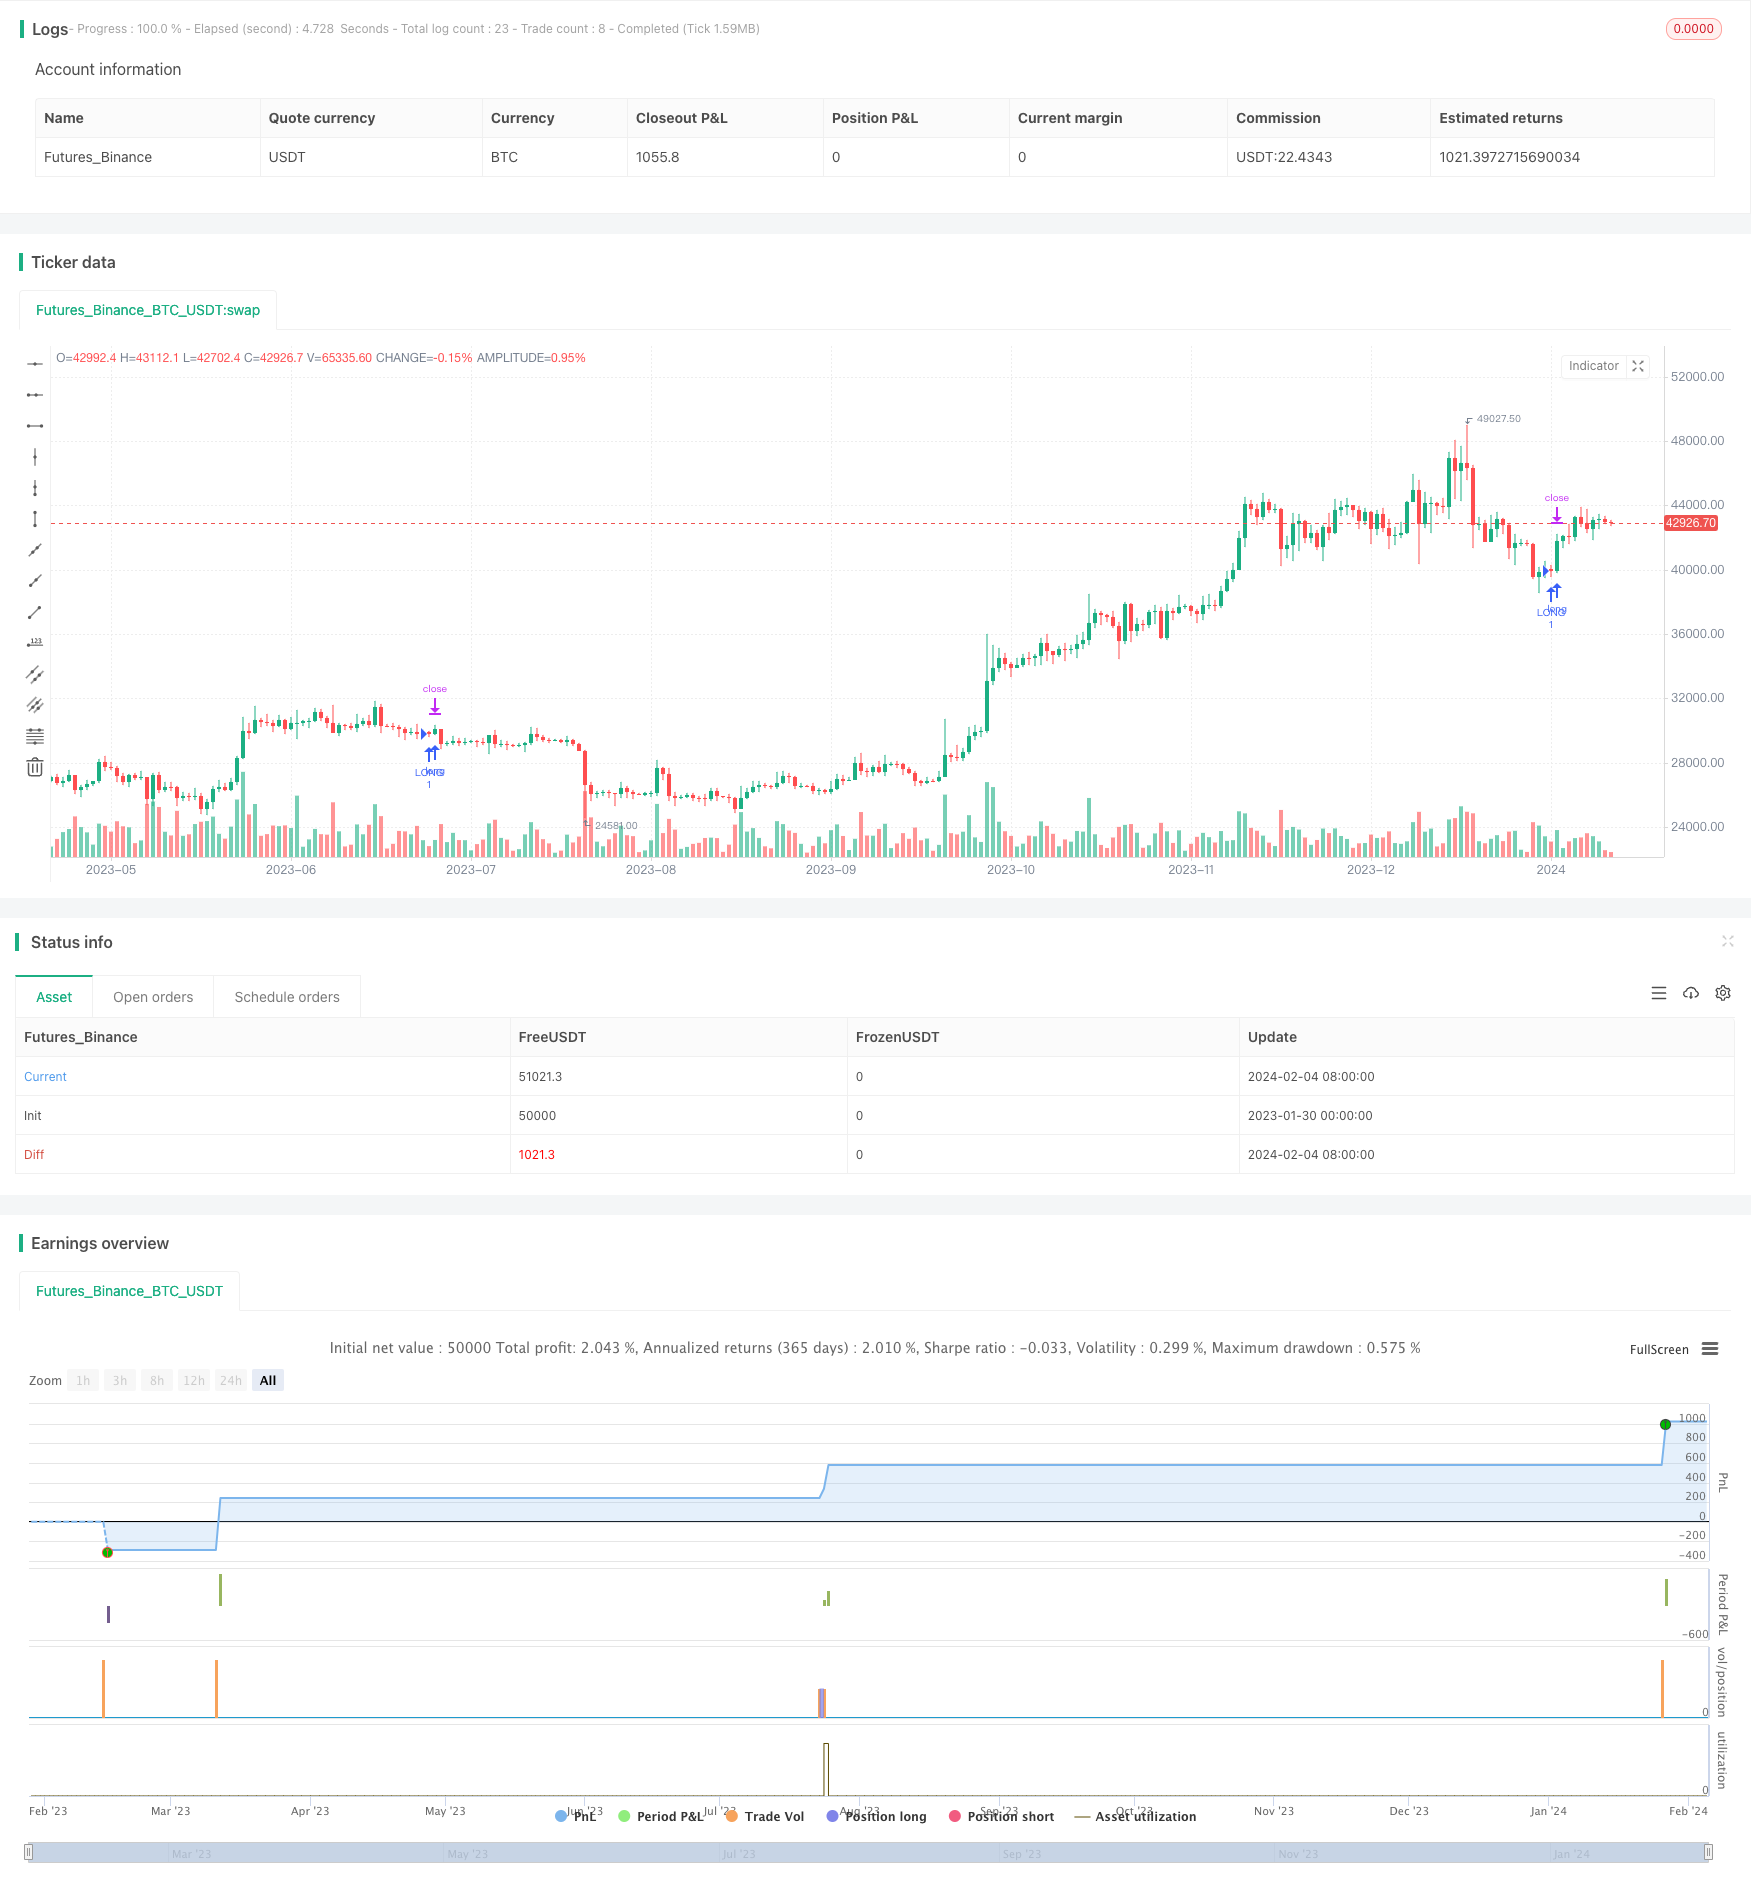
Overview
This strategy identifies support and resistance levels by tracking the consecutive up and down bars of prices, and combines moving averages as entry and stop loss signals to construct long and short trading strategies. The strategy can go both long and short, or only one side.
Principles
- S/R identification
- When the close price is higher than the close of 4 days ago for 4 consecutive days, mark the point as a downside support
- When the close price is lower than the close of 4 days ago for 4 consecutive days, mark the point as a upside resistance
- Signal generation
- After identifying a support level, if the up bar count reaches the threshold (default 9 days), generate long signal
- After identifying a resistance level, if the down bar count reaches the threshold (default 9 days), generate short signal
- MA filter and stop loss
- Require price to cross the MA line on entry, to filter signals
- Set stop loss to the MA line at entry
Advantages
- Judgment based on S/R is relatively reliable, not easily misled by short-term fluctuations
- Combining MA filter can reduce false signals
- Go both long and short to improve frequency and profit opportunities
- Parameters adjustable, can be optimized for different products and market situations
Risks and Solutions
- May suffer consecutive losses in trending markets
- Increase MA period to reduce trade frequency
- Probability of wrong S/R judgement
- Fine tune thresholds for S/R identification
- Stop loss may be triggered too often in whipsaw markets
- Loosen stop loss range
- Add trend indicator
Optimization Directions
- Add more technical indicators to improve robustness
- Trend, momentum etc.
- Optimize S/R identification logic
- Test impact of different parameters
- Parameter tuning for specific products and timeframes
- Adjustable range varies across products
- Develop adaptive stop loss mechanism
- Dynamically adjust stop loss based on market volatility
Conclusion
The strategy is relatively simple and reliable. By correctly identifying S/R levels it captures price reversal opportunities with high probability. Combining with MA ensures proper entry timing and avoids traps. Finally, the directional judgement is conservative but adaptable. Users can optimize parameters according to their market understanding and achieve even better results.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Long Only or Short Only or Both?: Both | Long Only | Short Only |
| v_input_2 | 9 | TD Sequential Long Price Flip |
| v_input_3 | 9 | TD Sequential Short Price Flip |
| v_input_4 | 0 | Long MA: SMA | EMA | VWMA |
| v_input_5 | 0 | Short MA: SMA | EMA | VWMA |
| v_input_6 | 10 | Long MA Exit Length |
| v_input_7 | 10 | Short MA Exit Length |
| v_input_8 | 0 | Long Trend Filter?: Above | Below | Don't Include |
| v_input_9 | 0 | Short Trend Filter?: Below | Above | Don't Include |
| v_input_10 | 0 | Trend MA: SMA | EMA | VWMA |
| v_input_11 | 200 | Trend MA Length |
| v_input_12 | true | Profit Target On/Off |
| v_input_13 | true | Profit Target % |
| v_input_14 | true | Stop Loss On/Off |
| v_input_15 | -1 | Stop Loss % |
Source Pine Script
/*backtest
start: 2023-01-30 00:00:00
end: 2024-02-05 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © GlobalMarketSignals

//@version=4
strategy("GMS: TD Sequential Strategy", overlay=true)

LongShort     = input(title="Long Only or Short Only or Both?", type=input.string, defval="Both", options=["Both", "Long Only", "Short Only"])
PriceFlipL    = input(title="TD Sequential Long Price Flip", type = input.integer ,defval=9)
PriceFlipS    = input(title="TD Sequential Short Price Flip", type = input.integer ,defval=9)
MAs1          = input(title="Long MA", type=input.string, defval="SMA", options=["SMA", "EMA", "VWMA"])
MAs2          = input(title="Short MA", type=input.string, defval="SMA", options=["SMA", "EMA", "VWMA"])
SMAlenL       = input(title="Long MA Exit Length", type = input.integer ,defval=10)
SMAlenS       = input(title="Short MA Exit Length", type = input.integer ,defval=10)
AboveBelowL   = input(title="Long Trend Filter?", type=input.string, defval="Above", options=["Above", "Below", "Don't Include"])
AboveBelowS   = input(title="Short Trend Filter?", type=input.string, defval="Below", options=["Above", "Below", "Don't Include"])
TLma          = input(title="Trend MA", type=input.string, defval="SMA", options=["SMA", "EMA", "VWMA"])
TrendLength   = input(title="Trend MA Length", type = input.integer ,defval=200)
PTbutton      = input(title="Profit Target On/Off", type=input.bool, defval=true)
ProfitTarget  = input(title="Profit Target %", type=input.float, defval=1, step=0.1, minval=0)
SLbutton      = input(title="Stop Loss On/Off", type=input.bool, defval=true)
StopLoss      = input(title="Stop Loss %", type=input.float, defval=-1, step=0.1, maxval=0)

//PROFIT TARGET & STOPLOSS

if PTbutton == true and SLbutton == true
    strategy.exit("EXIT", profit=((close*(ProfitTarget*0.01))/syminfo.mintick), loss=((close*(StopLoss*-0.01))/syminfo.mintick))
else
    if PTbutton == true and SLbutton == false
        strategy.exit("PT EXIT", profit=((close*(ProfitTarget*0.01))/syminfo.mintick))
    else
        if PTbutton == false and SLbutton == true
            strategy.exit("SL EXIT", loss=((close*(StopLoss*-0.01))/syminfo.mintick))
        else
            strategy.cancel("PT EXIT")

// S/R Code By johan.gradin (lines 36-46)
// Buy setup//
priceflip1 = barssince(close>close[4])
buysetup = close<close[4] and priceflip1
buy = buysetup and barssince(priceflip1!=9)
buyovershoot = barssince(priceflip1!=13) and buysetup
// Sell Setup //
priceflip = barssince(close<close[4])
sellsetup = close>close[4] and priceflip
sell = sellsetup and barssince(priceflip!=9)
sellovershoot = sellsetup and barssince(priceflip!=13)


///////
/////// SMA
///////

if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "SMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "SMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and  close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "SMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) )
    strategy.close("LONG", when = close>sma(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "SMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "SMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close<sma(close,TrendLength))
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "SMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "SMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "SMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and  close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "SMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) )
    strategy.close("LONG", when = close>sma(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "SMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "SMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close<sma(close,TrendLength))
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "SMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

///////
/////// EMA
///////

if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "EMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "EMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and  close<sma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "EMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) )
    strategy.close("LONG", when = close>ema(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "EMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<ema(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "EMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close<sma(close,TrendLength))
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "EMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) )
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "EMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "EMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and  close<sma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "EMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) )
    strategy.close("LONG", when = close>ema(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "EMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<ema(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "EMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close<sma(close,TrendLength))
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "EMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) )
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))


///////
/////// VWMA
///////

if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "VWMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "VWMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and  close<sma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "VWMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) )
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "VWMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<vwma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "VWMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close<sma(close,TrendLength))
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "VWMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "VWMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "VWMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and  close<sma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "VWMA" and TLma == "SMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) )
    strategy.close("LONG", when = close>vwma(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "VWMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<vwma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "VWMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close<sma(close,TrendLength))
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "VWMA" and TLma == "SMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))


//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////

///////
/////// SMA
///////


if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "SMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and close>ema(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "SMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and  close<ema(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "SMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) )
    strategy.close("LONG", when = close>sma(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "SMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close>ema(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "SMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close<ema(close,TrendLength))
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "SMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "SMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and close>ema(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "SMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and  close<ema(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "SMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) )
    strategy.close("LONG", when = close>sma(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "SMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close>ema(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "SMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close<ema(close,TrendLength))
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "SMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

///////
/////// EMA
///////

if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "EMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and close>ema(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "EMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and  close<ema(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "EMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) )
    strategy.close("LONG", when = close>ema(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "EMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close>ema(close,TrendLength))
    strategy.close("SHORT", when = close<ema(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "EMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close<ema(close,TrendLength))
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "EMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) )
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "EMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and close>ema(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "EMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and  close<ema(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "EMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) )
    strategy.close("LONG", when = close>ema(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "EMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close>ema(close,TrendLength))
    strategy.close("SHORT", when = close<ema(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "EMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close<ema(close,TrendLength))
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "EMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) )
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))


///////
/////// VWMA
///////

if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "VWMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and close>ema(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "VWMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and  close<ema(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "VWMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) )
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "VWMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close>ema(close,TrendLength))
    strategy.close("SHORT", when = close<vwma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "VWMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close<ema(close,TrendLength))
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "VWMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "VWMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and close>ema(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "VWMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and  close<ema(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "VWMA" and TLma == "EMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) )
    strategy.close("LONG", when = close>vwma(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "VWMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close>ema(close,TrendLength))
    strategy.close("SHORT", when = close<vwma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "VWMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close<ema(close,TrendLength))
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "VWMA" and TLma == "EMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))


//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////

///////
/////// SMA
///////


if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "SMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and close>vwma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "SMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and  close<vwma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "SMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) )
    strategy.close("LONG", when = close>sma(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "SMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close>vwma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "SMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close<vwma(close,TrendLength))
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "SMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "SMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and close>vwma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "SMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) and  close<vwma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "SMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<sma(close,SMAlenL) )
    strategy.close("LONG", when = close>sma(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "SMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close>vwma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "SMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) and close<vwma(close,TrendLength))
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "SMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>sma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<sma(close,SMAlenS))

///////
/////// EMA
///////

if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "EMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and close>vwma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "EMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and  close<vwma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "EMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) )
    strategy.close("LONG", when = close>ema(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "EMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close>vwma(close,TrendLength))
    strategy.close("SHORT", when = close<ema(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "EMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close<vwma(close,TrendLength))
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "EMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) )
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "EMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and close>vwma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "EMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) and  close<vwma(close,TrendLength))
    strategy.close("LONG", when = close>ema(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "EMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<ema(close,SMAlenL) )
    strategy.close("LONG", when = close>ema(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "EMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close>vwma(close,TrendLength))
    strategy.close("SHORT", when = close<ema(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "EMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) and close<vwma(close,TrendLength))
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "EMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>ema(close,SMAlenS) )
    strategy.close("SHORT",  when = close<ema(close,SMAlenS))


///////
/////// VWMA
///////

if LongShort =="Long Only" and AboveBelowL == "Above" and MAs1 == "VWMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and close>vwma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Below" and MAs1 == "VWMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and  close<vwma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Long Only" and  AboveBelowL == "Don't Include" and MAs1 == "VWMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) )
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

///////

if LongShort =="Short Only" and  AboveBelowS == "Above" and MAs2 == "VWMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close>vwma(close,TrendLength))
    strategy.close("SHORT", when = close<vwma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Below" and MAs2 == "VWMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close<vwma(close,TrendLength))
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

if LongShort =="Short Only" and  AboveBelowS == "Don't Include" and MAs2 == "VWMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

///////

if LongShort =="Both" and AboveBelowL == "Above" and MAs1 == "VWMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and close>vwma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Below" and MAs1 == "VWMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) and  close<vwma(close,TrendLength))
    strategy.close("LONG", when = close>vwma(close,SMAlenL))

if LongShort =="Both" and  AboveBelowL == "Don't Include" and MAs1 == "VWMA" and TLma == "VWMA"
    strategy.entry("LONG", true, when = buysetup and barssince(priceflip1!=PriceFlipL) and close<vwma(close,SMAlenL) )
    strategy.close("LONG", when = close>vwma(close,SMAlenL))


if LongShort =="Both" and  AboveBelowS == "Above" and MAs2 == "VWMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close>vwma(close,TrendLength))
    strategy.close("SHORT", when = close<vwma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Below" and MAs2 == "VWMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) and close<vwma(close,TrendLength))
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))

if LongShort =="Both" and  AboveBelowS == "Don't Include" and MAs2 == "VWMA" and TLma == "VWMA"
    strategy.entry("SHORT", false, when = sellsetup and barssince(priceflip!=PriceFlipS) and close>vwma(close,SMAlenS) )
    strategy.close("SHORT",  when = close<vwma(close,SMAlenS))


//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/TD-Sequential-Dual-Direction-S-R-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- Trend Reversal Momentum Indicators Crossover Tracking StrategyPine Script · Mean reversion · 1h
- Fibonacci Channel Based Candlestick Reversal Trading StrategyPine Script · Mean reversion · 1h
- Reversal Fluctuation CAT StrategyPine Script · Mean reversion · 2h