Strategy vault / Trend following
The Interwoven Moving Average Crossover Strategy
This strategy generates trading signals based on the crossover of simple moving average and weighted moving average, combined with stop loss and take profit to manage positions. The strategy integrates dynamic…
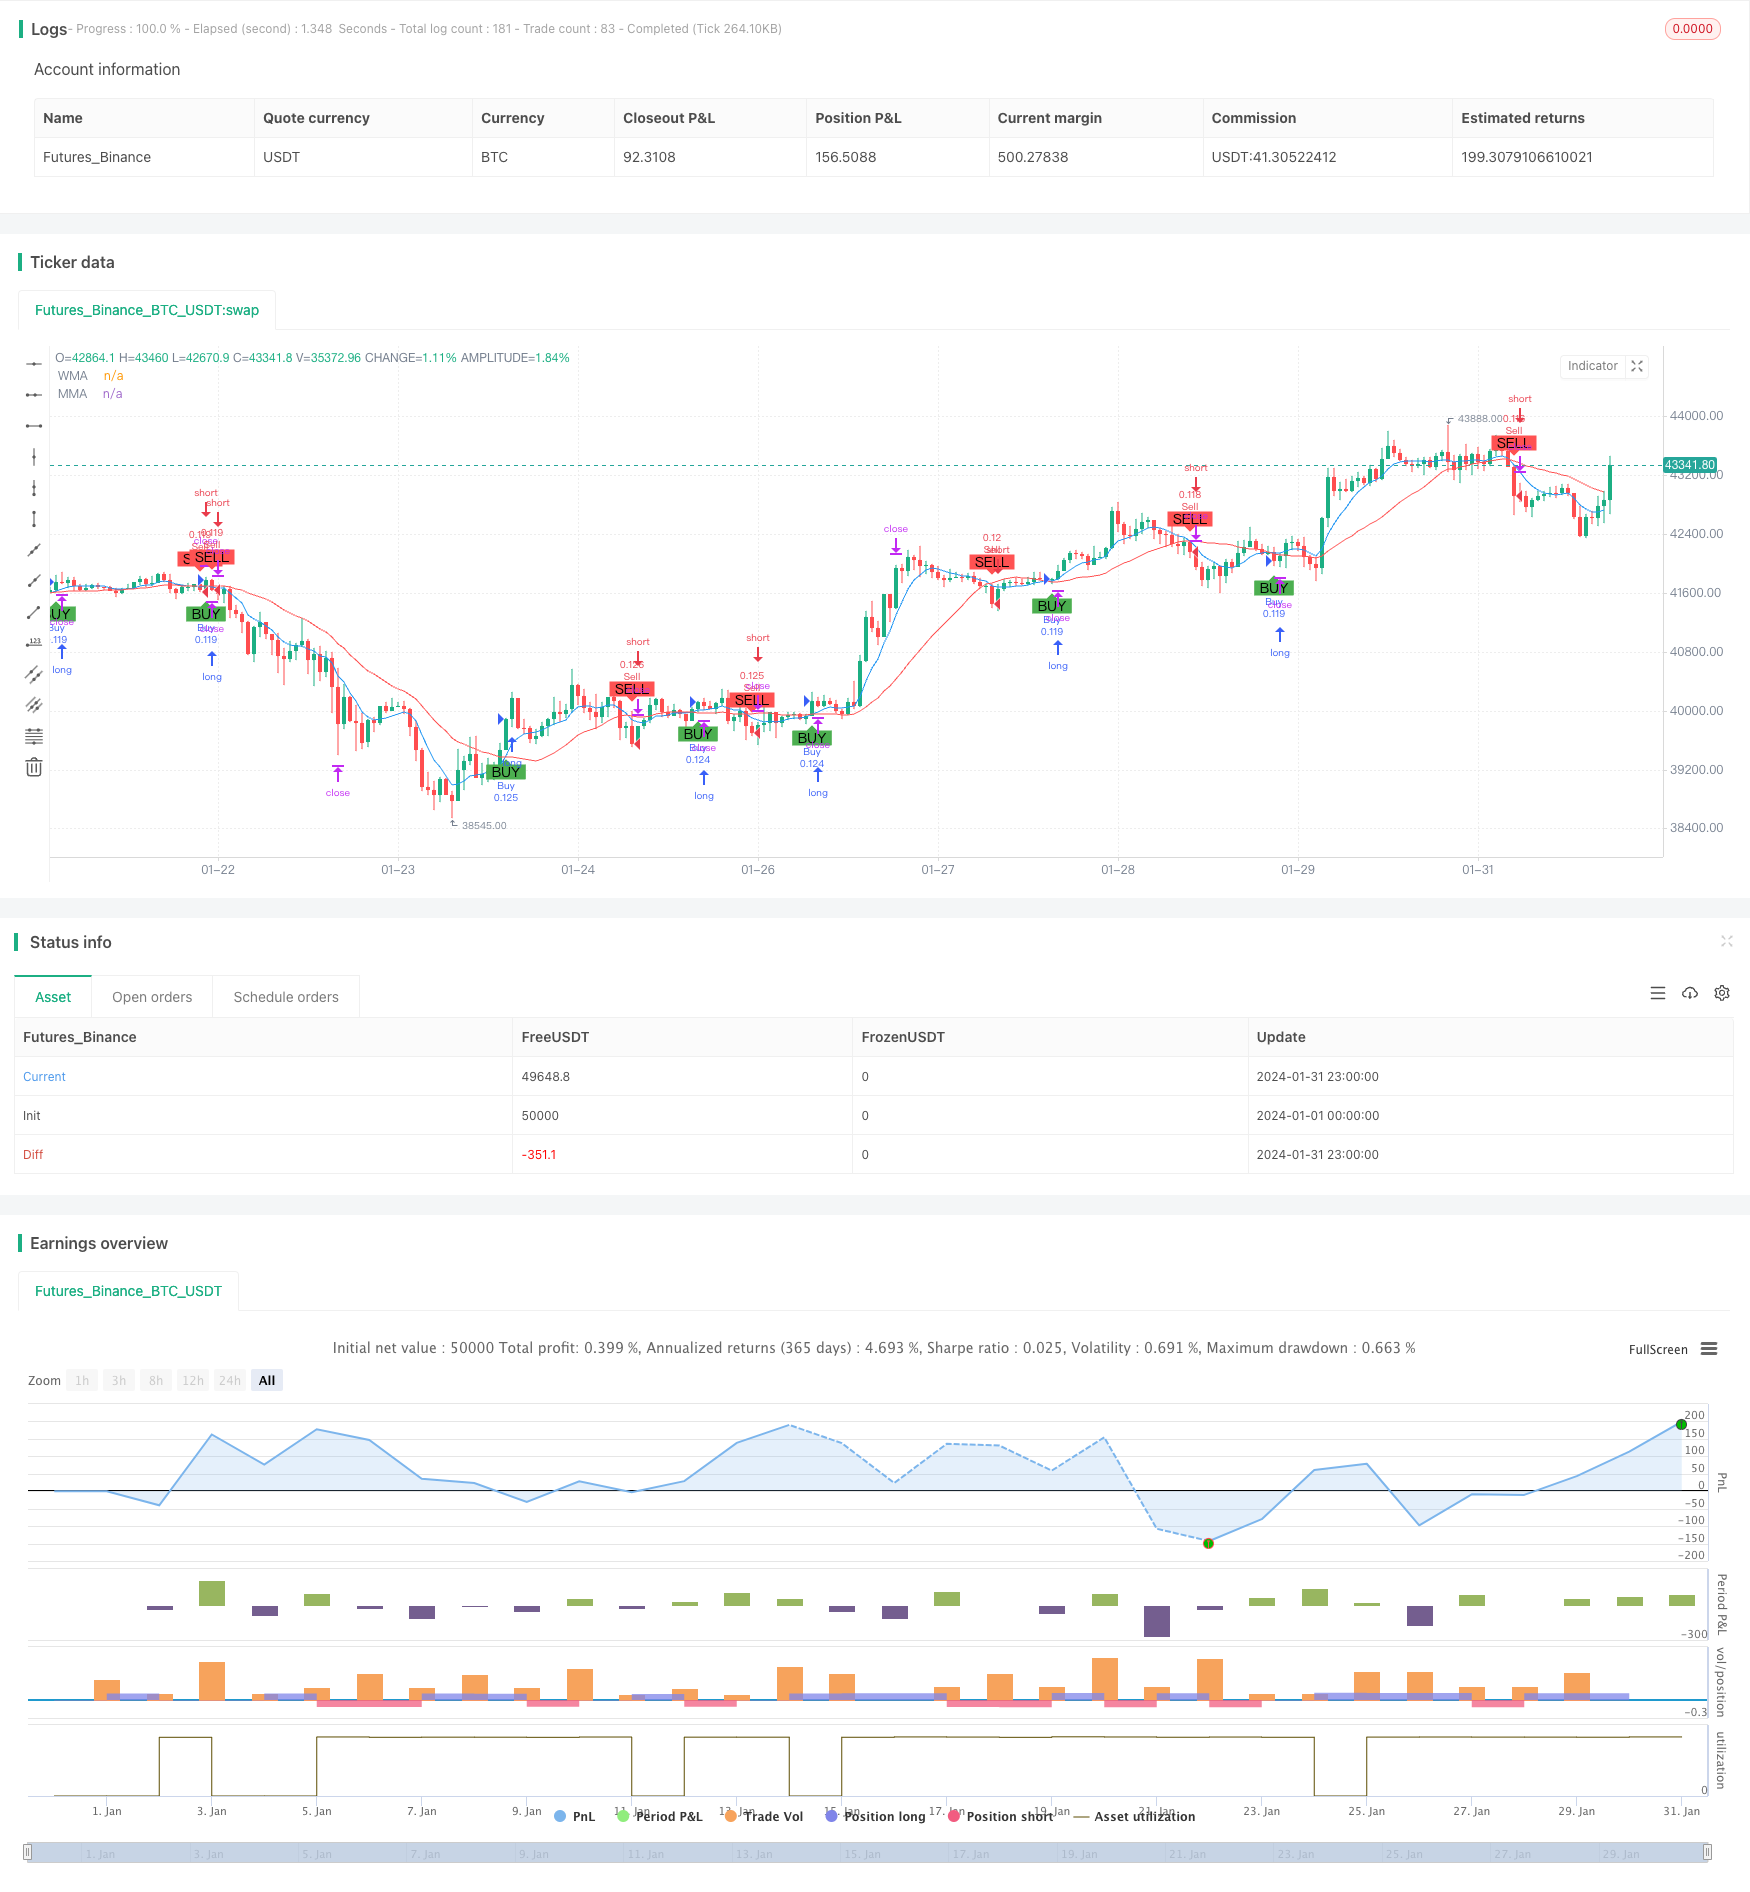
Overview
This strategy generates trading signals based on the crossover of simple moving average and weighted moving average, combined with stop loss and take profit to manage positions. The strategy integrates dynamic factors (moving average crossover) and static factors (fixed stop loss and take profit ratios) to achieve an interwoven effect of dynamic and static elements.
Strategy Logic
The core logic is to calculate two moving averages with different periods, one is the 9-day simple moving average and the other is the 21-day weighted moving average. When the short-period 9-day SMA crosses above the long-period 21-day WMA, a buy signal is generated. When the short-period line crosses below the long-period line, a sell signal is generated.
After receiving the signal, orders are placed according to the set stop loss and take profit ratios. For example, if the stop loss ratio is set at 5%, then the stop loss price will be set at 95% of the entry price. If the take profit ratio is 5%, then the take profit price will be set at 105% of the entry price. This realizes the fusion of dynamic factors (moving average crossover deciding entry and exit timing) and static factors (fixed stop loss and take profit ratios).
Advantage Analysis
The strategy combines dynamic technical indicators and static strategy parameters, possessing the pros of both dynamic and static systems. Technical indicators can dynamically capture market characteristics, which is beneficial for catching trends. Parameter settings provide stable risk and return control, which helps to reduce the randomness in position management.
Compared with pure dynamic systems, this strategy is more robust in position management, which reduces the impact of irrational decisions. Compared with pure static systems, this strategy is more flexible in entry selections, which adapts better to market changes. Therefore, this strategy has good overall robustness and profitability.
Risk Analysis
The risks of this strategy mainly come from two aspects. First, the possibility of wrong signals from the moving averages. When the market is range-bound, the moving averages may have frequent crossovers, causing the strategy to be whipsawed.
Second, the risk that fixed stop loss and take profit cannot adapt to extreme market conditions. When black swan events cause huge market swings, the preset stop loss and take profit levels may be penetrated, failing to effectively control risks.
The countermeasures are: first, avoid key time nodes to reduce the probability of wrong signals; second, enable adaptive stop loss algorithms according to market volatility and special events, making stop loss and take profit adjust with the market.
Optimization Directions
This strategy can be optimized from the following aspects:
Test different parameter combinations to find the optimal parameters;
Add filtering conditions to avoid invalid signals;
Apply adaptive stop loss algorithms to move with the market;
Incorporate other indicators to judge trend strength, avoiding range-bound markets;
Utilize machine learning methods to automatically optimize parameters.
Through testing parameters, adding filters, improving stops, judging trends, etc., the stability and profitability of the strategy can be further enhanced.
Summary
The strategy successfully combines dynamic indicators and static parameters, balancing flexibility and robustness. Compared with pure dynamic and static strategies, this strategy performs better overall. Of course, there is still room for optimization by adjusting parameters, adding filters, adaptive stops, machine learning, etc., to make the strategy more effective.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 9 | WMA Length |
| v_input_int_2 | 21 | MMA Length |
| v_input_float_1 | 5 | Stop Loss (%) |
| v_input_float_2 | 5 | Take Profit (%) |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("WMA vs MMA Crossover Strategy with SL/TP", shorttitle="WMA_MMA_Cross_SL_TP", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=10)

// Définition des périodes pour les moyennes mobiles
wmaLength = input.int(9, title="WMA Length")
mmaLength = input.int(21, title="MMA Length")

// Paramètres de Stop Loss et Take Profit en pourcentage
stopLossPercentage = input.float(5, title="Stop Loss (%)") / 100
takeProfitPercentage = input.float(5, title="Take Profit (%)") / 100

// Calcul des moyennes mobiles
wmaValue = ta.wma(close, wmaLength)
mmaValue = ta.sma(close, mmaLength)

// Conditions pour les signaux d'achat et de vente
buySignal = ta.crossover(wmaValue, mmaValue)
sellSignal = ta.crossunder(wmaValue, mmaValue)

// Génération des ordres en fonction des signaux
if buySignal
    strategy.entry("Buy", strategy.long)
    strategy.exit("Exit Buy", "Buy", stop=strategy.position_avg_price * (1 - stopLossPercentage), limit=strategy.position_avg_price * (1 + takeProfitPercentage))

if sellSignal
    strategy.entry("Sell", strategy.short)
    strategy.exit("Exit Sell", "Sell", stop=strategy.position_avg_price * (1 + stopLossPercentage), limit=strategy.position_avg_price * (1 - takeProfitPercentage))

// Affichage des moyennes mobiles sur le graphique
plot(wmaValue, color=color.blue, title="WMA")
plot(mmaValue, color=color.red, title="MMA")

// Affichage des signaux sur le graphique pour référence
plotshape(series=buySignal, location=location.belowbar, color=color.green, style=shape.labelup, title="Buy Signal", text="BUY")
plotshape(series=sellSignal, location=location.abovebar, color=color.red, style=shape.labeldown, title="Sell Signal", text="SELL")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/The-Interwoven-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m