This BIST stocks 4 stage quantitative acquisition strategy
This BIST stocks 4-stage quantitative acquisition strategy is based on a four-stage buying to track the wave movements. It enters the market during post-manipulation and sells when buyer demand increases. This…
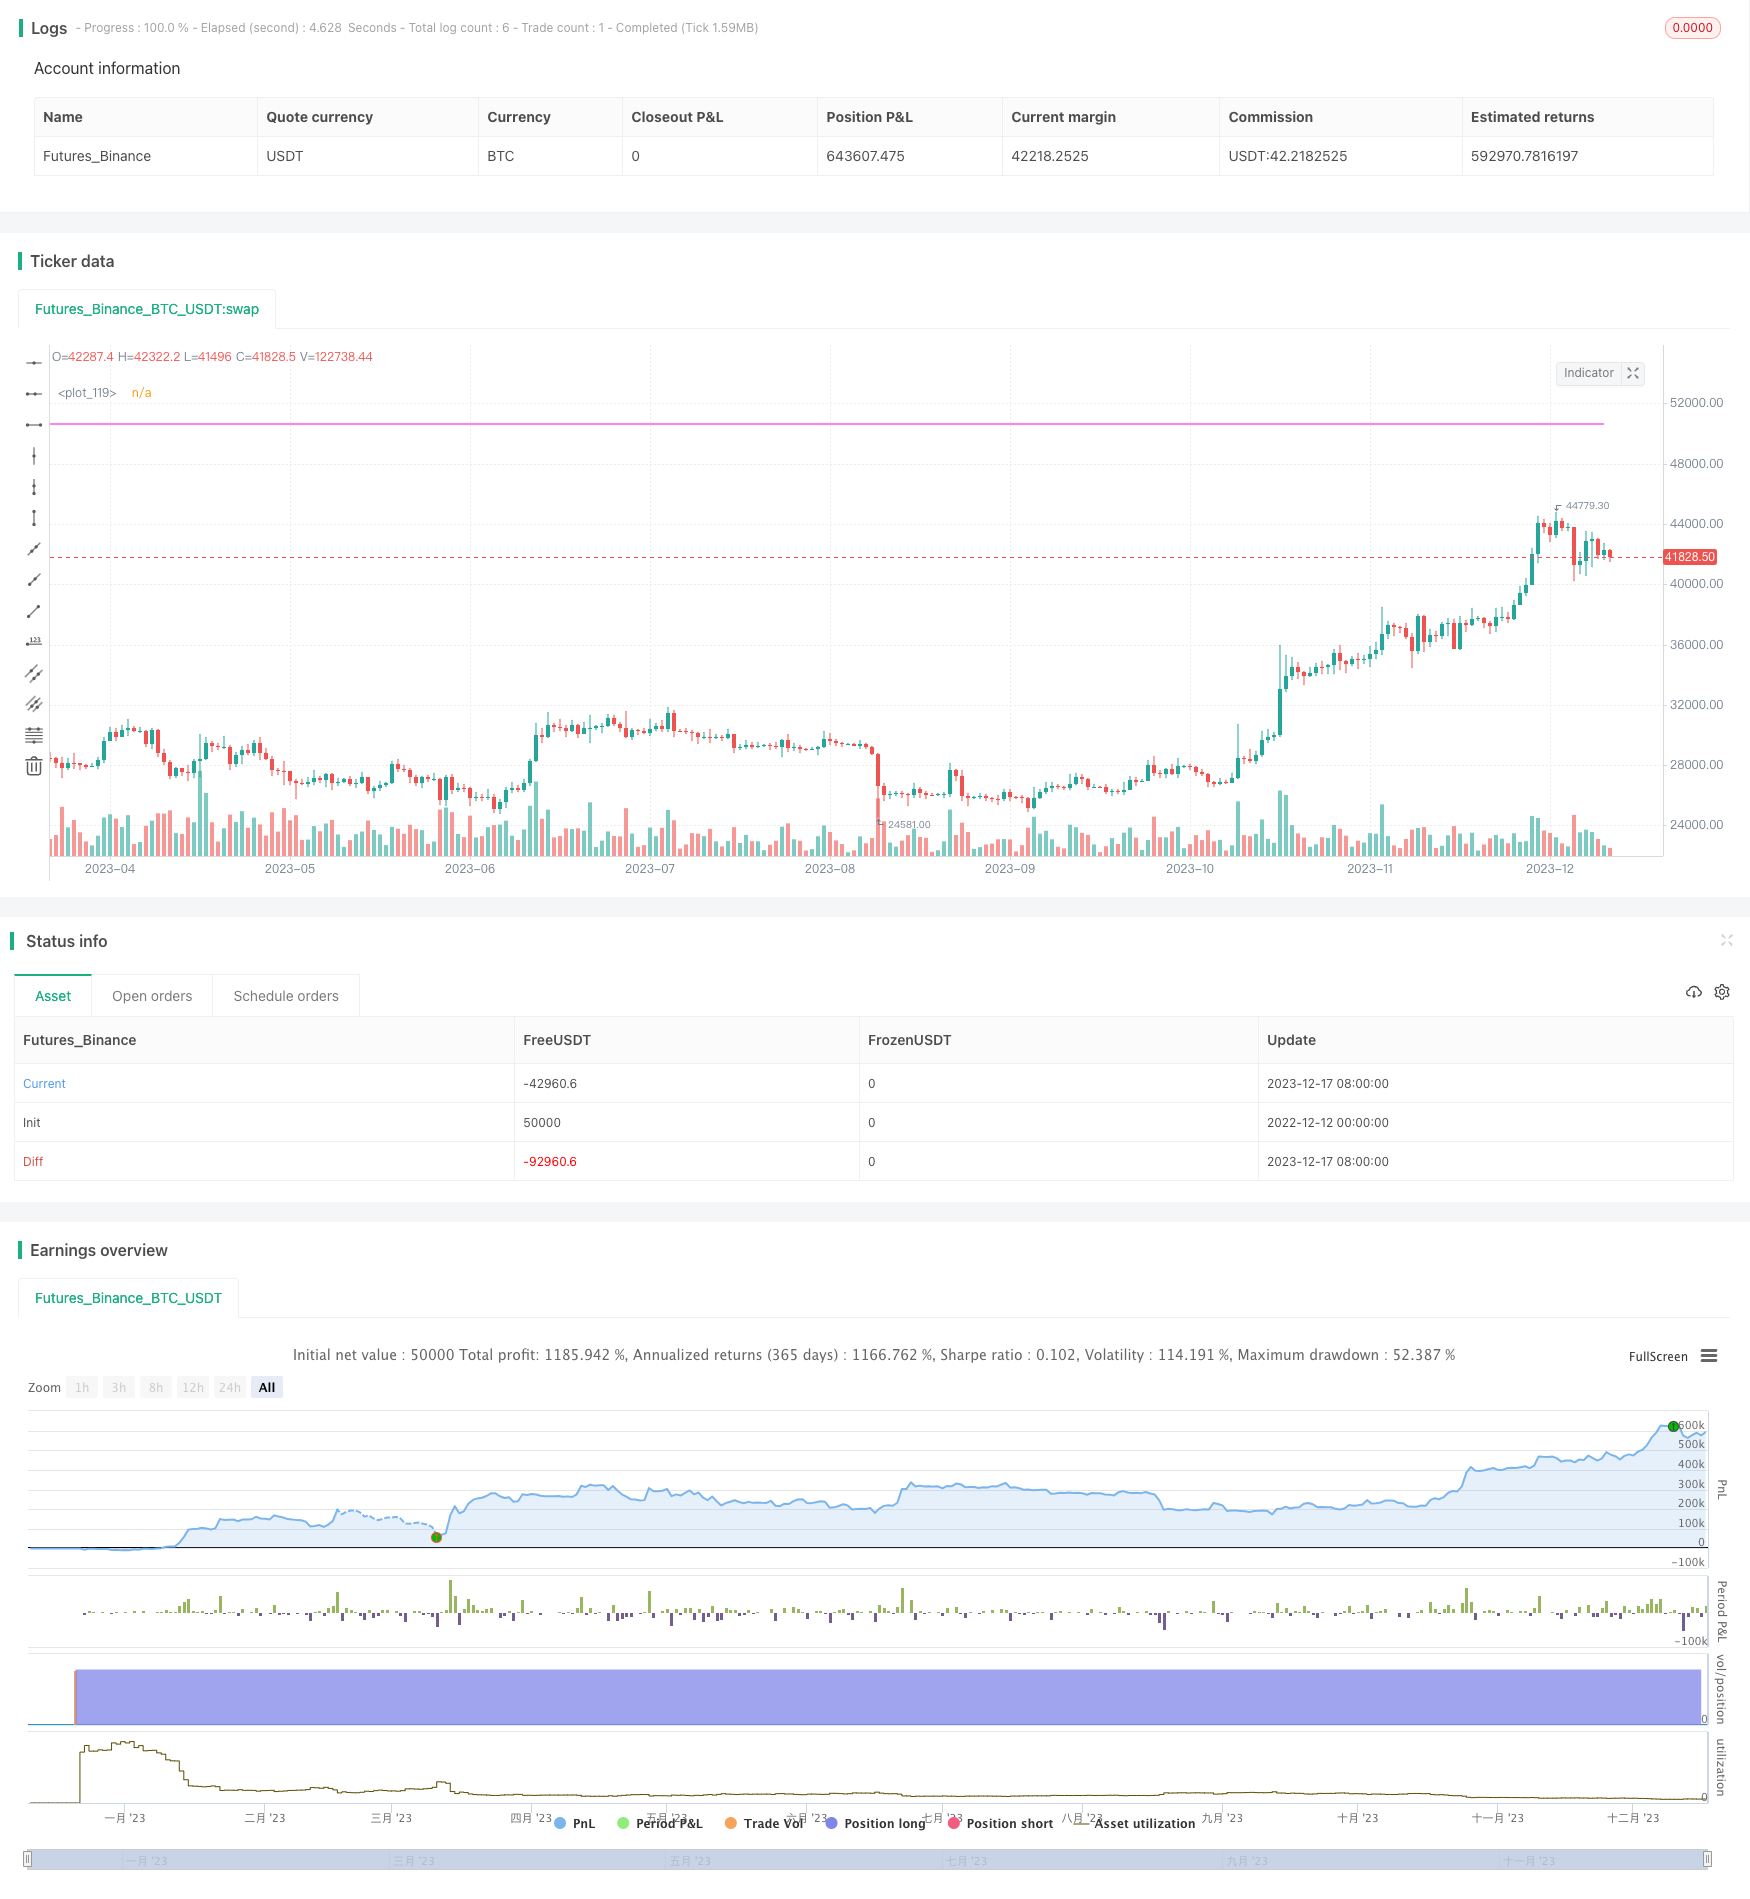
This BIST stocks 4-stage quantitative acquisition strategy is based on a four-stage buying to track the wave movements. It enters the market during post-manipulation and sells when buyer demand increases. This strategy is suitable for stocks with large fluctuations, and achieves better cost control through stage-by-stage purchases.
Strategy Principles
This strategy first calculates the resistance and support lines. The resistance line is determined by the intersection of the close price and the oscillating moving average of the high price, while the support line is determined by the intersection of the close price and the oscillating moving average of the low price.
When the price breaks below the support line, if the price is within the set buying range from the resistance line, it will buy in 25% of the position in the first stage. Then it will buy another 25% of the position around the first buy price, and so on for 4 times, eventually holding 100% of the position.
When the stock price exceeds twice the opening cost, it will close out all positions.
Advantages of the Strategy
- Lower buying costs through four-stage purchases
- Better entry points by tracking stock fluctuations
- Reasonable take profit point for decent returns
Risks and Solutions
Continued stock decline without stop loss, leading to large losses
- Set reasonable stop loss to effectively control losses
Improper parameter settings make multiple buy points too close to diversify costs
- Set appropriate price differences between buying stages
Stop loss point too wide to effectively control losses
- Set suitable stop distance based on actual trading environment and psychological tolerance
Optimization Directions
Adjust parameters for different types of stocks to better fit their characteristics
Add volatility indicators to buy when volatility rises
Optimize take profit by using trailing stop to achieve higher returns
Add stop loss settings to cut losses when price breaks certain levels
Summary
The BIST stocks 4-stage quantitative acquisition strategy is well suited for popular concept stocks overall. By staging the purchases, it can effectively utilize the volatility of the stocks to get better costs when prices pull back. Also, the reasonable take profit and stop loss settings allow it to perform well in risk control. With continual parameter adjustments and optimizations based on actual market environments, this strategy can reliably deliver alpha.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 30 | Alım_Üst_Çizgi |
| v_input_2 | 90 | Alım_Alt_Çizgi |
| v_input_3 | true | Barcolor |
| v_input_4 | true | Bgcolor |
| v_input_5 | 40 | Satım_Üst_Çizgi |
| v_input_6 | 300 | Satım_Alt_Çizgi |
| v_input_7 | true | Barcolor2 |
| v_input_8 | true | Bgcolor2 |
| v_input_9 | 25 | Alış Aralığı % |
| v_input_10 | 45 | Satış aralığı % |
| v_input_11 | 0.12 | ALIM YERİ % |
| v_input_12 | long entry message | message_long_entry |
| v_input_13 | long exit message | message_long_exit |
| v_input_14 | 2 | PROFİT SATIŞ SEVİYESİ |
Source Pine Script
/*backtest
start: 2022-12-12 00:00:00
end: 2023-12-18 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Cantalk

//@version=5
strategy("BİST_100 HİSSELERİ 1_SAAT 4 KADEME ALIM",overlay = true, pyramiding=4, initial_capital=10000, process_orders_on_close=true, commission_type=strategy.commission.percent, commission_value=0.002)


LB2 = input(30, title="Alım_Üst_Çizgi")
LB = input(90, title="Alım_Alt_Çizgi")
Barcolor=input(true,title="Barcolor")
Bgcolor=input(true,title="Bgcolor")
//////////////////////////////////////////////////////////////////////

//////////////////////////////////////////////////////////////////////////////////////
RDirenc = ta.valuewhen(ta.cross(ta.hma(close, LB2), close), ta.highest(high, LB2), 1)
SDestek = ta.valuewhen(ta.cross(close, ta.hma(close, LB)), ta.lowest(low, LB), 1)


//plot(RDirenc,title="Resistance", color=#f7d707fc, linewidth =2)
//plot(SDestek,title="Support", color=#064df4, linewidth = 2)

//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////

LB22 = input(40, title="Satım_Üst_Çizgi")
LB1 = input(300, title="Satım_Alt_Çizgi")

Barcolor2=input(true,title="Barcolor2")
Bgcolor2=input(true,title="Bgcolor2")
//////////////////////////////////////////////////////////////////////

//////////////////////////////////////////////////////////////////////////////////////
RDirenc2 = ta.valuewhen(ta.cross(ta.hma(close, LB22), close), ta.highest(high, LB22), 1)
SDestek2 = ta.valuewhen(ta.cross(close, ta.hma(close, LB1)), ta.lowest(low, LB1), 1)


//plot(RDirenc2,title="Resistance2", color=#f40a0afc, linewidth =2)
//plot(SDestek2,title="Support2", color=#0eed0e, linewidth = 2)

//colors=if(close>RDirenc, color= #008000,if(SDestek<close,color=#FFFF00,color=#FF0000))

aralik_yuzde_alis = ((RDirenc-SDestek)/SDestek)*100
fark = input(25.0, title="Alış Aralığı %")


aralik_yuzde_satis = ((RDirenc2-SDestek2)/SDestek2)*100
fark2 = input(45.0, title="Satış aralığı %")


buyProcess = input(0.12, "ALIM YERİ %")
//buyProcess2 = input(0.10, "ALIM YERİ-2 %")
//buyProcess3 = input(0.10, "ALIM YERİ-3 %")


buy1 = strategy.position_avg_price - (strategy.position_avg_price * buyProcess)

buy2 = buy1 - (strategy.position_avg_price * buyProcess)

buy3 = buy2 - (strategy.position_avg_price * buyProcess)

buy4 = buy3 - (strategy.position_avg_price * buyProcess)


//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
isLong1 = if ta.crossover(close, SDestek) and aralik_yuzde_alis < fark
    1
else
    0


isLong2 = if ta.crossover(close, SDestek) and (close <=  buy1)
    1
else
    0

isLong3 = if ta.crossover(close, SDestek) and (close <=  buy2)
    1
else
    0

isLong4 = if ta.crossover(close, SDestek) and (close <= buy3)
    1
else
    0


message_long_entry  = input("long entry message")
message_long_exit   = input("long exit message")


fullProfit = input(2.00, "PROFİT SATIŞ SEVİYESİ")
profit = strategy.position_avg_price * fullProfit
///////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////

strategy.entry(id = "BUY-1", direction = strategy.long, qty = 25, when = (isLong1 and strategy.position_size == 0), alert_message = message_long_entry)
strategy.entry(id = "BUY-2", direction = strategy.long, qty = 25, when = (isLong2 and strategy.position_size == 25), alert_message = message_long_entry)
strategy.entry(id = "BUY-3", direction = strategy.long, qty = 25, when = (isLong3 and strategy.position_size == 50), alert_message = message_long_entry)
strategy.entry(id = "BUY-4", direction = strategy.long, qty = 25, when = (isLong4 and strategy.position_size == 75), alert_message = message_long_entry)


buyclose1 = if  (close >= (strategy.position_avg_price + profit)) and aralik_yuzde_satis > fark2
    close


strategy.exit("EXİT",qty_percent = 100, stop = buyclose1)


aritmeticClose =  strategy.position_avg_price + profit
plot(aritmeticClose, color = color.rgb(248, 5, 240), linewidth = 1, style = plot.style_linebr)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/This-BIST-stocks-4-stage-quantitative-acquisition-strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Bollinger Band Volatility Tracking StrategyPine Script · Volatility · 1d
- Dual EMA Volatility Adaptive Trading Strategy with Multi Tiered Profit Optimization SystemPine Script · Volatility · 1d
- Dual Moving Average Volatility Tracking StrategyPine Script · Volatility · 1h
- Dynamic ATR Trailing Stop Trading Strategy Market Volatility Adaptive SystemPine Script · Volatility · 1d
- Multi Indicator Dynamic Volatility Alert Trading SystemPine Script · Volatility · 1m
- Multi Indicator Volatility Trading RSI EMA ATR StrategyPine Script · Volatility · 3m