Three Moving Average System Exodus
This system is a two-way contract strategy. When the conditions are met, whether to go long or short, the order amount is the number of contracts. When using Binance, the order amount is a few BTC. When using Huobi…
This system is a two-way contract strategy. When the conditions are met, whether to go long or short, the order amount is the number of contracts. When using Binance, the order amount is a few BTC. When using Huobi, the order amount unit is Zhang. [7-31Update] The parameters of this strategy are suitable for operation at the 1-hour level, but the number of orders opened at the hour-level is too small, so the minute-level is updated. However, parameters need to be modified manually at the minute level.
The following backtest results are in hourly intervals
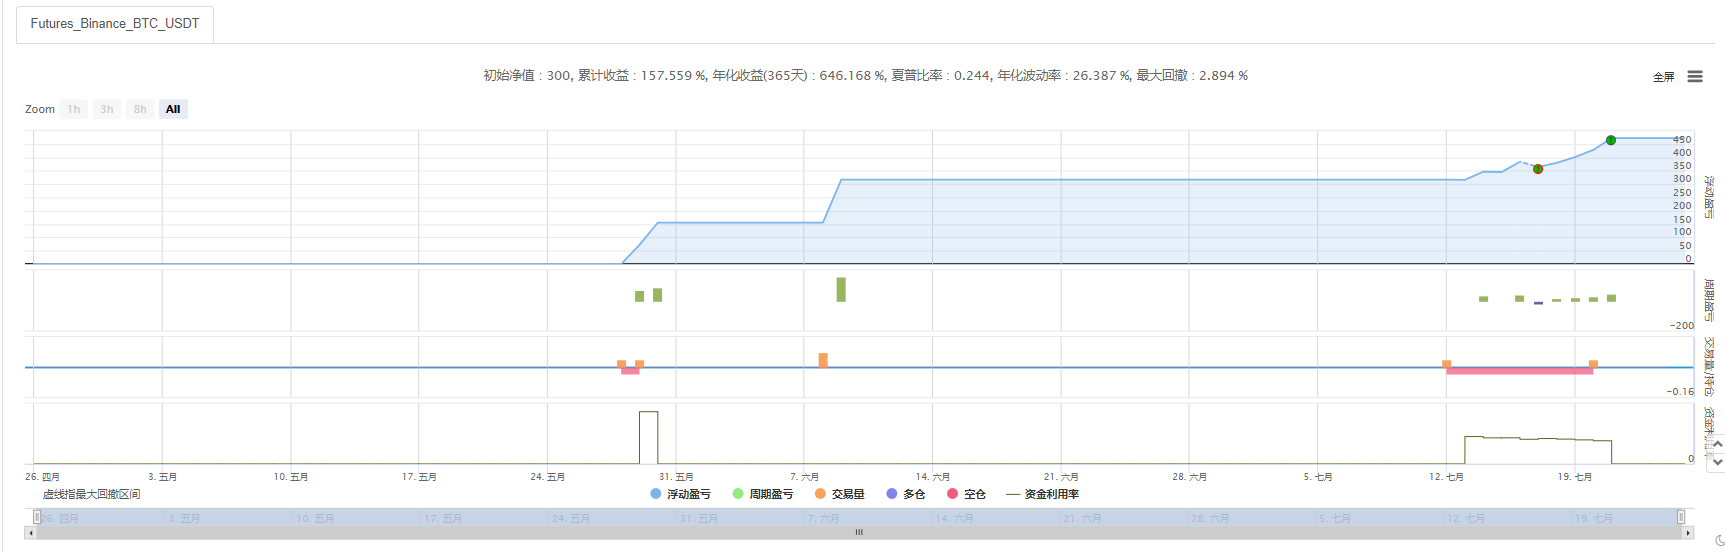
**** 4-27to7-25****
Principal 300, order quantity0.04btc
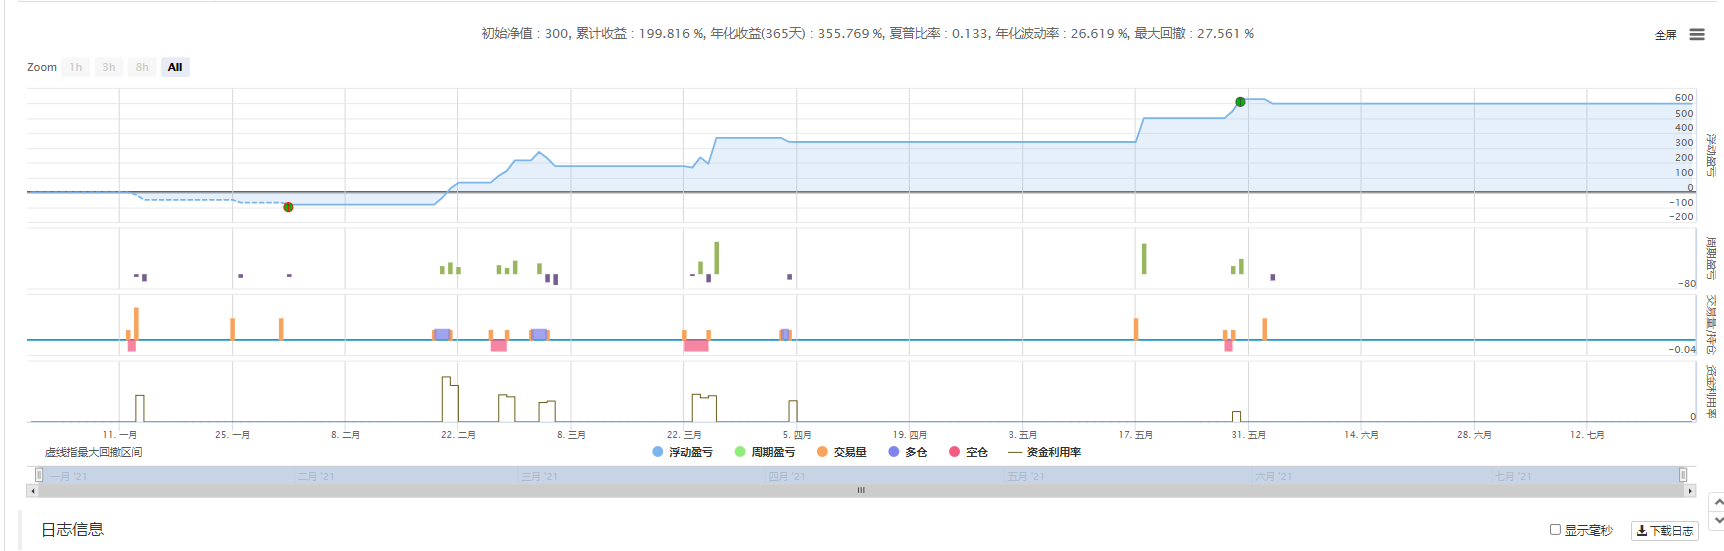
 **** 1-1to7-25****
Principal 300, order amount 0.03 BTC, order quantity 0.04 is insufficient principal
If you want to use it yourself, please conduct a backtest to determine your order volume.
If you make money, consider supporting the author
Parameters
| Name | Default | What it controls |
|---|---|---|
| afterEmaCrossTime | 4 | Only Allow Operation if MACD Meets Conditions Within a Few Candles After K-Line Golden Cross or Death Cross |
| buyVolume | 0.016 | Transaction quantity(0.016BTC) |
| stopLossRate | true | Stop loss rate (leverage not calculated)) |
| winLossRate | 5 | Profit and Loss Ratio |
| period | 60 | Period (minutes) |
| EMA1 | 8 | Fastest moving average period |
| EMA2 | 34 | Medium-speed moving average period |
| EMA3 | 89 | Slowest moving average period |
| MACD1 | 16 | MACDParameters1 |
| MACD2 | 26 | MACDParameters2 |
| MACD3 | 9 | MACDParameters3 |
Source JavaScript
/*backtest
start: 2021-04-27 00:00:00
end: 2021-07-25 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":300}]
args: [["afterEmaCrossTime",4],["buyVolume",0.04],["winLossRate",5]]
*/

function GetCrossStatus(a, lastA, b, lastB) {
    let lastStatus = lastA < lastB;
    let curStatus = a < b;
    let crosssStaus = 0; //0Indicates no crossover,1means golden cross,2means death cross
    //Determine golden cross or death cross,Simultaneously determine if it is greater at the moment0Axis or less than0axis,Because in this system it requires a golden cross whenmacd>0Only then does it make sense; during a death crossmacd<0makes sense
    if (curStatus != lastStatus) //Different states indicate golden cross or death cross
    {
        if (a > b) {
            crosssStaus = 1; //golden cross
        }
        if (a < b)
            crosssStaus = 2; //death cross
    }
    return crosssStaus;
}
var lastOpenTime;

function GetCurRecord(records) {
    return records[records.length - 1];
}

function GetCurTime(records) {
    return GetCurRecord(records).Time;
}

function GetCurPrice(records) {
    return GetCurRecord(records).Close;
}

function Open(direction) {
    let pos = exchange.GetPosition()[0];

    if (pos != null) {
        return;
    }
    let amount = buyVolume;
    if (direction == 1) { //go long
        Log("go long", amount);
        exchange.SetDirection("buy");
        exchange.Buy(-1, amount);
    }
    if (direction == 2) { //go short
        Log("go short", amount);
        exchange.SetDirection("sell");
        exchange.Sell(-1, amount);
    }

}

function Close(ticker,fastLine,midLine) {
    let pos = exchange.GetPosition()[0];

    if (pos == null) {
        return;
    }

    if (pos.Type == PD_LONG) {
        if (ticker.Last < pos.Price*(1- stopLossRate/100) || ticker.Last > pos.Price*(1+(stopLossRate*winLossRate)/100)) {
            Log("close long,The opening price is:",pos.Price,"This profit:",pos.Profit);
            exchange.SetDirection("closebuy");
            exchange.Sell(-1, pos.Amount);

        }
    }
    if (pos.Type == PD_SHORT) {
        if (ticker.Last > pos.Price*(1+ stopLossRate/100) || ticker.Last < pos.Price*(1-(stopLossRate*winLossRate)/100) ) {
            Log("close short,The opening price is:",pos.Price,"This profit:",pos.Profit);
            exchange.SetDirection("closesell");
            exchange.Buy(-1, pos.Amount);
        }
    }
}


var lastEmaCrossTime = 0;
var lastMacdCrossTime = 0;

function NearMacdCross(time) {
    //Log("MACD",time,lastMacdCrossTime,time - lastMacdCrossTime);
    return time - lastMacdCrossTime <= afterEmaCrossTime * 1000 * 3600;
}

function NearEmaCross(time) {
    //Log("EMA",time,lastMacdCrossTime,time - lastMacdCrossTime);
    return time - lastEmaCrossTime <= afterEmaCrossTime * 1000 * 3600;
}


var emaMeet = 0; //0Indicates not satisfied,1Meets long condition,2Meets short condition
var macdMeet = 0; //JudgmentmacdWhether the condition is met,0Indicates not satisfied,1Indicates long conditions are met,2Indicates short conditions are met
function main() {
    exchange.SetContractType("swap");
    while (1) {
        let r = exchange.GetRecords(PERIOD_M1*period);

        //************moving averageEMA****************
        let emaChart8 = TA.EMA(r, EMA1);
        let emaChart34 = TA.EMA(r, EMA2);
        let emaChart89 = TA.EMA(r, EMA3);

        let ema8 = emaChart8;
        let curEma8 = ema8[emaChart8.length - 1];
        let lastEma8 = ema8[emaChart8.length - 2];

        let ema34 = emaChart34;
        let curEma34 = ema34[emaChart34.length - 1];
        let lastEma34 = ema34[emaChart34.length - 2];

        let ema89 = emaChart89;
        let curEma89 = ema89[emaChart89.length - 1];
        let lastEma89 = ema89[emaChart89.length - 2];

        //Judgment8Average sum34The death cross and golden cross of moving averages; when a golden cross occurs, if the current bar is onema89Go long above moving average; when death cross occurs, if the body is onema89Short when below
        let ticker = exchange.GetTicker();
        let low = ticker.Low;
        let high = ticker.High;
        let close = ticker.Close;

        Close(ticker,curEma8,curEma34);

        let crossStatus1 = GetCrossStatus(curEma8, lastEma8, curEma34, lastEma34);

        if (crossStatus1 != emaMeet) { //Update status when status changes
            if (crossStatus1 == 1) {
                emaMeet = 1;
                Log("emaGolden cross, time:", GetCurTime(r),talib.LINEARREG_SLOPE(ema8));
                lastEmaCrossTime = r[r.length - 1].Time;
            }
            if (crossStatus1 == 2) {
                emaMeet = 2;
                //Log("emaDeath cross, time:", GetCurTime(r));
                lastEmaCrossTime = r[r.length - 1].Time;
                //Log("Ema 2");
            }
        }

        //***************Macd*************
        let macdChart = TA.MACD(r, MACD1, MACD2, MACD3);

        let macd = macdChart[2]; //Kinetic energy column
        let curMacd = macd[r.length - 1]; //Current momentum bar
        let lastMacd = macd[r.length - 2]; //the previous momentum bar, directly judge based on the polarity of the momentum barmacdGolden cross and death cross of
        //auto lastMacd = macd[r.size() - 2]; //Previous momentum bar

        //Determine golden cross or death cross
        let dif = macdChart[0];
        let curDif = dif[r.length - 1];
        let lastDif = dif[r.length - 2];


        //Determine golden cross or death cross,Simultaneously determine if it is greater at the moment0Axis or less than0axis,Because in this system it requires a golden cross whenmacd>0Only then does it make sense; during a death crossmacd<0makes sense

        //MacdThe moment when a golden cross or a death cross is formed
        if (curMacd < 0 != lastMacd < 0) {

            if (curMacd > 0) {
                macdMeet = 1;
                //Log("macdgolden cross", lastMacd, curMacd);
                lastMacdCrossTime = GetCurTime(r);
            }
            if (curMacd < 0) {
                macdMeet = 2;
                //Log("macddeath cross", lastMacd, curMacd);
                lastMacdCrossTime = GetCurTime(r);

            }
        }


        let Account = exchange.GetAccount();
        let curBalance = exchange.GetAccount().Balance; //Balance
        let curStock = exchange.GetAccount().Stocks; //Coin amount

        //Moving average system
        var curTime = GetCurTime(r);

        if (NearEmaCross(curTime) && NearMacdCross(curTime)) {

            if (emaMeet == 1 && macdMeet == 1 && curDif >= 0) {
                Open(1);
            }

            if (emaMeet == 2 && macdMeet == 2 && curDif < 0) {
                Open(2);
            }
        }


        var myDate = new Date();
        var myDataM = myDate.getMinutes();
        var myDateS = myDate.getSeconds() * 1000;
        var myDateMs = myDate.getMilliseconds(); //Get milliseconds to reduce error
        Sleep(Math.abs(period - myDataM % period) * 60000 - myDateS - myDateMs);


    }


}Published by Exodus[策略代写] on the FMZ strategy square · last modified 2021-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Three-Moving-Average-System-Exodus.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.