Strategy vault / Tools & templates
Time stepped Pyramiding Simple Quant Strategy
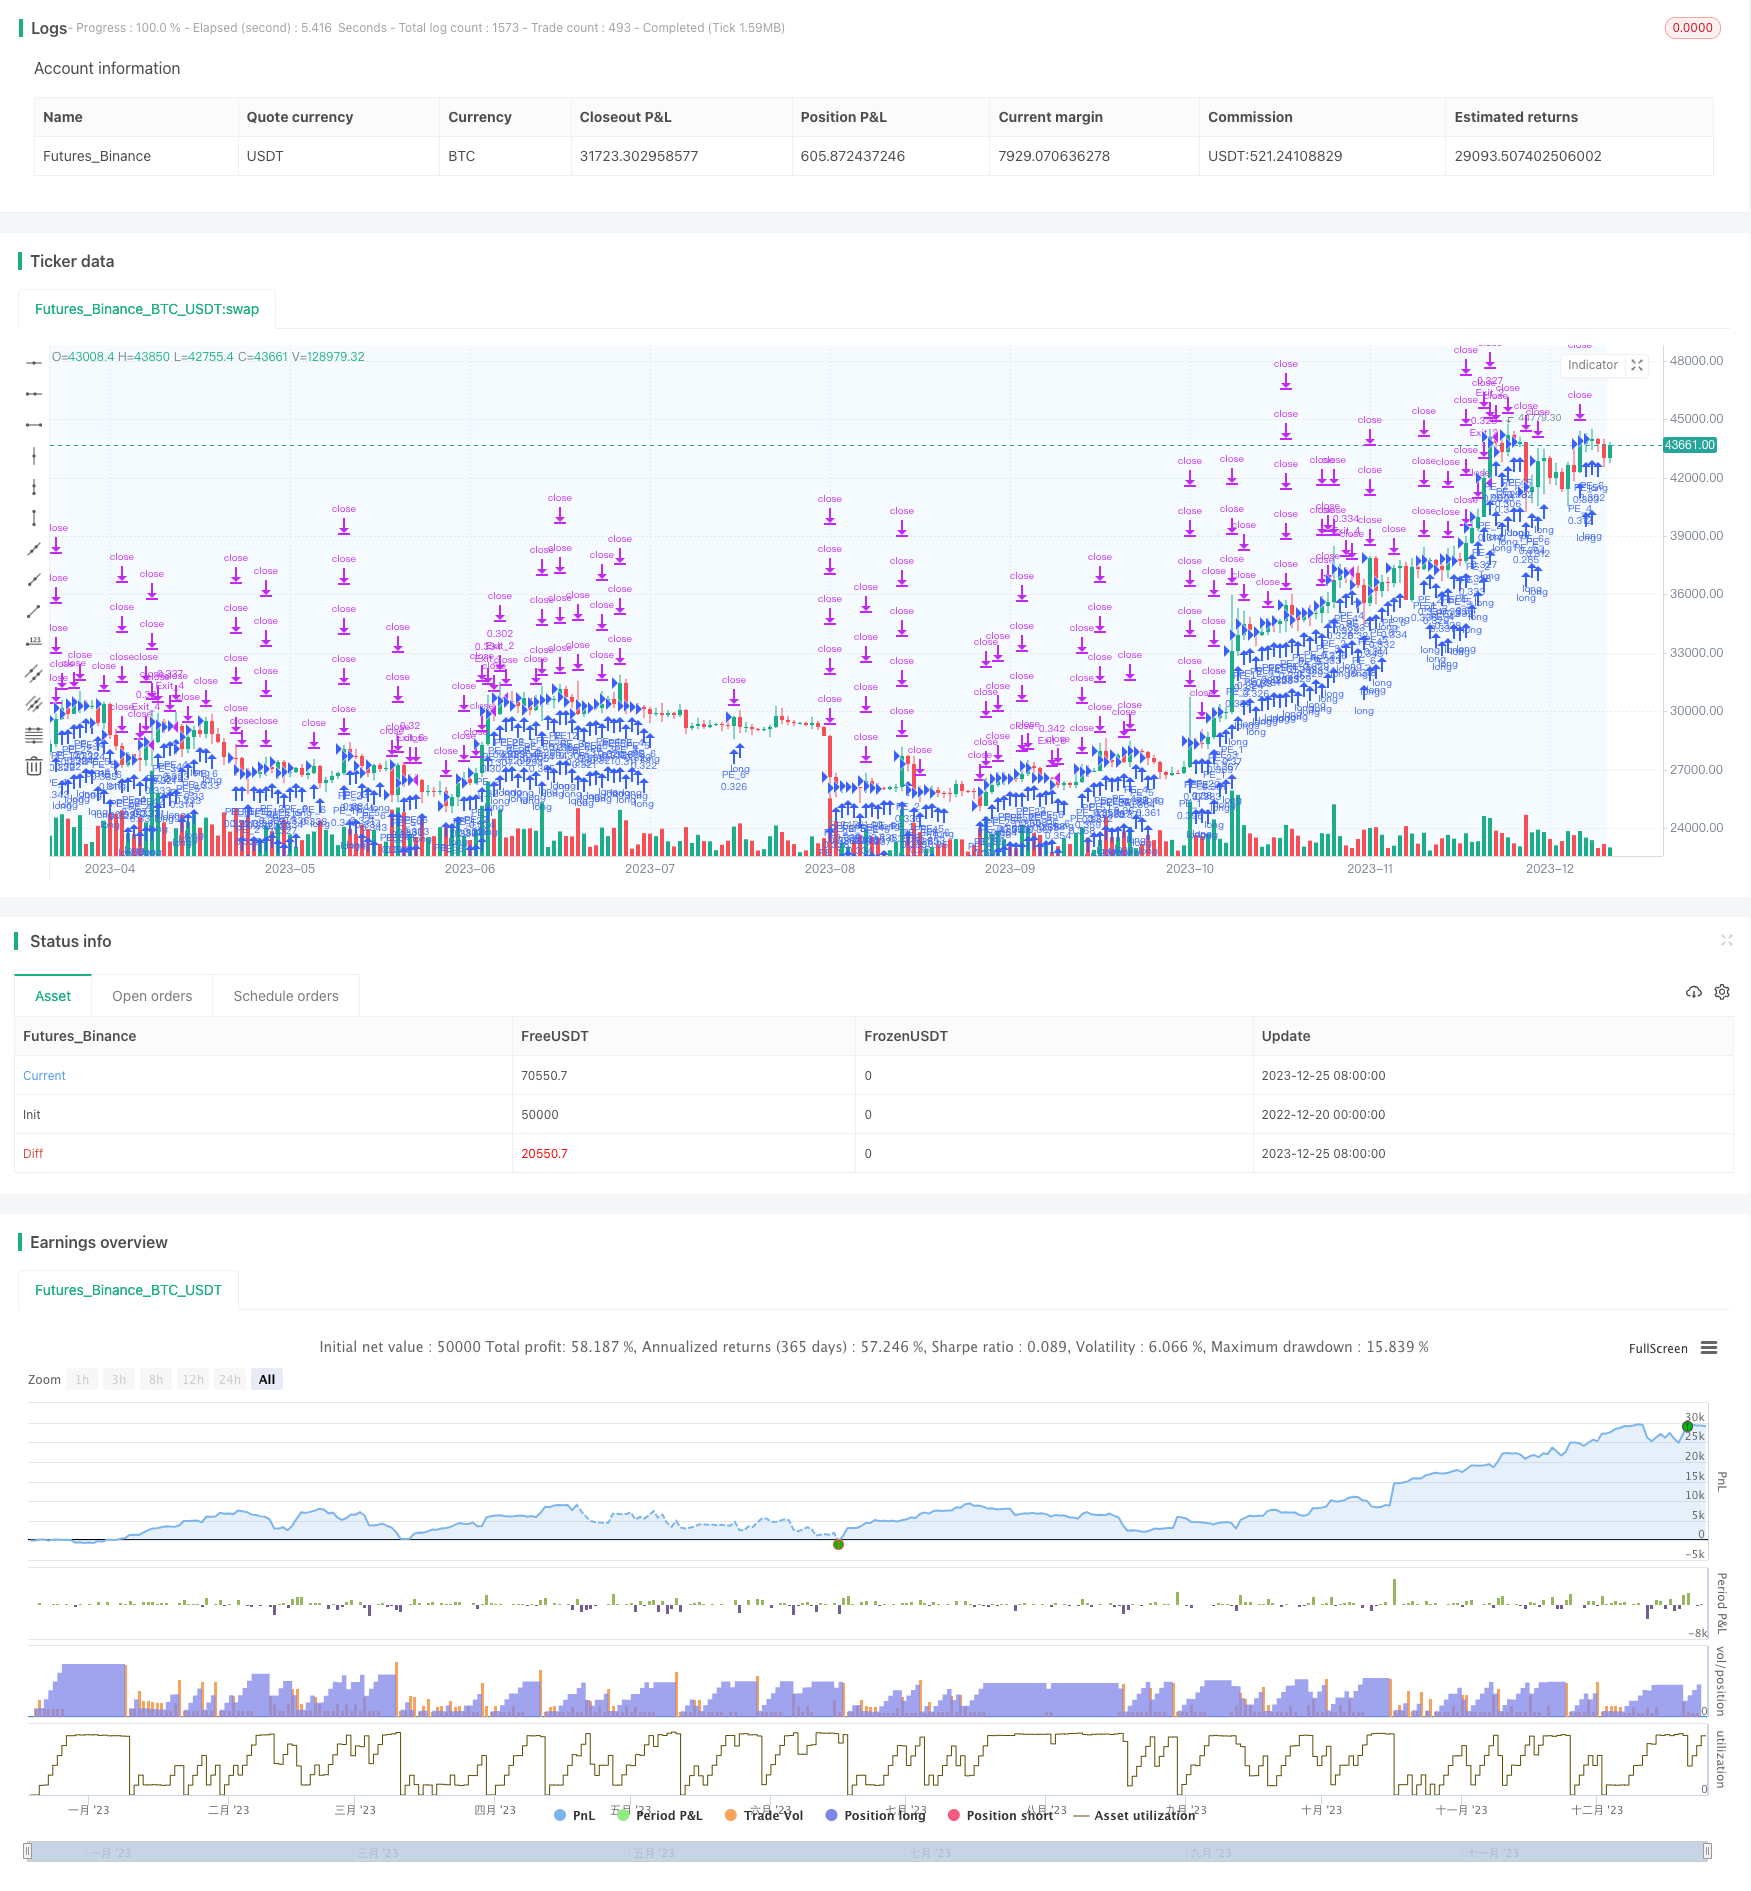
This strategy is a simple quant trading strategy that utilizes time-stepped pyramiding. The main idea is to long open positions every day at fixed times, and set different take profit and stop loss levels for each…
Overview
This strategy is a simple quant trading strategy that utilizes time-stepped pyramiding. The main idea is to long open positions every day at fixed times, and set different take profit and stop loss levels for each position to realize batched profit taking and stopping loss.
Principles
The strategy is based on three key logics:
Time-stepped pyramiding
Use the
sessionTimeparameter to set a daily trading time window, pyramid long positions step by step at market open during this window. The position size is the average allocation of the maximum capital.Individualized profit taking and stopping loss
Set corresponding take profit level
takeProfitand stop loss levelstopLossfor every opened position, so that each position has its own profit taking and stopping loss logic to realize batch executions.Close all positions when time window ends
Choose whether to close all positions opened during the time window at the end of the window.
Advantages
The strategy has the following advantages:
Risk diversification. Allocate capital evenly to different positions to effectively control single position loss.
Batch profit taking and stopping loss. Different positions have independent logics to avoid mass stopping loss.
Flexible configurations. Customizable parameters like maximum pyramiding times, daily time window, profit taking/stopping loss ratios etc.
Simple and clear logic. Easy to understand.
Risks
There are also some risks:
Risk of full capital stuck if all positions trigger stop loss before take profit. Can be avoided by reasonably configuring the stop loss ratio.
No limit on total open position capital per day. Too many positions may exceed capital bearability if encountering unusual market situations. Consider adding maximal total position capital per day.
Improper time window configuration may miss trading chances. Suggest to refer to the active trading time window of the trading assets.
Enhancement
The strategy can be enhanced from the following aspects:
Add open position conditions based on technical indicators to avoid reckless pyramiding.
Add daily total open position capital limit to prevent exceeding capital bearability.
Set different take profit/stop loss ratios for different positions to realize differentiated profit taking and stopping loss.
Add logics to link position amount with capital pool balance.
Conclusion
In conclusion, this is a very simple quant trading strategy template utilizing the time-stepped pyramiding methodology. The logic is simple and clear while there are also some risks and rooms for enhancement. Developers can optimize it properly to make it a relatively stable and reliable quant strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | timestamp(01 April 2021 20:00) | (?Backtest Window)Start Time |
| v_input_2 | timestamp(01 Aug 2022 20:00) | End Time |
| v_input_int_1 | 6 | (?Risk)Max Amount of DCA Entries |
| v_input_float_1 | 2.5 | Take Profit % |
| v_input_bool_1 | true | Activate Stop Loss |
| v_input_float_2 | 9 | Stop Loss % |
| v_input_3 | 1800-1700 | (?DCA Settings)DCA Order Timeframe |
| v_input_bool_2 | false | Exit DCA Entry at end of Timeframe |
Source Pine Script
/*backtest
start: 2022-12-20 00:00:00
end: 2023-12-26 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © A3Sh

//@version=5
strategy("Simple_Pyramiding", overlay=true, pyramiding=99, initial_capital=500, default_qty_type=strategy.percent_of_equity, commission_type=strategy.commission.percent, commission_value=0.075, close_entries_rule='FIFO')

// Study of a Simple DCA strategy that opens a position every day at a specified time.
// A position is opened at the start time of the Timeframe.
// Positions exit individually when the take profit level is triggered.
// Option to activate Stop Loss and/or Position exit at the end of the Timeframe


// Backtest Window
start_time   = input(defval=timestamp("01 April 2021 20:00"), group = "Backtest Window", title="Start Time")
end_time     = input(defval=timestamp("01 Aug 2022 20:00"),  group = "Backtest Window", title="End Time")
window() => true


// Inputs
posCount     = input.int    (6,           group = "Risk",         title = "Max Amount of DCA Entries")
takeProfit   = input.float  (2.5,         group = "Risk",         title = "Take Profit %")
slSwitch     = input.bool   (true,        group = "Risk",         title = "Activate Stop Loss")
stopLoss     = input.float  (9,           group = "Risk",         title = "Stop Loss %")
sessionTime =  input("1800-1700", group = "DCA Settings", title = "DCA Order Timeframe", tooltip="Open order at the start/If ativated, close order at the end")
exitDCA     =  input.bool   (false,       group = "DCA Settings", title = "Exit DCA Entry at end of Timeframe")


// Order size based on max amount of pyramid orders
q = (strategy.equity  / posCount) / open


// Timeframe for opening and closing a DCA order
// example taken from https://stackoverflow.com/questions/69230164/pinescript-basic-question-open-a-trade-at-a-set-time-each-day
t       = time("D", sessionTime)
isStart = na(t[1]) and not na(t) or t[1] < t
isEnd   = na(t) and not na(t[1]) or t[1] < t
bgcolor(t ? color.new(color.blue,95) : na, title = " TimeFrame Color")


// Create DCA Entries
entry_price = 0.0
if isStart and window()
    for i = 0 to strategy.opentrades
        if strategy.opentrades == i
            entry_price := close
            entry_id = "PE_" + str.tostring(i + 1)
            strategy.entry(id = entry_id, direction=strategy.long, limit=entry_price, qty=q)
        if strategy.opentrades == posCount
            break


//Exit DCA Entries when take profit or stop loss is triggered
if strategy.opentrades > 0 and window()
    for i = 0 to strategy.opentrades
        exit_from = "PE_" + str.tostring(i + 1)
        exit_id = "Exit_" + str.tostring(i + 1)
        strategy.exit(id= exit_id, from_entry= exit_from, profit = close * takeProfit / 100 / syminfo.mintick, loss = slSwitch ? close * stopLoss /100 / syminfo.mintick :na)


//Exit DCA Entries at end of DCA Timeframe
if strategy.opentrades > 0 and exitDCA and isEnd and window()
    for i = 0 to strategy.opentrades
        exit_from = "PE_" + str.tostring(i + 1)
        exit_id = "Exit_" + str.tostring(i + 1)
        strategy.exit(id= exit_id, from_entry= exit_from, stop = close)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a tested, production-ready module from strategies/Time-stepped-Pyramiding-Simple-Quant-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- CSO Custom Signal Oscillator Strategy CSOPine Script · Tools & templates · 2h
- Mechanical Trading StrategyPine Script · Tools & templates · 4h
- Multi Indicator Configurable Strategy GeneratorPine Script · Tools & templates · 5m
- MA MACD BB Multi Indicator Trading Strategy Backtesting ToolPine Script · Tools & templates · 1d
- ML Alerts TemplatePine Script · Tools & templates · 2h
- Monthly Returns Strategy with BenchmarkPine Script · Tools & templates · 2h