Trend Following RSI Scalping Strategy
According to technical analysis, an RSI above 70 should signal overbought conditions and thus a sell signal. Cryptocurrencies represent an entirely new asset class that is reshaping concepts of technical analysis…
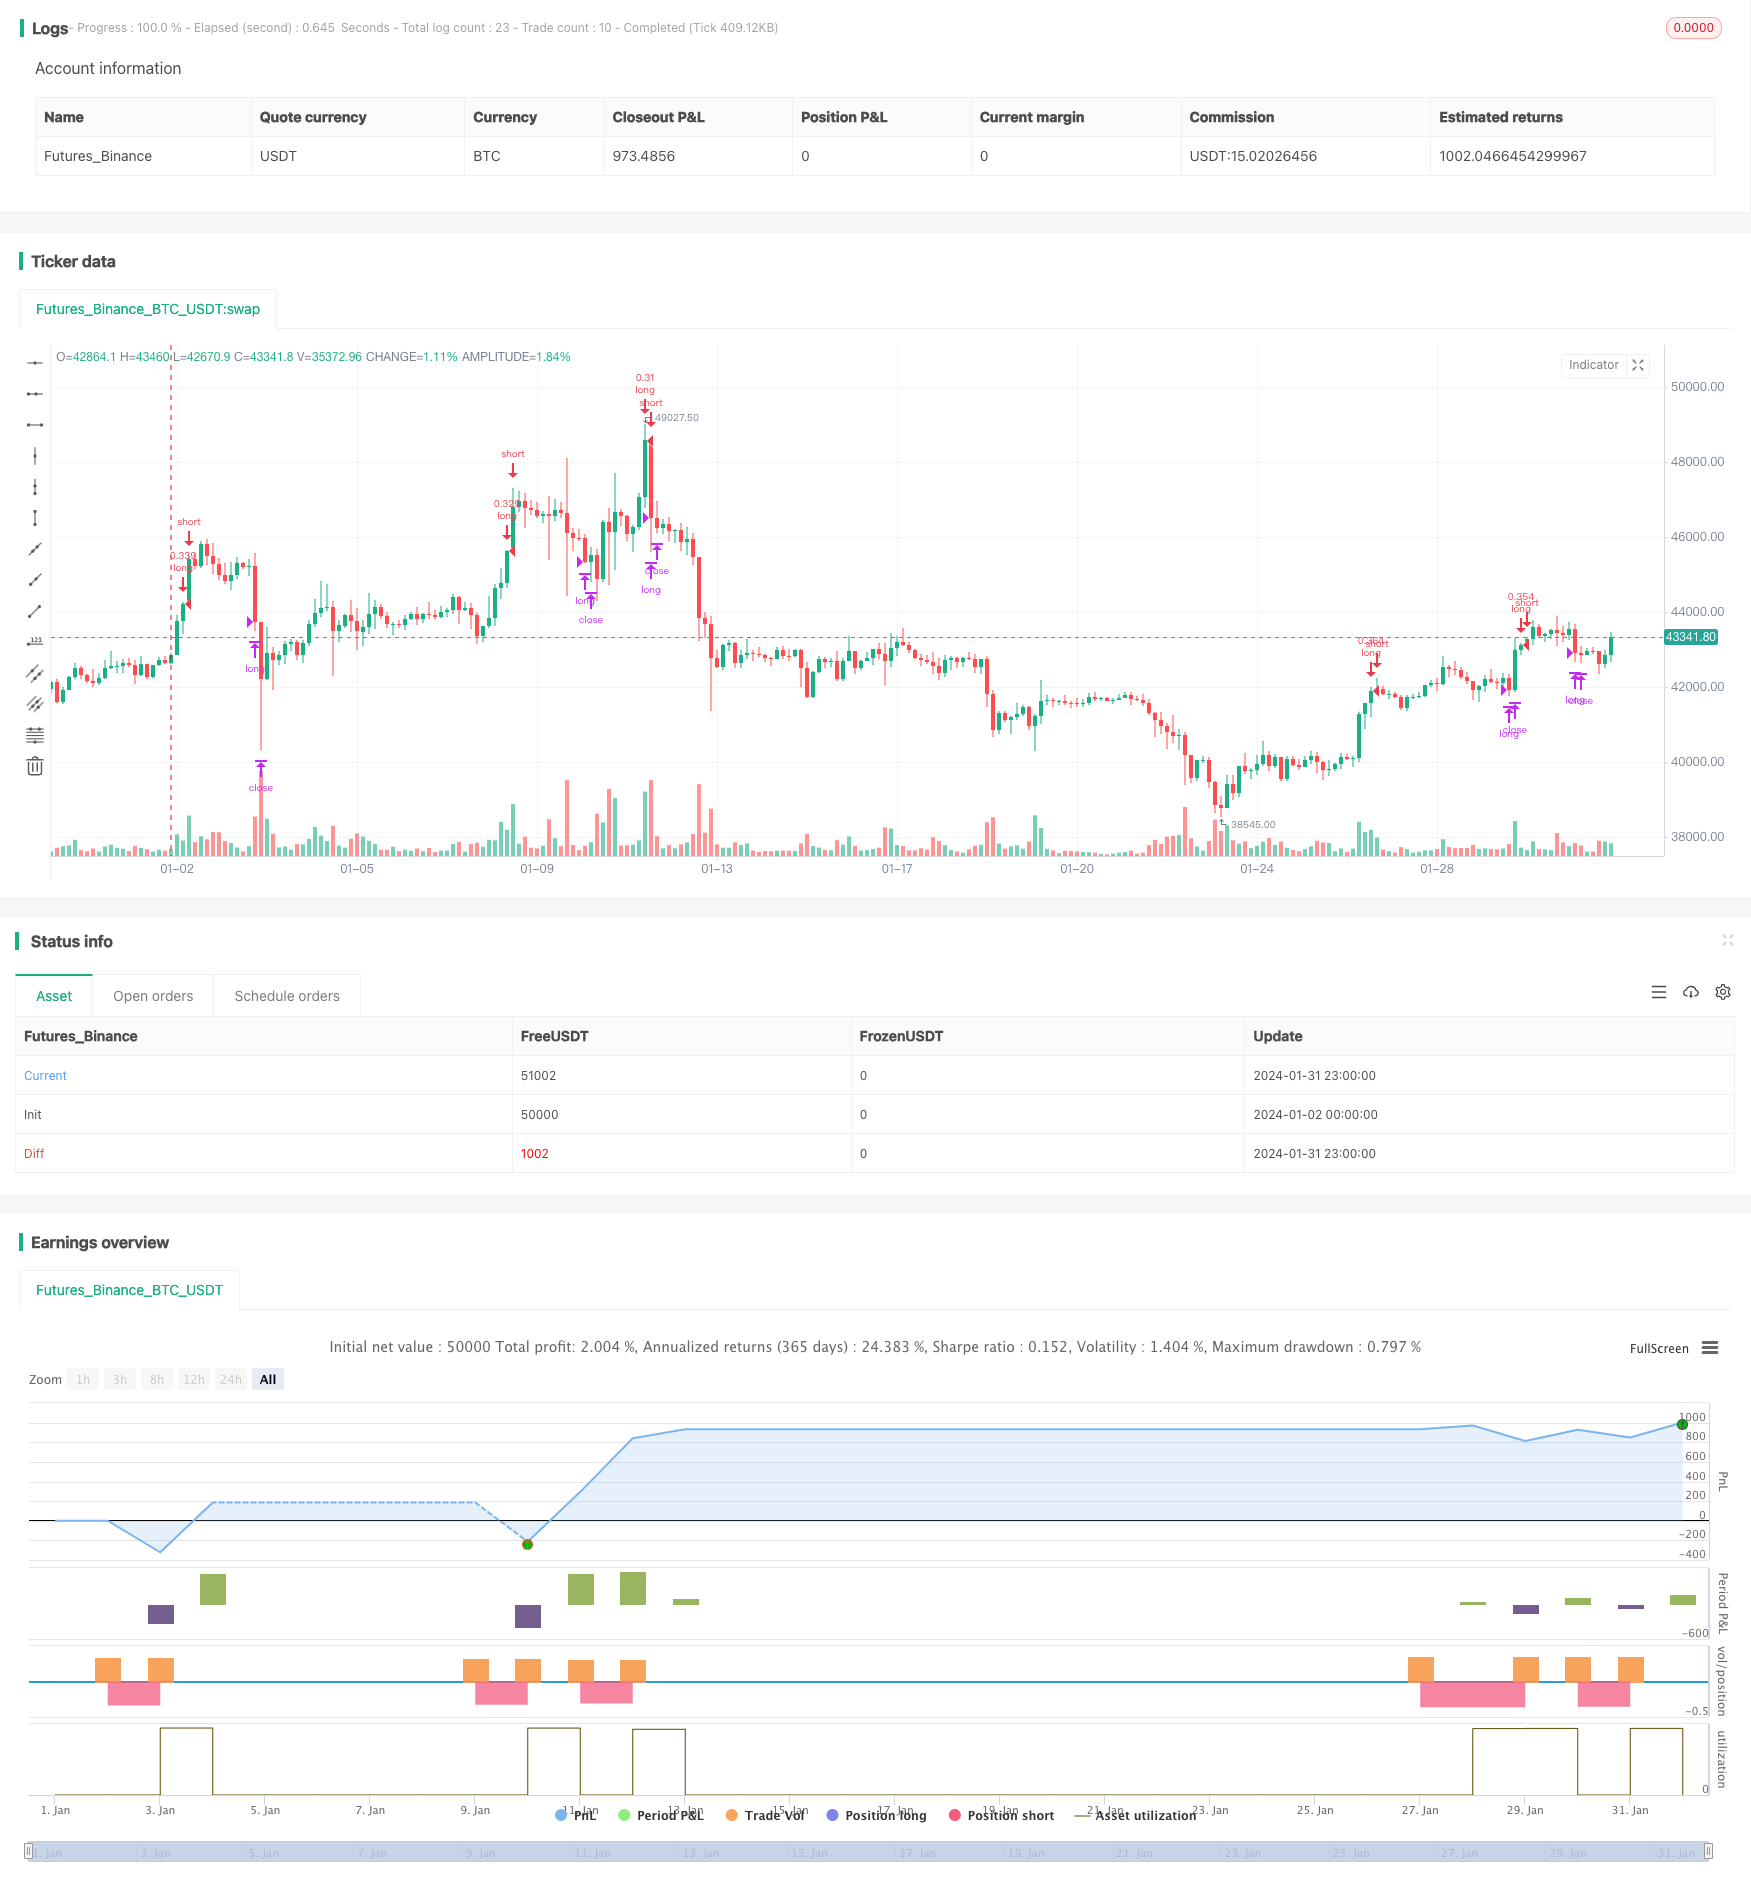
Overview
According to technical analysis, an RSI above 70 should signal overbought conditions and thus a sell signal. Cryptocurrencies represent an entirely new asset class that is reshaping concepts of technical analysis. FOMO buying can be very powerful, and coins can remain in overbought territory long enough to provide excellent scalping opportunities on the upside.
Building a trend-following trading strategy based on the RSI, which is generally considered a contrarian indicator, may sound counterintuitive. However, over 200 backtests prove this is a very interesting long-term setup.
Strategy Logic
The strategy assumes each order to trade 30% of the available capital. A trading fee of 0.1% is taken into account, aligned with the base fee applied on Binance, the world's largest cryptocurrency exchange.
- Entry Signal: Go long when RSI goes above 70 and within backtest window
- Exit Signal: Close long position when RSI drops below 55 or close goes above take profit
Advantage Analysis
- Identify trends using RSI, avoiding missing signals in ranging markets
- Fixed position sizing manages single trade risk
- Suitable for mid-to-long term holds, avoiding shakeouts from short-term fluctuations
Risk Analysis
- Ensure RSI parameters are set reasonably, otherwise overbought/oversold errors occur
- Tracking take profit requires timely updates, otherwise profits are left on the table
- Monitor risk from exceptional market volatility, adjust position sizing or stop losses if necessary
Optimization Directions
- Consider combining other indicators like MACD to confirm trend
- Test different RSI parameter settings
- Introduce dynamic take profit based on market volatility
Conclusion
This strategy identifies overbought conditions with RSI to determine trend direction and takes progressive profits trailing the uptrend. Compared to traditional RSI contrarian usage, this strategy offers a new perspective. Rigorous backtesting shows promising results, but we need to monitor risks and optimize parameters. Overall, it provides a simple, practical trend following approach for quantitative trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | From Month |
| v_input_2 | 10 | From Day |
| v_input_3 | 2020 | From Year |
| v_input_4 | true | Thru Month |
| v_input_5 | true | Thru Day |
| v_input_6 | 2112 | Thru Year |
| v_input_7 | true | Show Date Range |
| v_input_8 | 14 | RSI period |
| v_input_9 | 6 | v_input_9 |
Source Pine Script
/*backtest
start: 2024-01-02 00:00:00
end: 2024-02-01 00:00:00
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=1
strategy(shorttitle='Trend-following RSI Scalping Strategy (by Coinrule)',title='Trend-following RSI Strategy ', overlay=true, initial_capital = 1000, default_qty_type = strategy.percent_of_equity, default_qty_type = strategy.percent_of_equity, default_qty_value = 30, commission_type=strategy.commission.percent, commission_value=0.1)

//Backtest dates
fromMonth = input(defval = 1,  title = "From Month")
fromDay   = input(defval = 10,    title = "From Day")
fromYear  = input(defval = 2020, title = "From Year")
thruMonth = input(defval = 1,    title = "Thru Month")
thruDay   = input(defval = 1,    title = "Thru Day")
thruYear  = input(defval = 2112, title = "Thru Year")

showDate  = input(defval = true, title = "Show Date Range")

start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)        // backtest start window
finish    = timestamp(thruYear, thruMonth, thruDay, 23, 59)        // backtest finish window
window()  => true


// RSI inputs and calculations
lengthRSI = input(14, title = 'RSI period', minval=1)
RSI = rsi(close, lengthRSI)

//Entry


strategy.entry(id="long", long = true, when = RSI > 70 and window())

//Exit

Take_profit= ((input (6))/100)
longTakeProfit = strategy.position_avg_price * (1 + Take_profit)

strategy.close("long", when = RSI < 55 or close > longTakeProfit and window())
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-RSI-Scalping-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Moving Average Crossover Scalping StrategyPine Script · Scalping · 1h
- EMA MACD Composite Strategy for Trend ScalpingPine Script · Scalping · 1d
- Multi Indicator Synergistic Dynamic Risk Management Scalping Strategy EMAMACDRSI with ATR Adaptive Stop Loss Take Profit TechniquePine Script · Scalping · 2d
- Vitalik ScalpePine Script · Scalping
- 20Bitcoin and Gold 5 Minute Scalping Strategy 20Pine Script · Scalping · 1h
- Scalping EMA ADX RSI with Buy SellPine Script · Scalping · 5m