Strategy vault / Trend following
Trend Following Strategy Based on Dynamic Stop Loss of Dual EMA Crossover
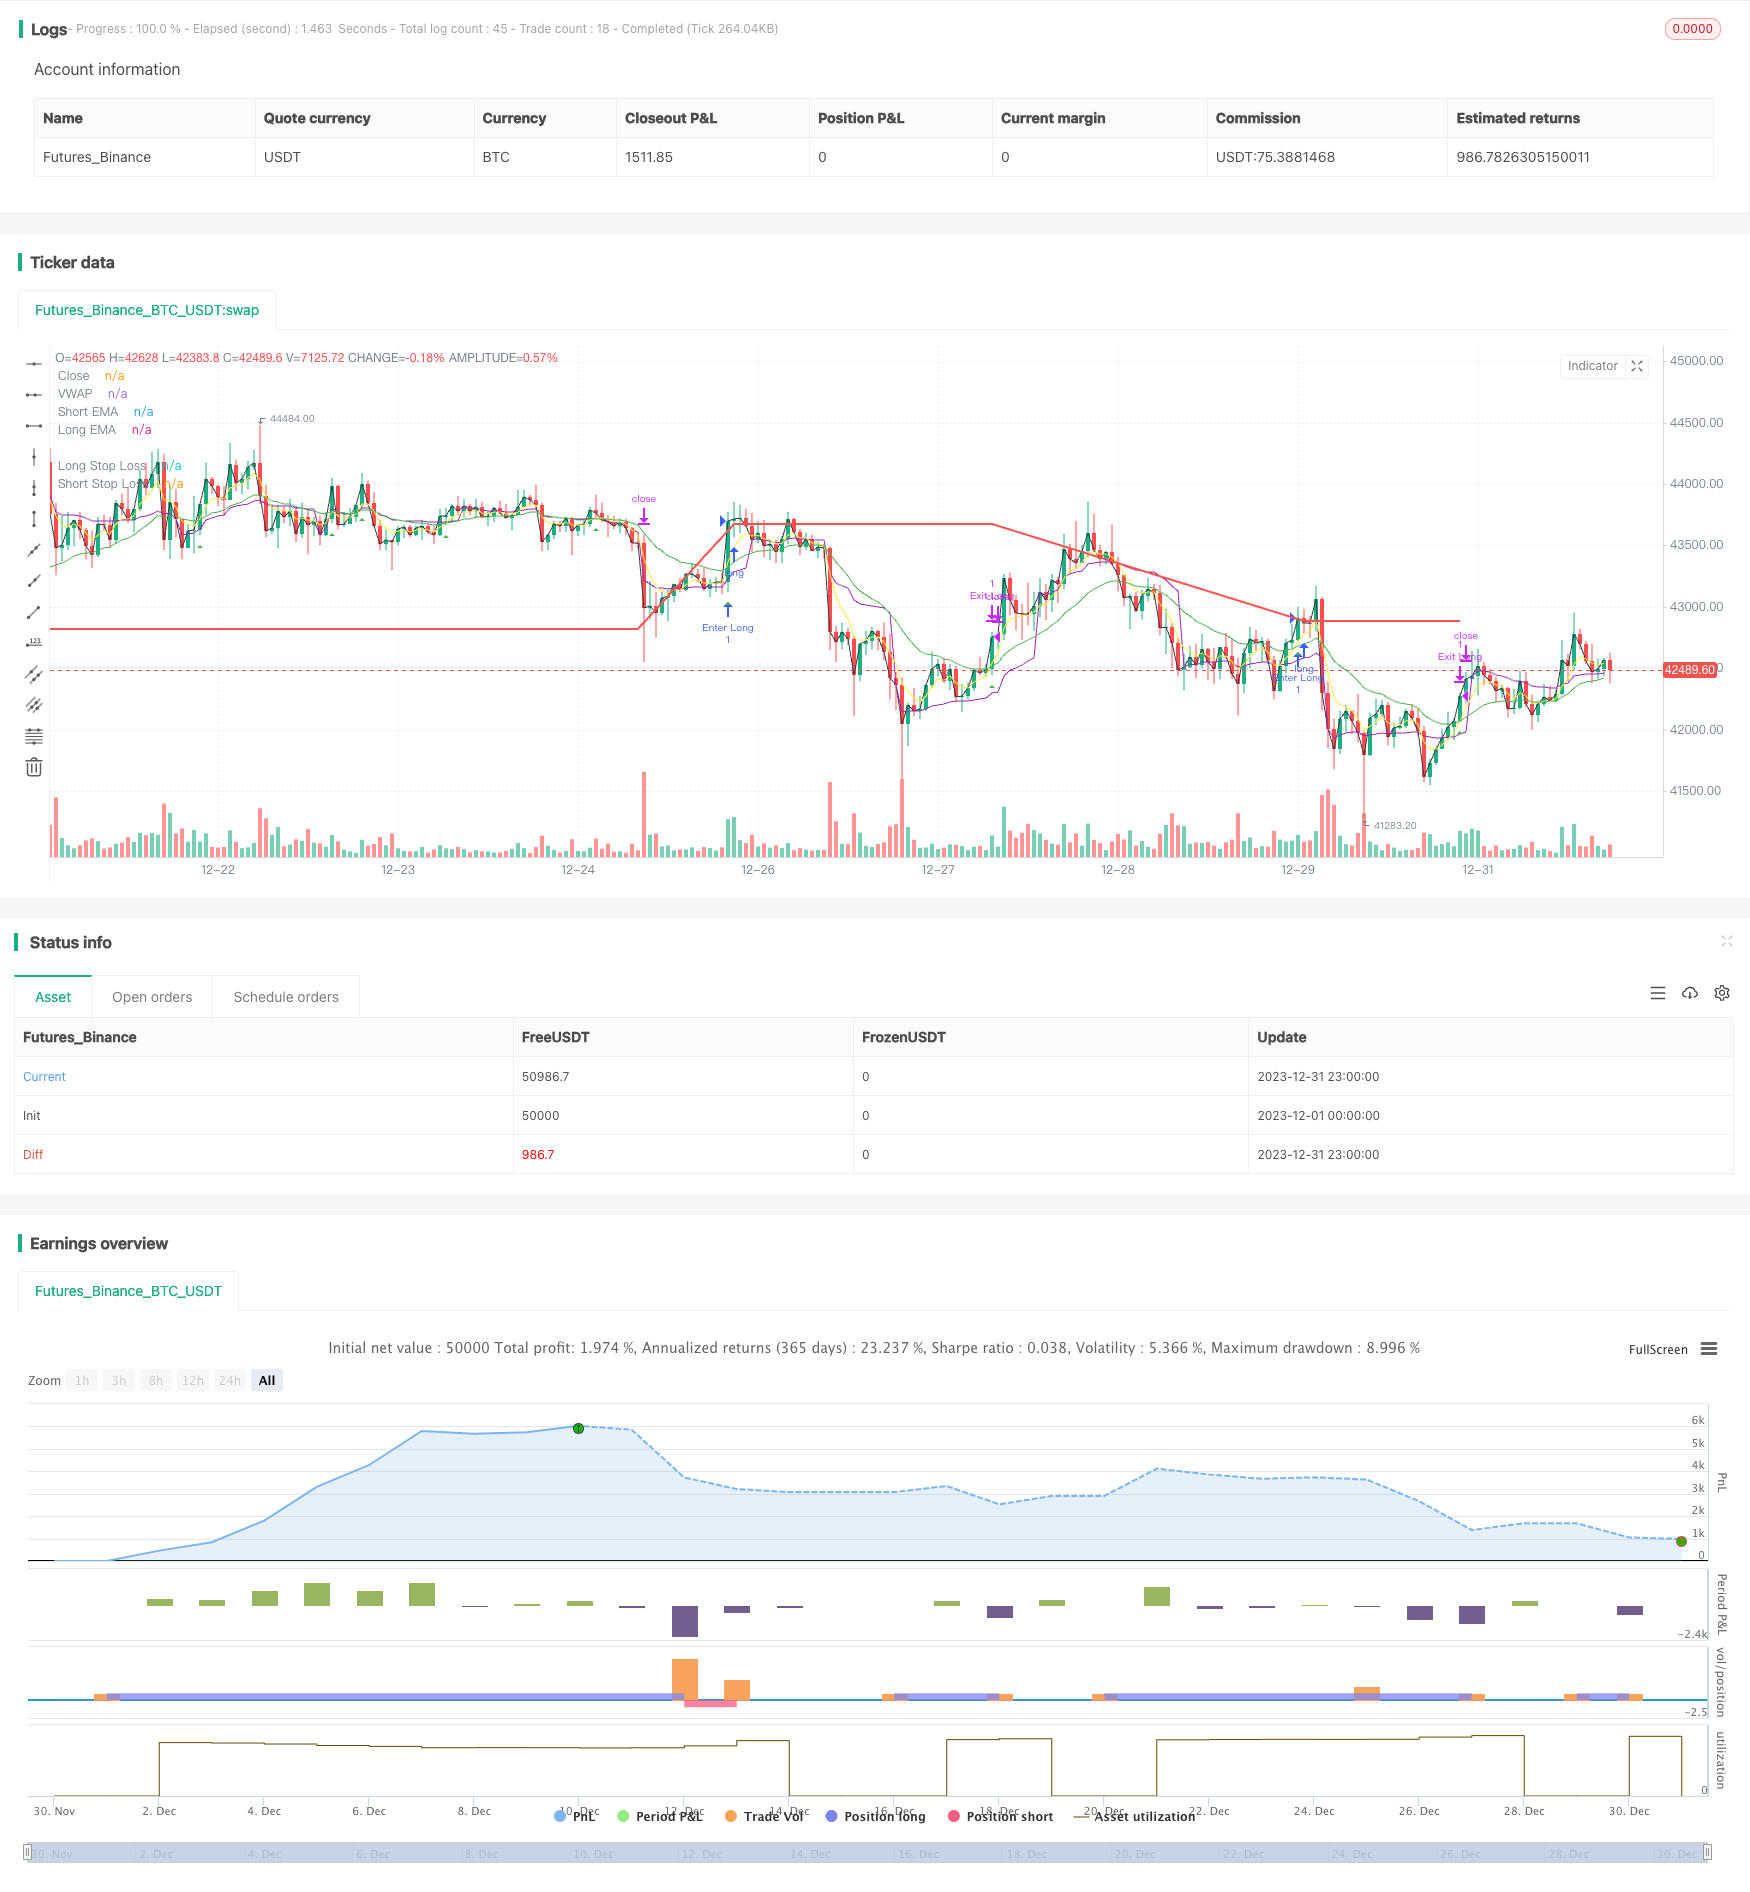
This strategy utilizes the golden cross and dead cross of EMA lines for dual-directional trend following, and sets up dynamic stop loss lines for long and short positions to capture trending moves in the market.
Overview
This strategy utilizes the golden cross and dead cross of EMA lines for dual-directional trend following, and sets up dynamic stop loss lines for long and short positions to capture trending moves in the market.
Strategy Logic
- Calculate fast EMA line (5-day) and slow EMA line (20-day)
- Go long when fast line crosses above slow line from below; Go short when fast line crosses below slow line from above
- After long entry, set dynamic stop loss at entry price * (1 - long stop loss percentage); After short entry, set dynamic stop loss at entry price * (1 + short stop loss percentage)
- Exit position with stop loss once price hits the stop loss level
Advantage Analysis
- EMA lines have stronger capabilities in tracking trends. Dual-crossover works as a timing tool to effectively catch trend opportunities
- Dynamic stop loss moves along with profit, maximizing trend catching profit
- Additional filter with vwap avoids being trapped in whipsaws and improves signal quality
Risk Analysis
- As a pure trend following strategy, it's vulnerable to ranging markets with whipsaws
- Overly loose stop loss may lead to magnified losses
- Lagging nature of EMA crossover signals may miss best entry points
Enhancements like ATR-based risk management, optimizing stop loss rules, adding filter indicators etc. can help improve the strategy.
Enhancement Directions
- Incorporate dynamic stop loss indicators like ATR or DONCH to set better adaptive stops
- Add more filter indicators like MACD, KDJ to avoid bad trades
- Optimize parameters to find best EMA lengths combination
- Utilize machine learning methods to discover optimal parameters
Conclusion
In conclusion, this is a very typical trend following strategy. Dual EMA crossover with dynamic stop loss can effectively lock in trend profits. Meanwhile the risks like lagging signals and overwide stops still exist. Through parameter tuning, risk management, filter additions etc., further refinement can lead to better results.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 5 | Short EMA Length |
| v_input_2 | 20 | Long EMA Length |
| v_input_3 | true | Price EMA Length |
| v_input_float_1 | 0.05 | Long Stop Loss (%) |
| v_input_float_2 | 0.05 | Short Stop Loss (%) |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5

strategy("EMA Crossover Strategy", shorttitle="EMAC", overlay=true,calc_on_every_tick=true)

// Input parameters
shortEmaLength = input(5, title="Short EMA Length")
longEmaLength = input(20, title="Long EMA Length")
priceEmaLength = input(1, title="Price EMA Length")

// Set stop loss level with input options (optional)
longLossPerc = input.float(0.05, title="Long Stop Loss (%)",
     minval=0.0, step=0.1) * 0.01

shortLossPerc = input.float(0.05, title="Short Stop Loss (%)",
     minval=0.0, step=0.1) * 0.01

// Calculating indicators
shortEma = ta.ema(close, shortEmaLength)
longEma = ta.ema(close, longEmaLength)
//priceEma = ta.ema(close, priceEmaLength)
vwap = ta.vwap(close)

// Long entry conditions
longCondition = ta.crossover(shortEma, longEma) and close > vwap
// Short entry conditions
shortCondition = ta.crossunder(shortEma, longEma) and close > vwap

// STEP 2:
// Determine stop loss price
longStopPrice  = strategy.position_avg_price * (1 - longLossPerc)
shortStopPrice = strategy.position_avg_price * (1 + shortLossPerc)


if (longCondition)
    strategy.entry("Enter Long", strategy.long)
    strategy.exit("Exit Long",from_entry = "Enter Long",stop= longStopPrice)
plotshape(series=longCondition, title="Long Signal", color=color.green, style=shape.triangleup, location=location.belowbar)


if (shortCondition)
    strategy.entry("Enter Short", strategy.short)
    strategy.exit("Exit Short", from_entry = "Enter Short",stop = shortStopPrice)
plotshape(series=shortCondition, title="Short Signal", color=color.red, style=shape.triangledown, location=location.abovebar)

// Stop loss levels
//longStopLoss = (1 - stopLossPercent) * close
//shortStopLoss = (1 + stopLossPercent) * close

// Exit conditions
//strategy.exit("Long", from_entry="Long", loss=longStopLoss)
//strategy.exit("Short", from_entry="Short", loss=shortStopLoss)

// Plotting indicators on the chart
plot(shortEma, color=color.yellow, title="Short EMA")
plot(longEma, color=color.green, title="Long EMA")
plot(close, color=color.black, title="Close")
plot(vwap, color=color.purple, title="VWAP")

// Plot stop loss values for confirmation
plot(strategy.position_size > 0 ? longStopPrice : na,
     color=color.red, style=plot.style_line,
     linewidth=2, title="Long Stop Loss")

plot(strategy.position_size < 0 ? shortStopPrice : na,
     color=color.blue, style=plot.style_line,
     linewidth=2, title="Short Stop Loss")
// Plotting stop loss lines
//plot(longStopLoss, color=color.red, title="Long Stop Loss", linewidth=2, style=plot.style_line)
//plot(shortStopLoss, color=color.aqua, title="Short Stop Loss", linewidth=2, style=plot.style_line)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Strategy-Based-on-Dynamic-Stop-Loss-of-Dual-EMA-Crossover.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Trend Following Strategy Based on Moving Average 439858Pine Script · Trend following · 1d
- Multi Timeframe Volume and Trend Confluence Trading StrategyPine Script · Trend following · 1d
- Intelligent Multi Dimensional Adaptive Trend Trading SystemPine Script · Trend following · 1h
- Trend Confirmation Tracking StrategyPine Script · Trend following · 1h
- Indicator Verification Automated Trading StrategyPine Script · Trend following · 10m