Strategy vault / Trend following
Trend Following Strategy Based on Moving Average 435962
This strategy uses Mark Minervini's stock selection template and moving average indicators to determine price trends for automated entry and stop-loss. It mainly judges whether stock prices are in an uptrend and…
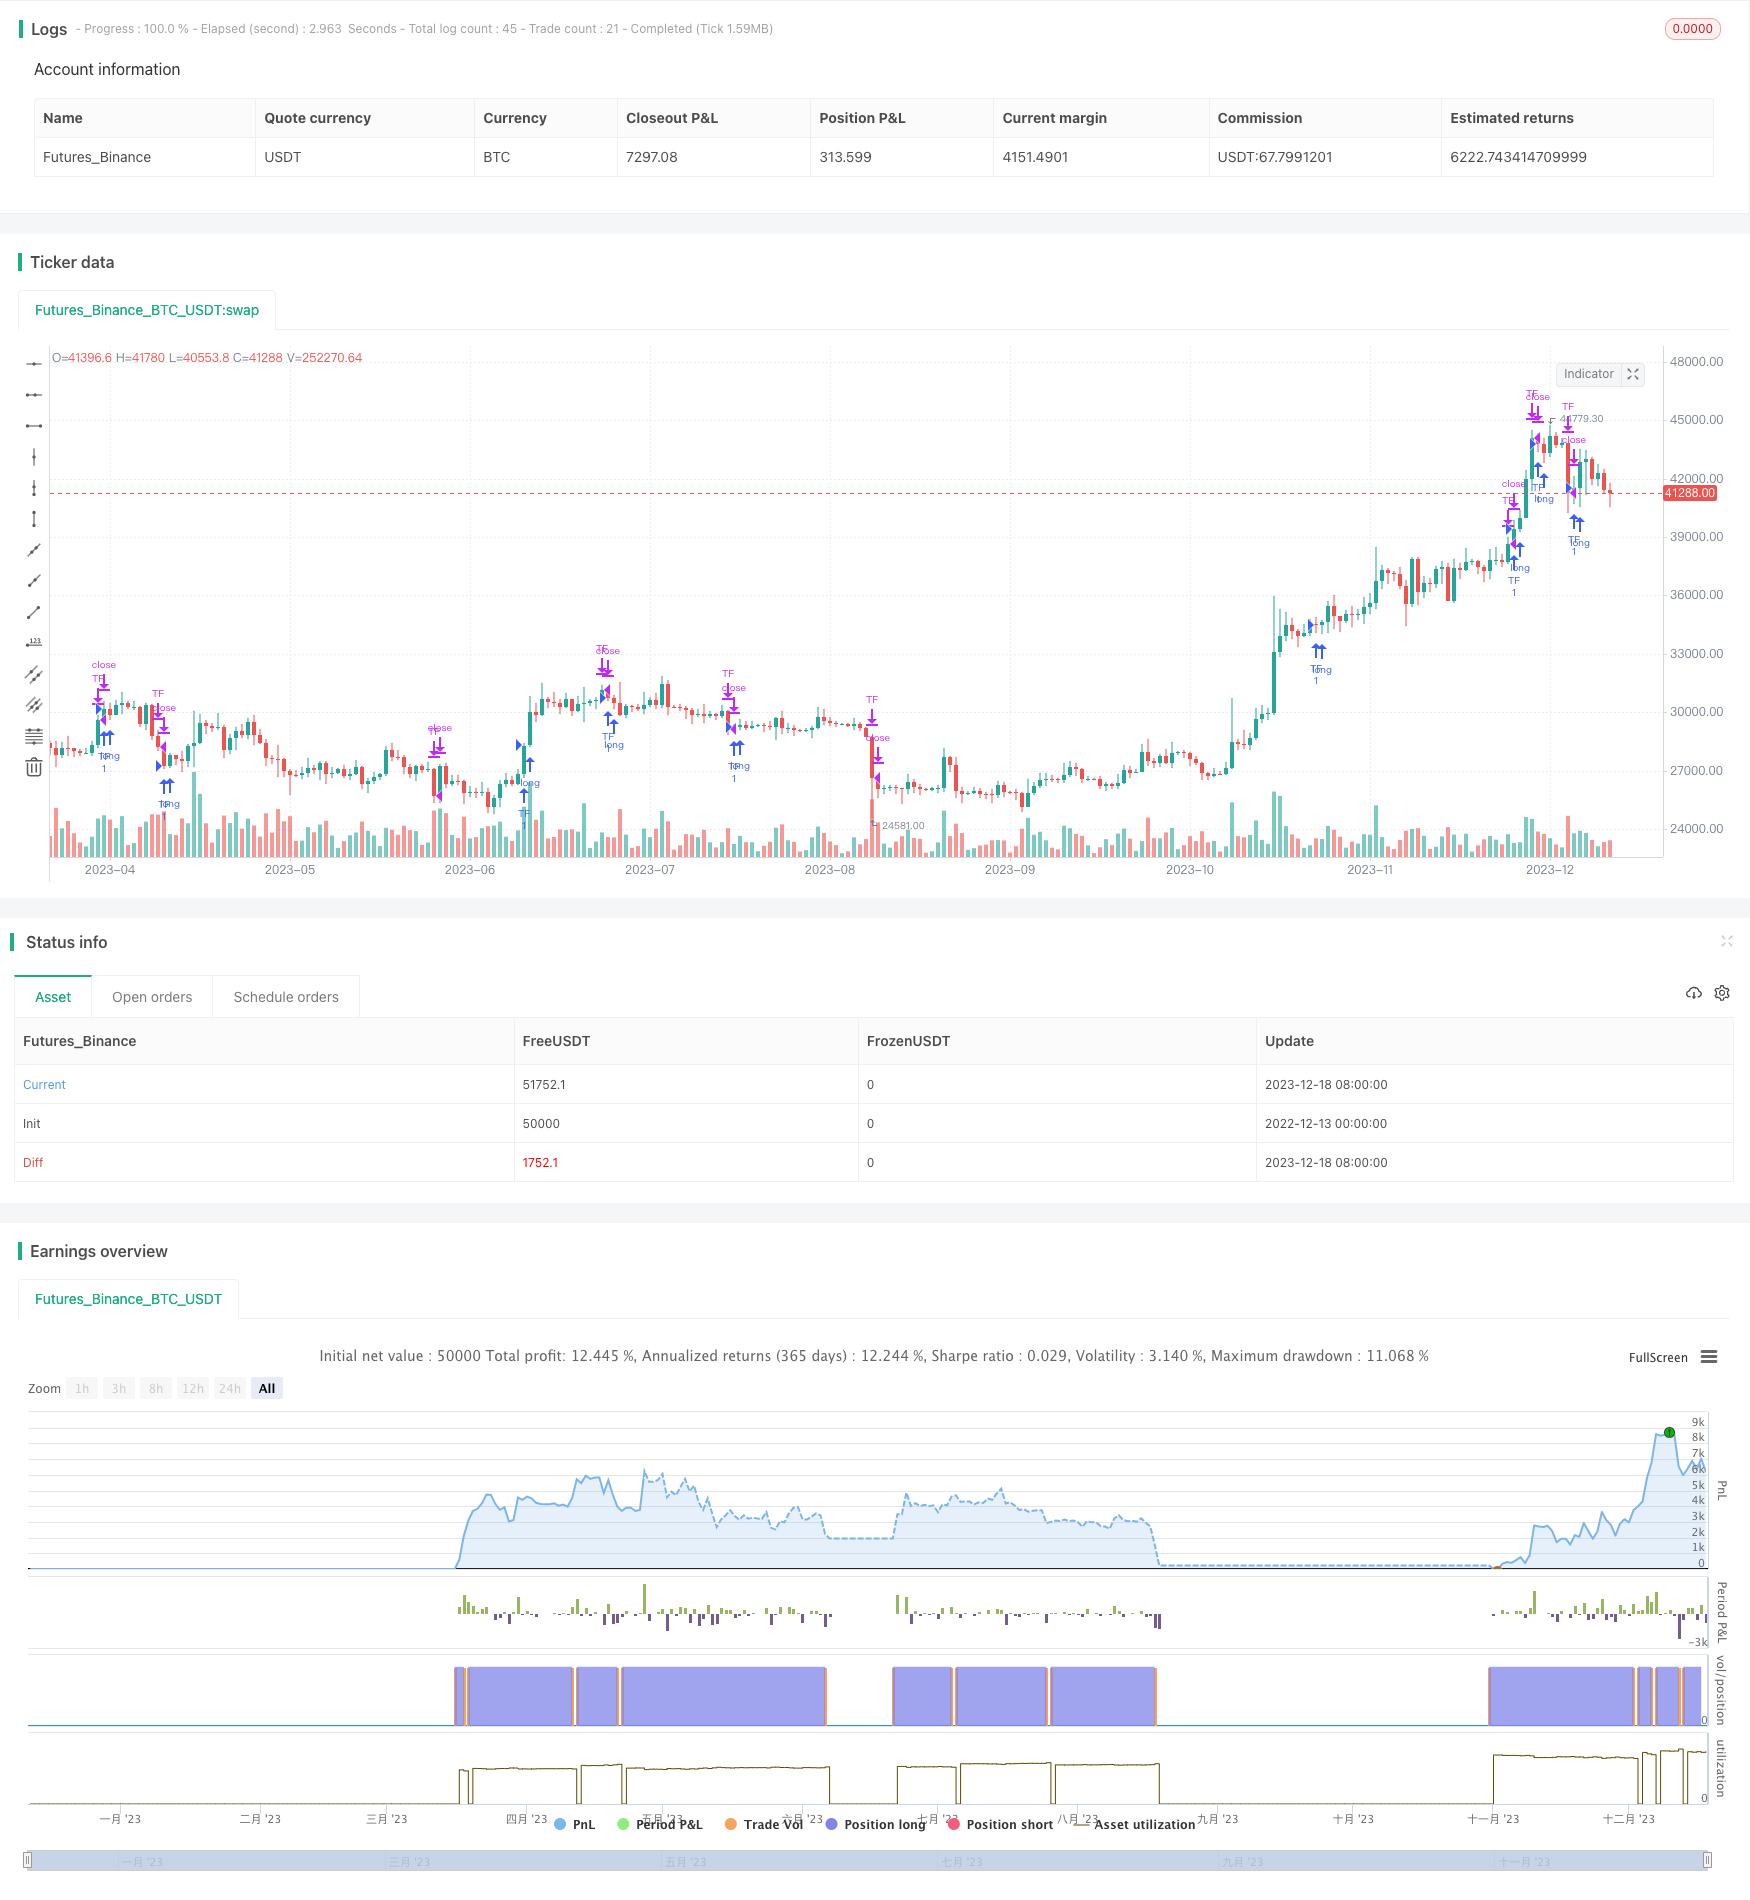
Overview
This strategy uses Mark Minervini's stock selection template and moving average indicators to determine price trends for automated entry and stop-loss. It mainly judges whether stock prices are in an uptrend and whether they have broken through key moving averages to generate buy signals. At the same time, the strategy sets a stop-loss line to actively stop losses when prices fall back.
Strategy Principle
The strategy mainly judges the following conditions and generates a buy signal when they are met at the same time:
- The current stock price is above both the 150-day and 200-day moving average lines.
- The 150-day moving average is above the 200-day moving average.
- The 200-day moving average has been trending up for at least 1 month.
- The 50-day moving average is above both the 150-day and 200-day moving averages.
- The current stock price is above the 50-day moving average.
- The current stock price is at least 25% above its 52-week low.
- The current stock price is within at least 25% of its 52-week high.
When the above conditions are met, the strategy judges that the stock price is in an upward trend and generates a buy signal.
In addition, the strategy also sets a stop-loss line. When the stock price falls back by 5% from its peak or rises by 10%, it will stop loss or take profit.
Advantage Analysis
- Use Mark Minervini's stock selection ideas to improve profitability.
- Use multiple moving averages to confirm the trend and avoid missing buying points.
- Set stop-loss mechanism to avoid huge losses.
Risk Analysis
- Stock prices may adjust in the short term, triggering a stop loss.
- Moving averages cannot fully determine trends, and false breakouts may occur.
- The stop loss and take profit ratios set are not perfect, may take profits or expand losses prematurely.
Optimization
- Test combinations of moving averages with different parameters.
- Add other technical indicators to determine entry timing.
- Optimize stop loss and take profit ratio settings.
Summary
The strategy overall follows the idea of trend trading, generating buy signals when the uptrend of stock prices is confirmed. At the same time, a stop-loss mechanism is set to control risks. By optimizing various detailed parameters, the stability and profitability of the strategy can be further improved. However, no strategy can completely avoid market risks, so investors need to treat it cautiously.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 260 | High Lookback Length |
| v_input_2 | 260 | Low Lookback Length |
Source Pine Script
/*backtest
start: 2022-12-13 00:00:00
end: 2023-12-19 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="Pure Mark Minervini 10%TP 5%CL", pyramiding = 0, commission_type=strategy.commission.percent, commission_value=0.08, overlay=true)

ma50 = sma(close,50)
ma150 = sma(close,150)
ma200 = sma(close,200)
ma200_22 = ma200[22]

high_loopback = input(260, "High Lookback Length")
low_loopback = input(260, "Low Lookback Length")
highest_price = highest(high, high_loopback)
lowest_price = lowest(low, low_loopback)
above52lo = ((close/lowest_price)-1)*100
below52hi = (1-(close/highest_price))*100
ep = strategy.position_avg_price

trigger = close>ma150 and close>ma200 and ma150>ma200 and ma200>ma200_22 and ma50>ma150 and ma50>ma200 and close>ma50 and above52lo>=25 and below52hi<=25 and close>0.3
var label maLabel = na
if (trigger)
    yLocation = close>ma150 and close>ma200 and ma150>ma200 and ma200>ma200_22 and ma50>ma150 and ma50>ma200 and close>ma50 and above52lo>=25 and below52hi<=25 and close>0.3 ?
         yloc.abovebar :
         yloc.belowbar

    // labelStyle = close>ma150 and close>ma200 and ma150>ma200 and ma200>ma200_22 and ma50>ma150 and ma50>ma200 and close>ma50 and above52lo>=25 and below52hi<=25 and close>0.3 ?
    //      label.style_labeldown :
    //      label.style_labelup

buy = close>ma150 and close>ma200 and ma150>ma200 and ma200>ma200_22 and ma50>ma150 and ma50>ma200 and close>ma50 and above52lo>=25 and below52hi<=25 and close>0.3
sell = close>ep*1.1 or close<ep*0.95

strategy.entry("TF", strategy.long, when = buy)
strategy.close("TF", when = sell)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Strategy-Based-on-Moving-Average-435962.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m