Strategy vault / Trend following
Trend Following Strategy Based on Trend Confidence
The main idea of this strategy is to implement a trend following strategy that is as precise as possible. It judges the continuity possibility of the current linear trend by calculating the "confidence" of a certain…
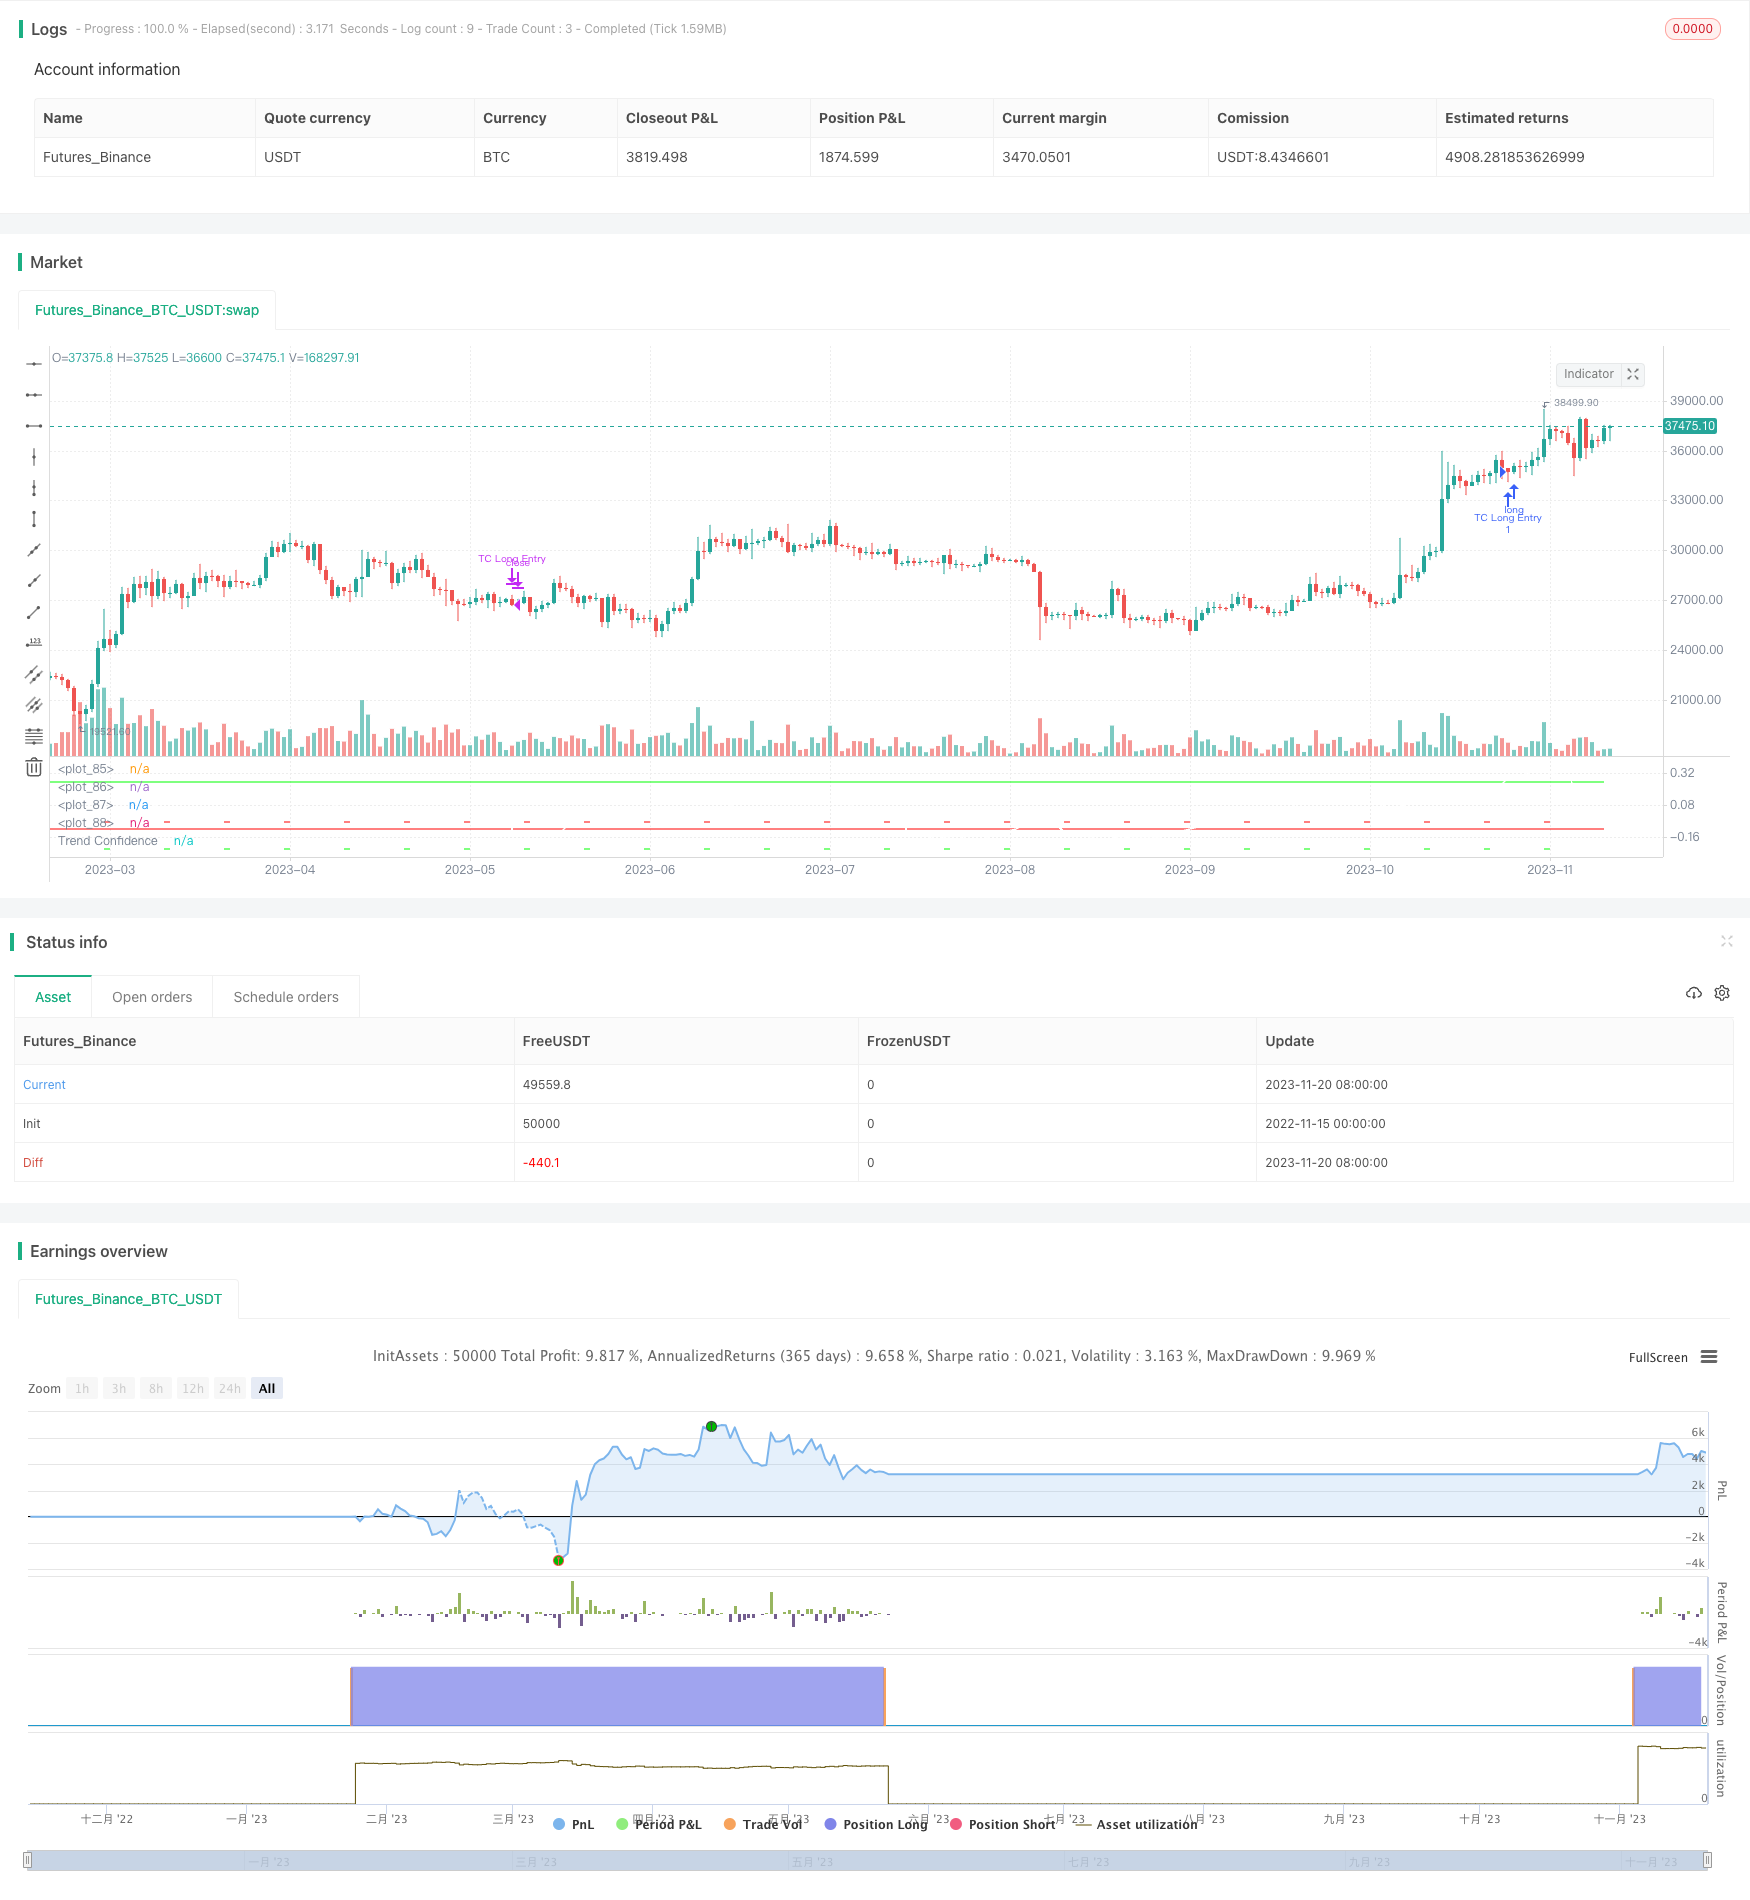
Overview
The main idea of this strategy is to implement a trend following strategy that is as precise as possible. It judges the continuity possibility of the current linear trend by calculating the "confidence" of a certain number of past closing prices. The strategy assumes that once the confidence exceeds a certain level, the ongoing linear trend is more likely to continue.
Strategy Principle
The strategy calculates the linear fit of the past N closing prices using ordinary linear regression, obtaining the slope k and standard deviation σ of the deviation from the closing prices. Then the trend confidence is defined as k/σ.
When the trend confidence exceeds the "long entry" threshold, go long; when it drops to the "long exit" threshold, close long. Similarly, when the trend confidence is below the "short entry" threshold, go short; when it exceeds the "short exit" threshold, close short.
This way it can filter out signals from wild price moves that do not follow a clear linear trend.
Advantage Analysis
The strategy combines trend following and linear regression methods in statistics, which can avoid following short-term price fluctuations and only follow long-term trends, thus obtaining lower trading frequency and higher win rate.
The strategy has large parameter tuning space and can be adapted to different products and timeframes by adjusting parameters, achieving good generalizability.
Risk Analysis
The strategy has the risk of being trapped. It will generate large losses when significant trend reversal occurs. In addition, improper parameter settings can also lead to overtrading or missing good trading opportunities.
Stop loss can be set to control downside risk. At the same time, the choice of parameters must be evaluated carefully to avoid overfitting.
Optimization Directions
The strategy can be further optimized in the following aspects:
Add stop loss/take profit logic to lock in profits and control risks
Add adaptive optimization module for dynamic parameter adjustment
Add machine learning model to determine trend reversal points and further improve win rate
Test adaptability on different products and timeframes to improve generalization
Conclusion
In general, this is a long-term trend following strategy with risk control. It combines trend following and linear regression methods to filter out noise trading signals. Through parameter tuning, it can adapt well to different products and timeframes, and is an effective strategy worth in-depth research and improvement.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | timestamp(2000-01-01) | Start trading interval |
| v_input_3 | timestamp(2030-01-01) | End trading interval |
| v_input_4 | 30 | Length |
| v_input_bool_1 | true | Longs |
| v_input_bool_2 | true | Shorts |
| v_input_float_1 | 0.25 | Long entry threshold |
| v_input_float_2 | -0.1 | Long exit threshold |
| v_input_float_3 | -0.25 | Short entry threshold |
| v_input_float_4 | -0.05 | Short exit threshold |
| v_input_float_5 | 10 | Stop loss (percentage) |
Source Pine Script
/*backtest
start: 2022-11-15 00:00:00
end: 2023-11-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © carefulCamel61097

// ################################################################################################

// "This is a trend following strategy that performed very well on the past 5 years"
// "Intended to be used on BTC-USDT, 4hr timeframe"

// "A factor 2 Leverage can be added by changing Order Size to 200% of equity"
// "Higher leverage is not recommended due to big drawdowns"

// "Also seems to work on 1D timeframe, although ideal parameters may be different"
// "Also seems to work on ETH-USDT and some other altcoins, although ideal parameters are different"

// ################################################################################################

//@version=5
strategy("Trend Following based on Trend Confidence", overlay=false )

// Inputs

source      = input(close)

since       = input(timestamp('2000-01-01'), title='Start trading interval')
till        = input(timestamp('2030-01-01'), title='End trading interval')

length      = input(30, title='Length')

longs_on    = input.bool(true, title='Longs')
shorts_on   = input.bool(true, title='Shorts')

// Parameters for best performance 2018 - 2022
// long_entry  = input.float(0.26, step=0.01, title='Long entry threshold')
// long_exit   = input.float(-0.10, step=0.01, title='Long exit threshold')
// short_entry = input.float(-0.24, step=0.01, title='Short entry threshold')
// short_exit  = input.float(-0.04, step=0.01, title='Short exit threshold')

long_entry  = input.float(0.25, step=0.01, title='Long entry threshold')
long_exit   = input.float(-0.10, step=0.01, title='Long exit threshold')
short_entry = input.float(-0.25, step=0.01, title='Short entry threshold')
short_exit  = input.float(-0.05, step=0.01, title='Short exit threshold')

stop_loss   = input.float(10, step=1, title='Stop loss (percentage)') / 100

// Trend Confidence

linreg = ta.linreg(source, length, 0)
linreg_p = ta.linreg(source, length, 0+1)

x = bar_index
slope = linreg - linreg_p
intercept = linreg - x*slope
deviationSum = 0.0
for i = 0 to length-1
    deviationSum := deviationSum + math.pow(source[i]-(slope*(x-i)+intercept), 2)
deviation = math.sqrt(deviationSum/(length))

slope_perc = slope / source[0]
deviation_perc = deviation / source[0]
trend_confidence = slope_perc / deviation_perc

// Strategy

in_interval = true

sl_long = strategy.position_avg_price * (1 - stop_loss)
sl_short = strategy.position_avg_price * (1 + stop_loss)

if in_interval and longs_on and ta.crossover(trend_confidence, long_entry)
    strategy.entry("TC Long Entry", strategy.long)
    strategy.exit("TC Long Exit", stop=sl_long)
if in_interval and longs_on and ta.crossunder(trend_confidence, long_exit)
    strategy.close("TC Long Entry")

if in_interval and shorts_on and ta.crossunder(trend_confidence, short_entry)
    strategy.entry("TC Short Entry", strategy.short)
    strategy.exit("TC Short Exit", stop=sl_short)
if in_interval and shorts_on and ta.crossover(trend_confidence, short_exit)
    strategy.close("TC Short Entry")

// Plots

plot(trend_confidence, "Trend Confidence", color.rgb(255, 255, 255))

plot(long_entry, "", color.rgb(0, 255, 0), linewidth=1)
plot(long_exit, "", color.rgb(255, 0, 0), linewidth=1)
plot(short_entry, "", color=bar_index % 10 == 0 ? color.rgb(0, 255, 0) : #00000000, linewidth=1)
plot(short_exit, "", color=bar_index % 10 == 0 ? color.rgb(255, 0, 0) : #00000000, linewidth=1)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Strategy-Based-on-Trend-Confidence.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h