Strategy vault / Trend following
Trend Strength Confirm Bars Strategy
Overview: This strategy judges the trend direction based on the closing price direction of consecutive N candlesticks. Trading signals are generated when the closing prices of N consecutive candlesticks meet the…
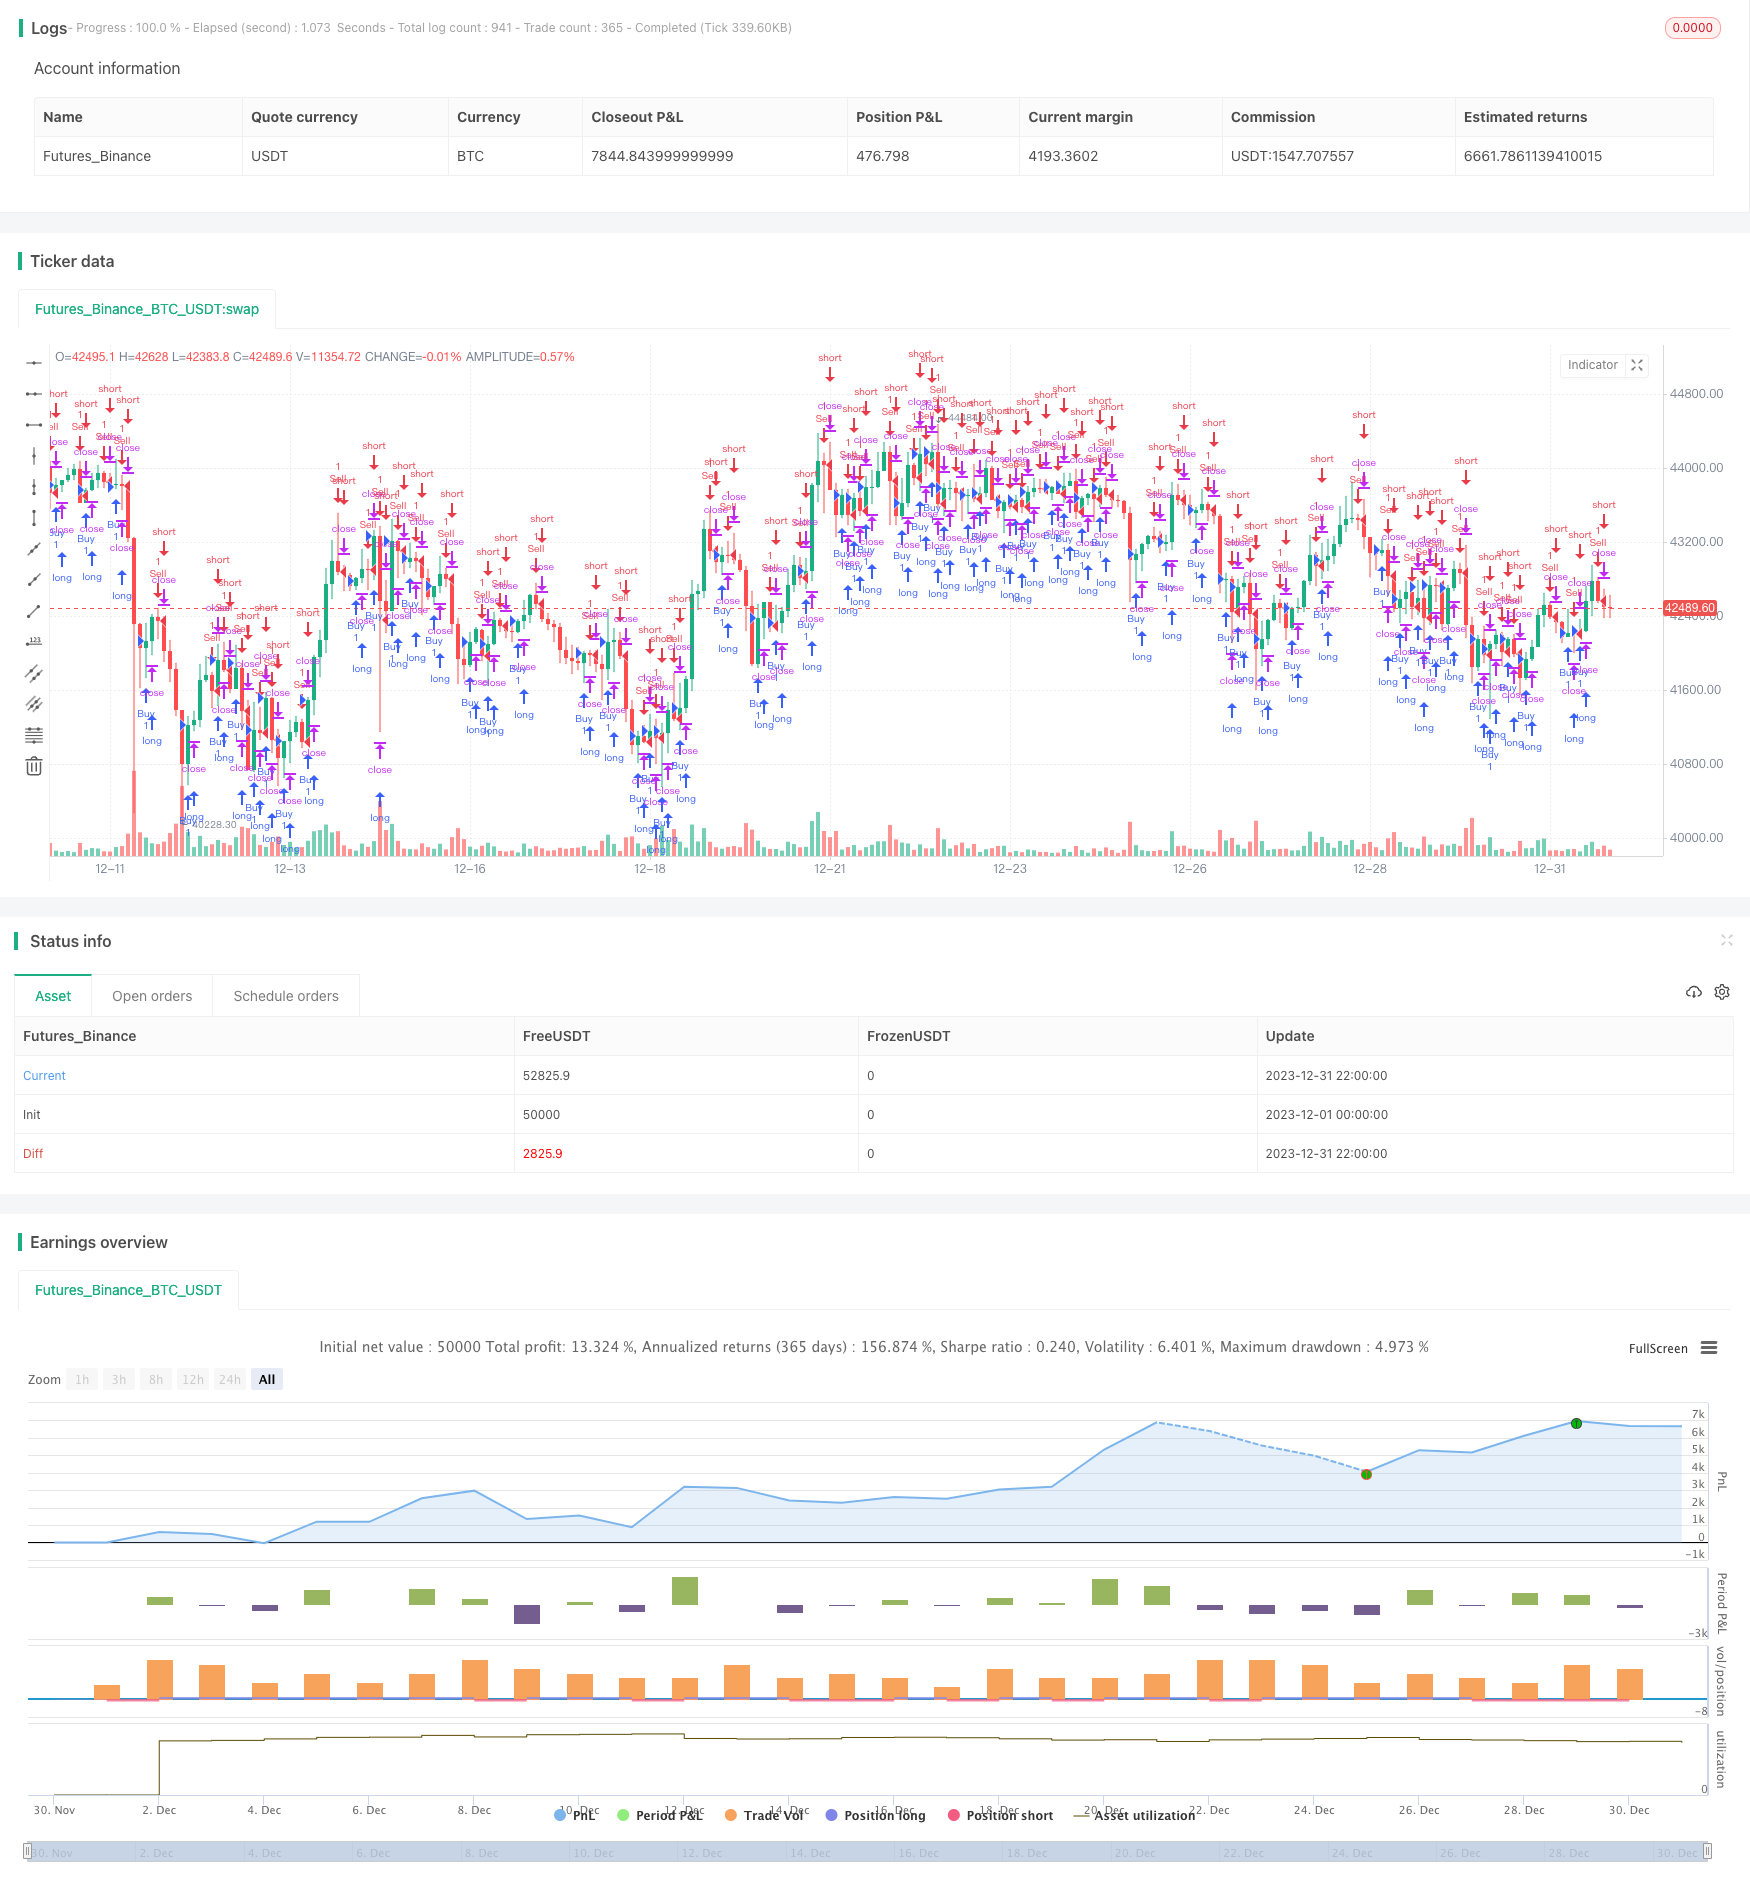
Overview: This strategy judges the trend direction based on the closing price direction of consecutive N candlesticks. Trading signals are generated when the closing prices of N consecutive candlesticks meet the condition. The size of N is set by the confirmBars input parameter. This strategy mainly utilizes the direction of consecutive N candlestick closing prices to determine the strength of the trend. Larger N requires more candlesticks to confirm the trend, which can filter out false breakouts but may also miss the early stage of trends.
Principle:
The strategy tracks the relationship between the closing prices of the last candlestick and the previous one to judge the strength of price rises and falls. Specifically, it defines two variables bcount and scount to record the number of consecutive candlestick closing prices that rise and fall.
When bcount reaches the value set by confirmBars, it means that the closing prices of confirmBars consecutive candlesticks have risen, generating a buy signal. When scount reaches the value set by confirmBars, it means that the closing prices of confirmBars consecutive candlesticks have fallen, generating a sell signal.
By judging the direction of the closing prices of consecutive multiple candlesticks, short-term market fluctuations can be effectively filtered out, and trading signals are only generated under trends of relatively large strength.
Advantage Analysis:
Effectively filter out noise and confirm trends
This strategy requires consecutive N candlesticks closing prices to meet the conditions before generating trading signals. This filters out the impact of normal market fluctuations on trading and ensures that positions are opened only under strong trends.Adjustable filtering strength parameters By adjusting the size of the confirmBars parameter, the strength of filtering price fluctuations can be controlled. Larger parameters have better filtering effects on noise, but may also miss early trend opportunities.
Risk Analysis:
May miss early trend opportunities The strategy requires multiple consecutive candlesticks closing prices to meet conditions before generating signals, so it often misses early trend opportunities and cannot track trends in a timely manner.
Prone to stop loss breakout When the number of confirmations confirmBars is set too large, it is easy to be misled by reverse short-term lines in the early stage of the trend, resulting in stop loss breakouts.
Optimization Directions:
Filter fake breakouts with other indicators
Other technical indicators such as Bollinger Bands and RSI can be used to perform secondary filtering on buy and sell signals to reduce the possibility of fake breakouts.Dynamically adjust parameters Try to dynamically adjust the confirmBars parameter based on market conditions. Increase the parameter value in volatile markets to filter out noise; decrease the parameter value when the trend is obvious to track the trend.
Summary:
This strategy achieves the effect of filtering shocks and confirming trends by judging the direction of closing prices of multiple consecutive candlesticks. It can effectively reduce erroneous trades caused by short-term market fluctuations and only generate trading signals when trends are obvious. By adjusting the size of the confirmBars parameter, users can balance the relationship between filtering effects and capturing trend opportunities. However, this strategy is prone to being stopped out early in trend initiation and fails to continuously track trends. It is recommended to optimize with other indicators or try dynamic parameter adjustment to pursue better returns.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | confirmBars |
| v_input_int_1 | 2019 | Backtest Start Year |
| v_input_int_2 | true | Backtest Start Month |
| v_input_int_3 | true | Backtest Start Day |
| v_input_int_4 | 2023 | Backtest End Year |
| v_input_int_5 | 12 | Backtest End Month |
| v_input_int_6 | 31 | Backtest End Day |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Confirm Bars Strategy [TS Trader]", overlay=true)

confirmBars = input(1)

// === INPUT BACKTEST RANGE ===
fromYear = input.int(2019, title="Backtest Start Year")
fromMonth = input.int(1, title="Backtest Start Month", minval=1, maxval=12)
fromDay = input.int(1, title="Backtest Start Day", minval=1, maxval=31)
toYear = input.int(2023, title="Backtest End Year")
toMonth = input.int(12, title="Backtest End Month", minval=1, maxval=12)
toDay = input.int(31, title="Backtest End Day", minval=1, maxval=31)

startTimestamp = timestamp(fromYear, fromMonth, fromDay, 00, 00)
endTimestamp = timestamp(toYear, toMonth, toDay, 23, 59)

inBacktestRange = true

// === STRATEGY LOGIC ===
bcount = 0
bcount := close[1] < close ? nz(bcount[1]) + 1 : 0
if (bcount == confirmBars and inBacktestRange)
    strategy.entry("Buy", strategy.long, comment="Long")

scount = 0
scount := close[1] > close ? nz(scount[1]) + 1 : 0
if (scount == confirmBars and inBacktestRange)
    strategy.entry("Sell", strategy.short, comment="Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Strength-Confirm-Bars-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h