Strategy vault / Trend following
Trend Tracking Short term Trading Strategy
This strategy uses the trend judging indicator ADX and moving averages to determine and track trends. When a trend reversal is identified, it uses breakout operations for short-term trading.
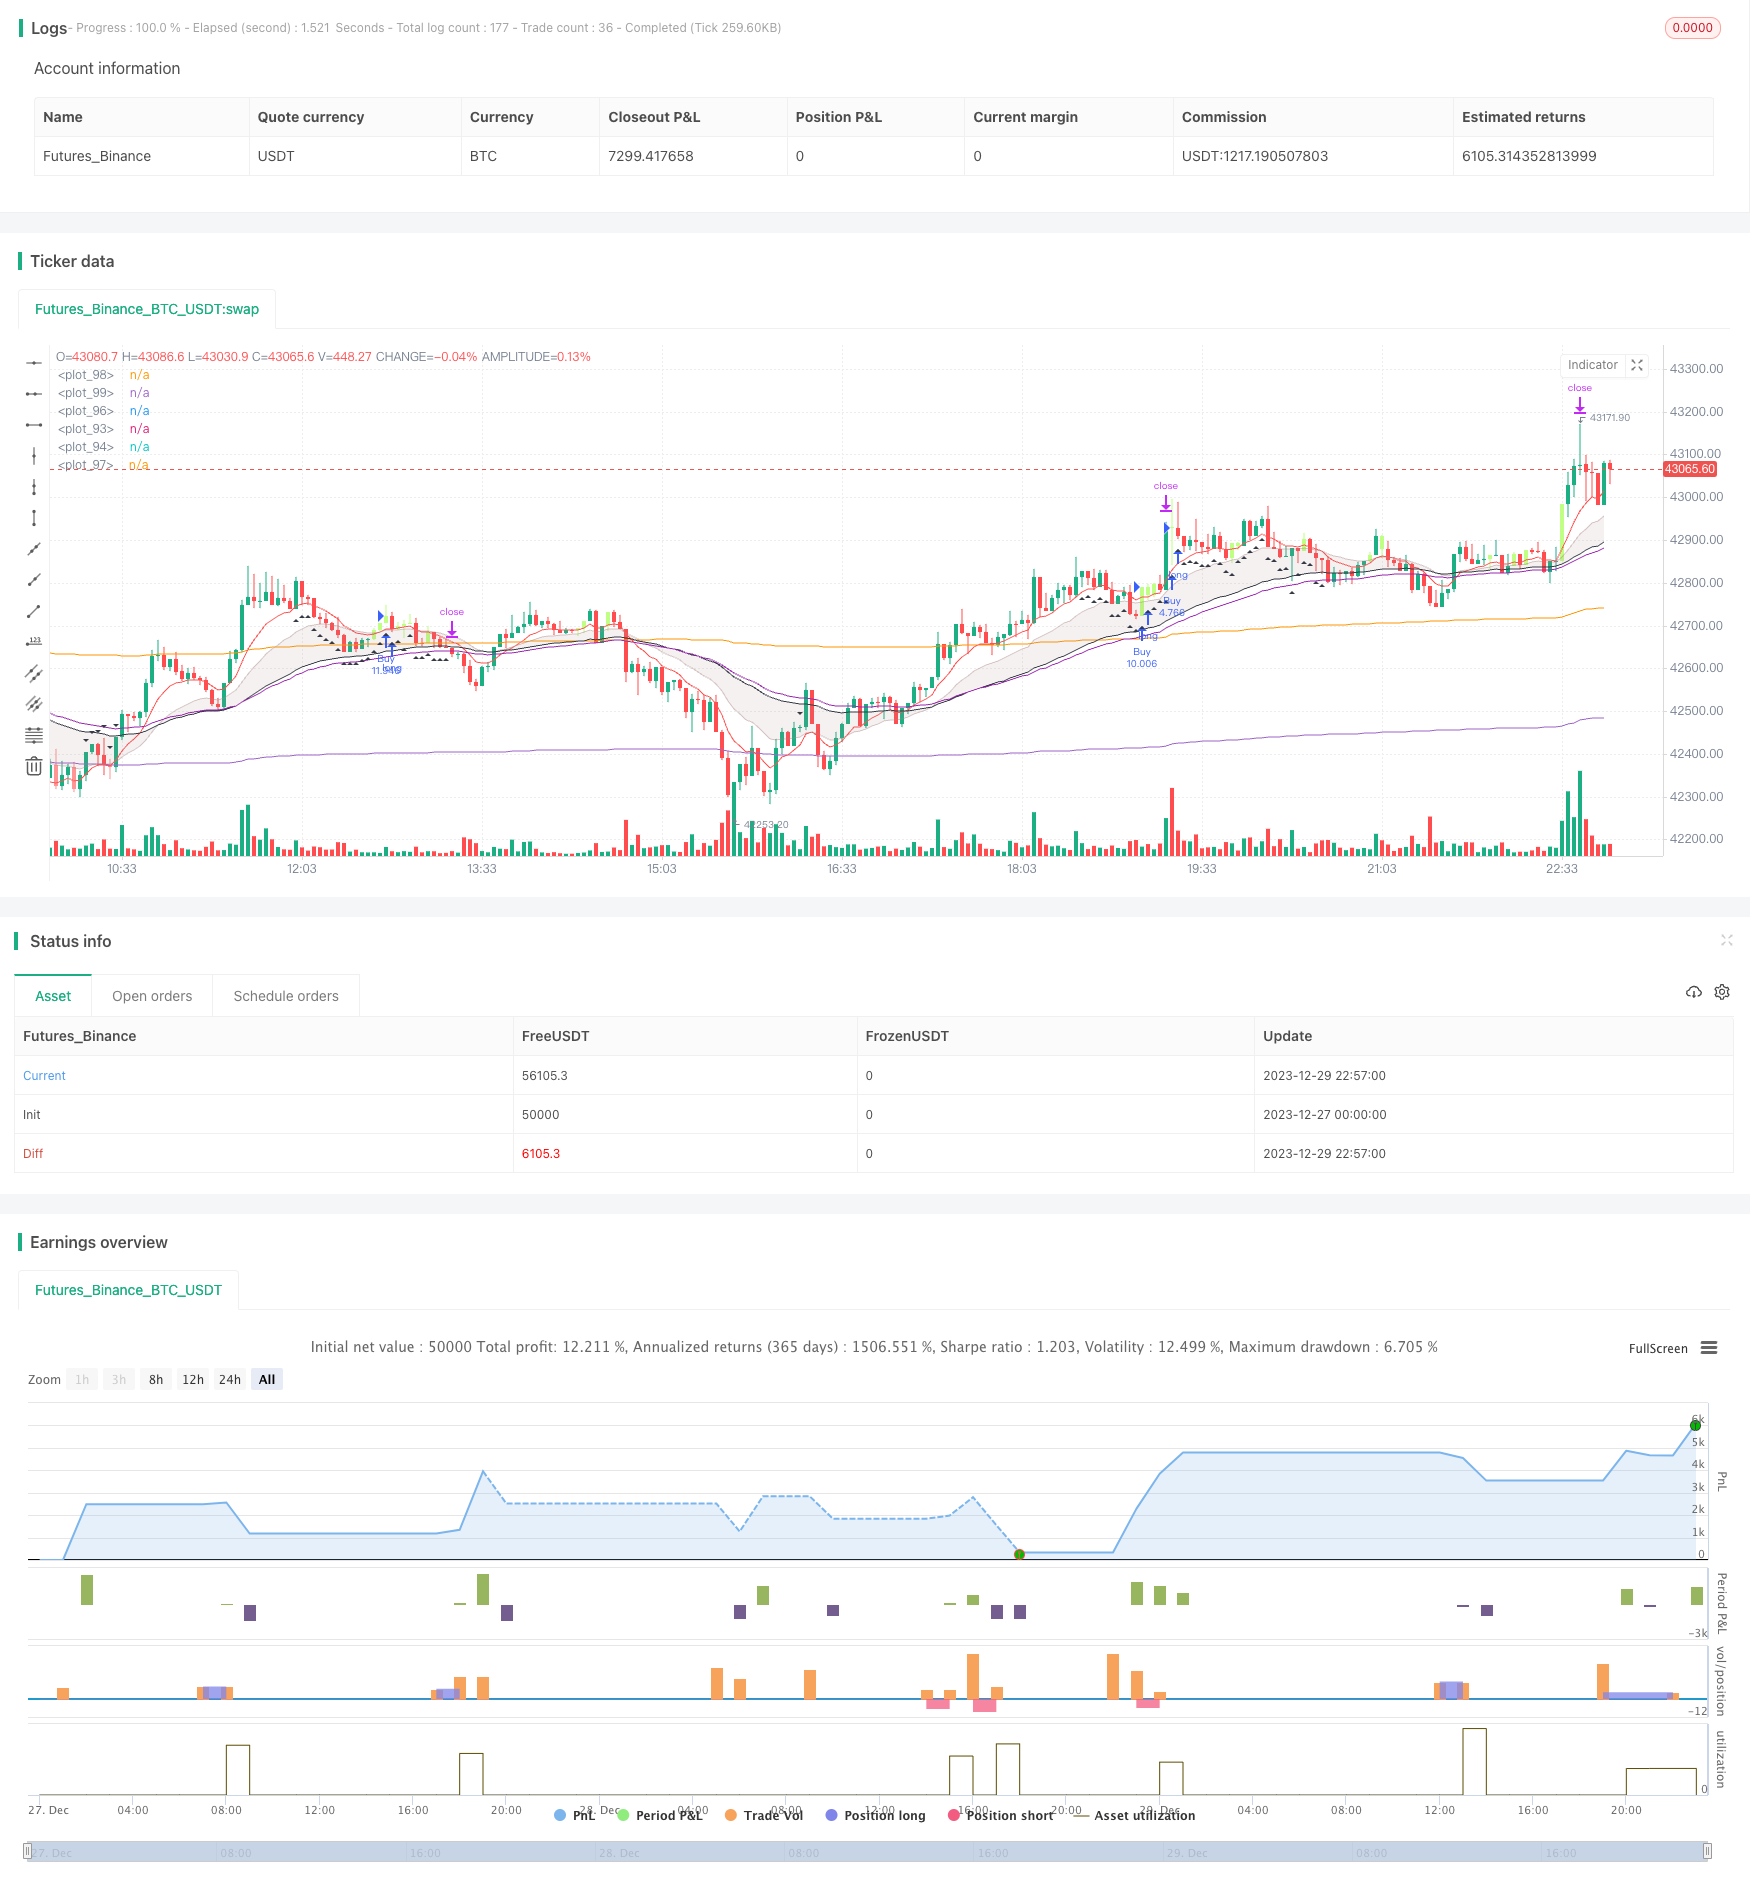
Overview
This strategy uses the trend judging indicator ADX and moving averages to determine and track trends. When a trend reversal is identified, it uses breakout operations for short-term trading.
Strategy Logic
- Use ADX to judge the trend direction. ADX above 20 indicates a trending market.
- Use EMA crossovers to determine uptrends and downtrends. Golden cross for uptrend and death cross for downtrend.
- Use VWAP as an important reference price level. Price above VWAP indicates bullish sentiment and below indicates bearish sentiment.
- Enter positions based on the comprehensive trend analysis from the indicators when a trend reversal is identified. Track the new trend using short-term trading.
Advantage Analysis
- Comprehensive trend analysis using multiple indicators improves accuracy.
- VWAP avoids trading in ineffective price zones.
- Only trade when ADX confirms a trend, avoiding false signals.
- Breakout trading aligns well with momentum. Higher probability of success.
Risk Analysis
- Failed breakout leading to a stop loss is possible. Can optimize stop loss placement.
- Higher trade frequency risks individual losing trades. Can adjust position sizing.
- Time frame and symbol selection impacts performance. Test different configurations.
Optimization Directions
- Optimize ADX parameters for better trend vs range identification.
- Test EMA combinations for better trend identification.
- Widen stop loss to reduce trading costs.
- Reduce position sizing to lower risk per trade.
Conclusion
This strategy comprehensively utilizes moving averages, trend indicators and key price levels to accurately determine market trends. It identifies trend reversals to trade breakouts and track the new trend direction for short-term profits. Further optimization can improve performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 1400-1500 | Session Time |
| v_input_float_1 | 1.5 | Risk to reward |
| v_input_2 | false | Move to Break Even |
| v_input_float_2 | true | Break Even at |
| v_input_3 | 3 | VWAP Multiplier |
| v_input_4 | BTC_USDT:swap | VWAP Source |
Source Pine Script
/*backtest
start: 2023-12-27 00:00:00
end: 2023-12-29 23:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © mariocastel

//@version=5
strategy("Wave Rider", overlay=true, initial_capital = 100000)

session = input(defval = "1400-1500", title = "Session Time")
t = not na(time(timeframe.period,session))
RR = input.float(1.5, "Risk to reward", step=0.5)
var bool movetoBE = input(false, "Move to Break Even")
BE = input.float(1, "Break Even at", step=0.5)

vwap_mult = 0.001 * input(3, "VWAP Multiplier")
aboveVWAP = ta.vwap(close) * (1 + vwap_mult)
belowVWAP = ta.vwap(close) * (1 - vwap_mult)
sym = input("BTC_USDT:swap", "VWAP Source")

QQQaboveVWAP = request.security(sym, "3", aboveVWAP)
QQQbelowVWAP = request.security(sym, "3", belowVWAP)
QQQclose = request.security(sym, "3", close)

ema20 = ta.ema(close, 20)
ema50 = ta.ema(close, 50)
ema60 = ta.ema(close, 60)
ema9 = ta.ema(close, 9)

opentrades = strategy.opentrades > 0

aboveEMA = close > ema60
belowEMA = close < ema60

uptrend = aboveEMA and aboveEMA[1] and aboveEMA[2] and aboveEMA[3] and aboveEMA[4] and aboveEMA[5] and aboveEMA[6] and aboveEMA[7] and aboveEMA[8] and aboveEMA[9] and aboveEMA[10] and aboveEMA[11] and aboveEMA[12] and aboveEMA[13] and aboveEMA[14] and aboveEMA[15] and aboveEMA[16] and aboveEMA[17] and aboveEMA[18] and aboveEMA[19] and aboveEMA[20] and aboveEMA[21] and aboveEMA[22] and aboveEMA[23] and aboveEMA[24] and aboveEMA[25] and aboveEMA[26] and aboveEMA[27] and aboveEMA[28] and aboveEMA[29]
downtrend = belowEMA and belowEMA[1] and belowEMA[2] and belowEMA[3] and belowEMA[4] and belowEMA[5] and belowEMA[6] and belowEMA[7] and belowEMA[8] and belowEMA[9] and belowEMA[10] and belowEMA[11] and belowEMA[12] and belowEMA[13] and belowEMA[14] and belowEMA[15] and belowEMA[16] and belowEMA[17] and belowEMA[18] and belowEMA[19] and belowEMA[20] and belowEMA[21] and belowEMA[22] and belowEMA[23] and belowEMA[24] and belowEMA[25] and belowEMA[26] and belowEMA[27] and belowEMA[28] and belowEMA[29]

buy = (low < ema20 and low > ema50 and close > ema9) and QQQclose > QQQaboveVWAP  or (low[1] < ema20 and low[1] > ema50 and close > ema9) and QQQclose > QQQaboveVWAP and uptrend
sell = (high > ema20 and high < ema50 and close < ema9) and QQQclose < QQQbelowVWAP  or (high[1] > ema20 and high[1] < ema50 and close < ema9) and QQQclose < QQQbelowVWAP and downtrend

var float entry = na
var float sl = na
var float qty = na
var float tp = na
var float be = na

if ema20 > ema50 and ema9 > ema20
    if buy and not opentrades and t and uptrend
        alert("Wave Rider Setup")
        entry := close
        sl := ema50
        qty := 1000/(close - sl) * 1
        if close - sl > syminfo.mintick*300
            tp := close + ((close - sl)*1)
        else
            tp := close + ((close - sl)*RR)
        be := close + ((close - sl)*BE)
        strategy.entry("Buy", strategy.long, qty=qty)
        strategy.exit("Close Buy", "Buy",qty=qty, stop=sl, limit=tp)

if ema20 < ema50 and ema9 < ema20
    if sell and not opentrades and t and downtrend
        alert("Wave Rider Setup")
        entry := close
        sl := ema50
        qty := 1000/(sl - close) * 1
        if sl - close > syminfo.mintick*300
            tp := close - ((sl - close)*1)
        else
            tp := close - ((sl - close)*RR)
        be := close - ((sl - close)*BE)
        strategy.entry("Sell", strategy.short, qty=qty)
        strategy.exit("Close Sell", "Sell", qty=qty, stop=sl, limit=tp)

// Adjust BEs
if movetoBE == true
    if strategy.position_size > 0
        if high >= be
            sl := entry
            strategy.cancel("Close Buy")
            strategy.exit("Close Buy", "Buy", qty=qty, stop=sl, limit=tp)
    if strategy.position_size < 0
        if low <= be
            sl := entry
            strategy.cancel("Close Sell")
            strategy.exit("Close Sell", "Sell", qty=qty, stop=sl, limit=tp)


EoD_time = timestamp(year, month, dayofmonth, 15, 58, 00)
EoD = time == EoD_time
if EoD
    strategy.close_all()

barcolor(color=buy ? color.rgb(191, 255, 131): na)
barcolor(color=sell ? color.rgb(255, 149, 149): na)
ema20plot = plot(ema20, color=color.rgb(168, 131, 131, 55))
ema50plot = plot(ema50, color=color.black)
fill(ema20plot, ema50plot, color=color.rgb(168, 131, 131, 85))
plot(ema9, color=color.red)
plot(ema60, color=color.purple)
plot(QQQaboveVWAP)
plot(QQQbelowVWAP)
plotshape(uptrend, style=shape.triangleup, location=location.belowbar, color=color.black)
plotshape(downtrend, style=shape.triangledown, location=location.abovebar, color=color.black)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Tracking-Short-term-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Trend StrategyPine Script · Trend following · 1m
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- Multi Timeframe Volume and Trend Confluence Trading StrategyPine Script · Trend following · 1d
- WaveTrend and DER Based Swing Trading StrategyPine Script · Trend following · 1d
- Multi Indicator Fusion Options Selling Strategy Trend Confirmation with ATR Dynamic Stop Loss OptimizationPine Script · Trend following · 1h
- Multi Period Trend Following and Volume Analysis Adaptive Risk StrategyPine Script · Trend following · 1d