Strategy vault / Trend following
Trend Trader Bands Backtest Strategy Based on Trend Trader Moving Average
The main idea of this strategy is to judge price trends and generate trading signals using moving averages and Bollinger bands. Specifically, it first calculates the average true range (ATR) over a certain period to…
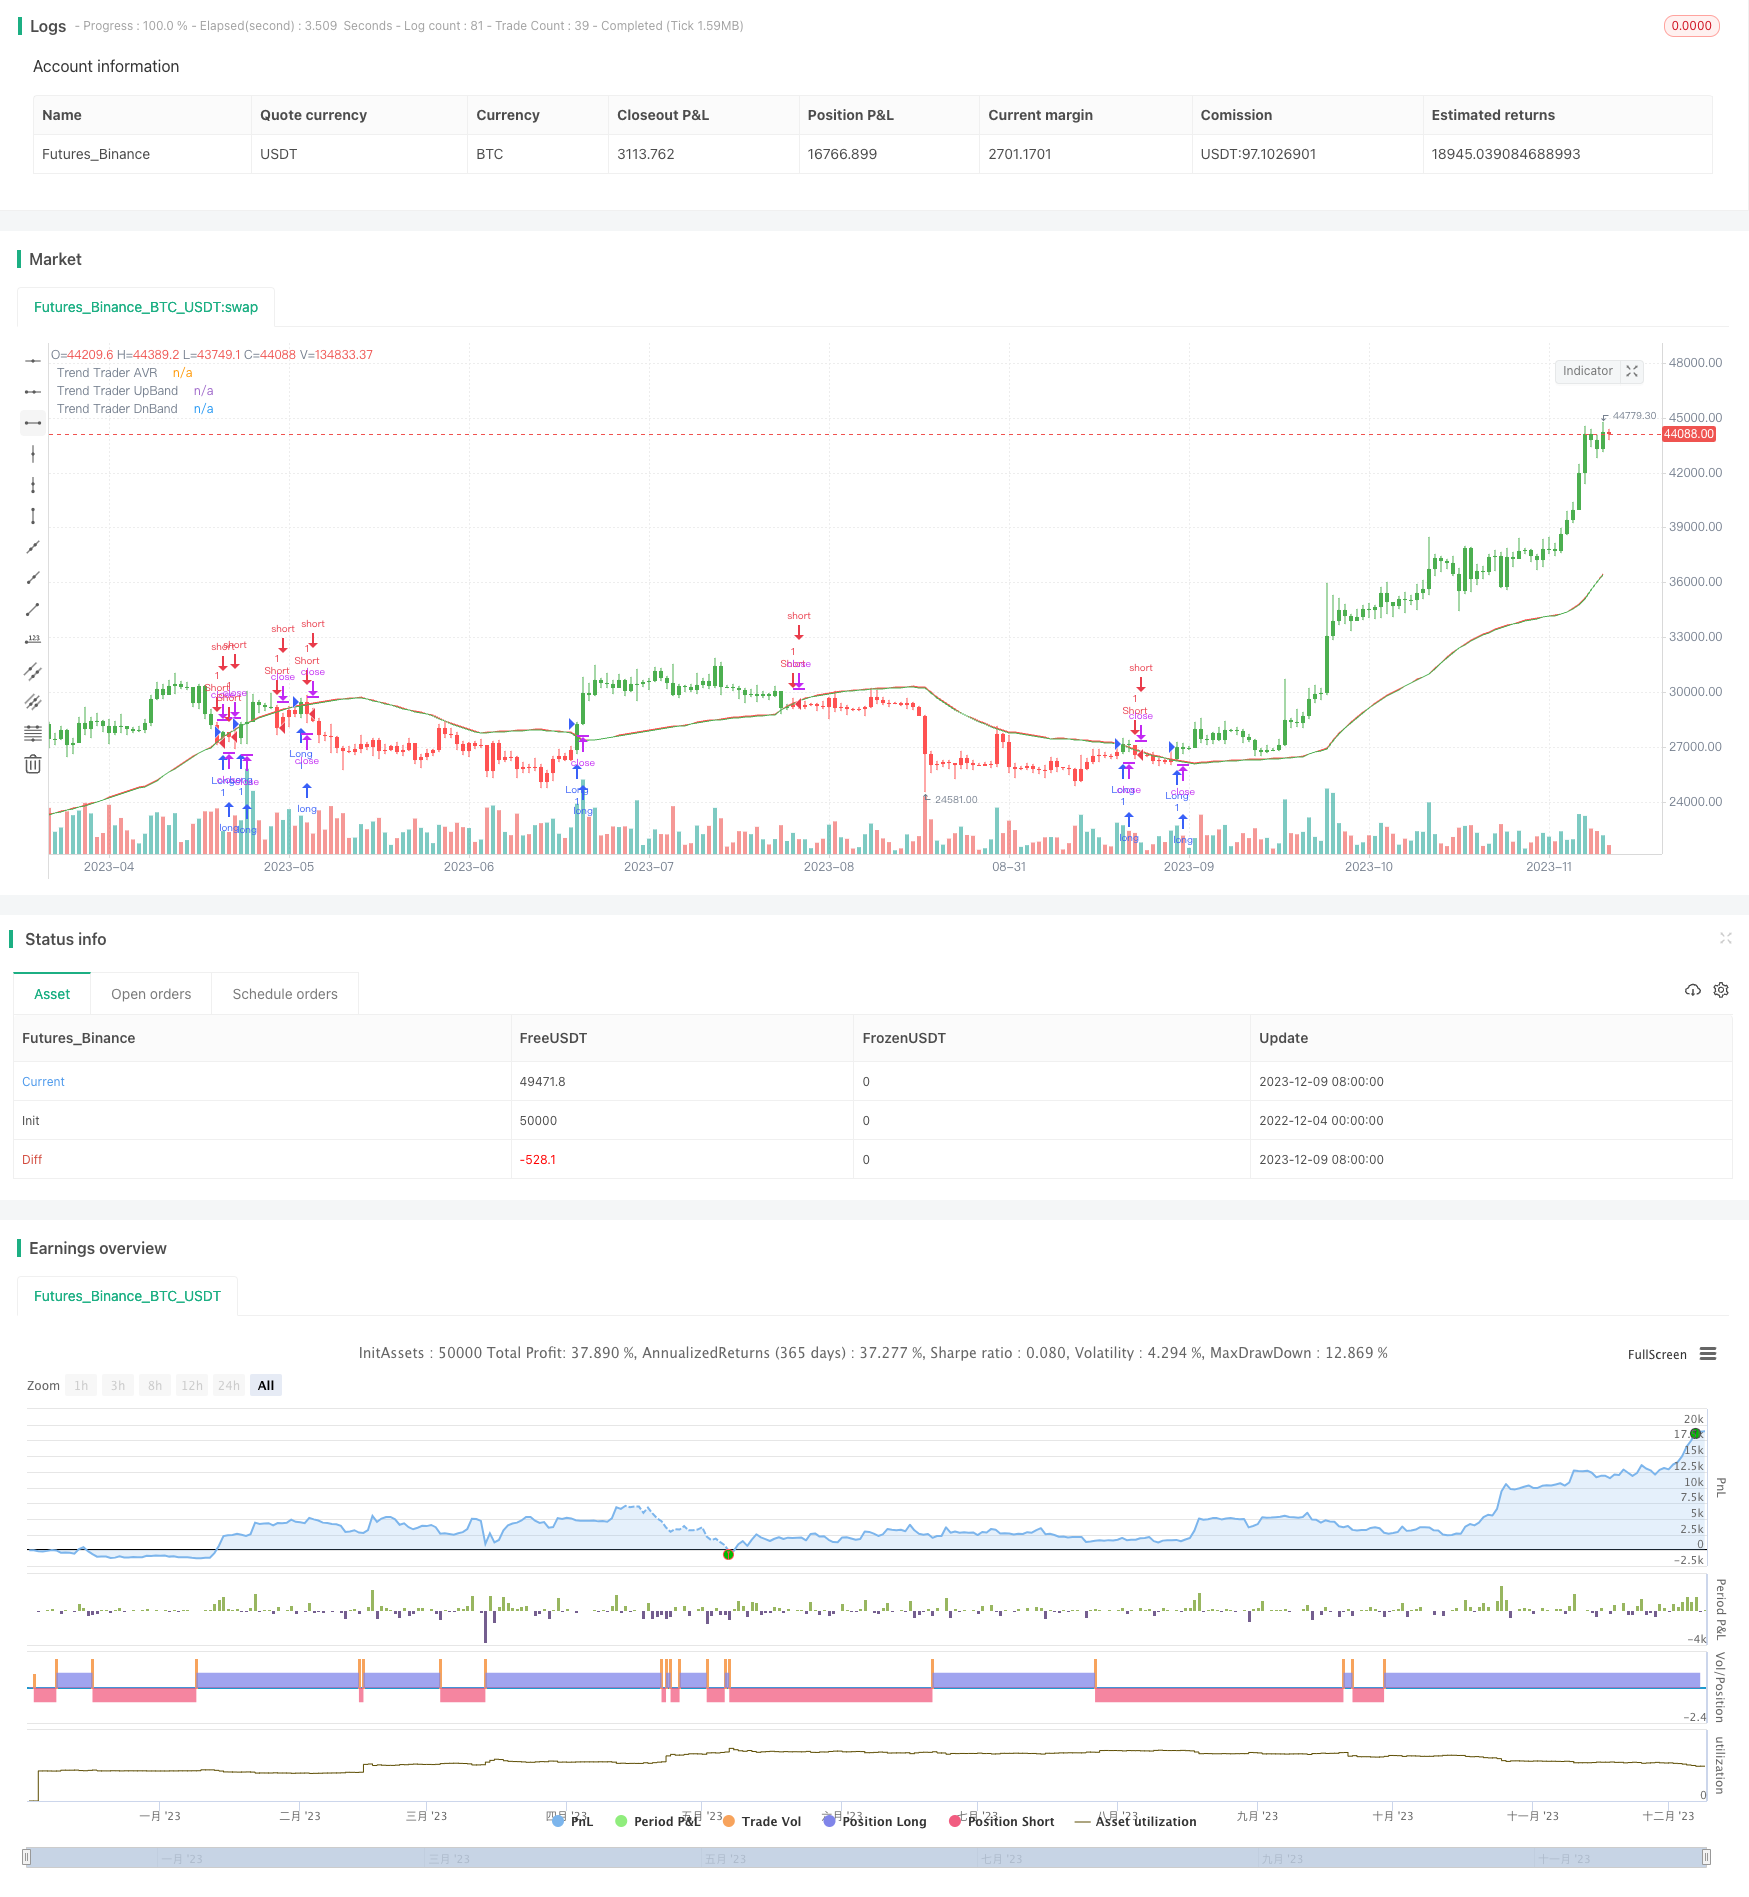
Overview
The main idea of this strategy is to judge price trends and generate trading signals using moving averages and Bollinger bands. Specifically, it first calculates the average true range (ATR) over a certain period to get volatility range, then combines highest and lowest prices to form a limiting channel. If price breaks through this channel, the close price is set to be the channel price. After that, it calculates moving average of the limited close prices, which is called Trend Trader moving average (AVR). Finally, draw Bollinger bands above and below Trend Trader moving average to form trading signals. Go long when price breaks through upper band, and go short when breaking through lower band.
Strategy Logic
The strategy first calculates ATR range and forms a limiting channel combined with highest and lowest prices. The close price will be limited to the channel price only when it breaks through the channel. After that, it calculates Trend Trader moving average of the limited close prices, which reflects mid-long term trend direction. At last, draw a upper band and a lower band parallel to the Trend Trader moving average as Bollinger bands. Breaking through upper band generates long signal and breaking through lower band generates short signal.
The core of judging trend lies in Trend Trader moving average, which embodies mid-long term trend direction. The role of Bollinger bands is to filter some false breakouts and make trading signals more reliable. The whole strategy combines trend following and breakout, forming a strong trend system.
Advantages
- ATR and price range build an adaptive channel to track market volatility
- Trend Trade AVR clearly judges mid-long term trend
- Bollinger Bands filter false breakouts and improve signal quality
- The system reflects strong trend, long holding can obtain good returns
Risks
- Long holding may suffer huge loss due to some sudden events
- Improper parameter setting may lead to over-trading, increasing transaction costs and slippage
- Performance relies heavily on parameter tuning
Solutions:
- Properly reduce holding period and set stop loss
- Optimize parameters to give signals enough buffer
- Utilize historical data and live trading for parameter tuning
Optimization Directions
- Research parameters settings on different markets and timeframes
- Test whether other indicators can filter false breakouts
- Try to incorporate stop loss to limit per trade loss
Conclusion
The strategy is overall a strong trend following system. It can judge mid-long term trend and generate trading signals combined with Bollinger bands. Through parameter optimization, it can obtain stable alpha. But risk control is also important to avoid huge losses due to some sudden events when holding for long term. Generally speaking, the strategy deserves further research and optimization for long term sustainable alpha.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 21 | Length |
| v_input_2 | 21 | LengthMA |
| v_input_3 | 20 | BandStep |
| v_input_4 | 3 | Multiplier |
| v_input_5 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2022-12-04 00:00:00
end: 2023-12-10 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 16/10/2018
// This is plots the indicator developed by Andrew Abraham
// in the Trading the Trend article of TASC September 1998
// It was modified, result values wass averages.
// And draw two bands above and below TT line.
////////////////////////////////////////////////////////////
strategy(title="Trend Trader Bands Backtest", overlay = true)
Length = input(21, minval=1),
LengthMA = input(21, minval=1),
BandStep = input(20),
Multiplier = input(3, minval=1)
reverse = input(false, title="Trade reverse")
avgTR      = wma(atr(1), Length)
highestC   = highest(Length)
lowestC    = lowest(Length)
hiLimit = highestC[1]-(avgTR[1] * Multiplier)
loLimit = lowestC[1]+(avgTR[1] * Multiplier)
ret = 0.0
ret :=  iff(close > hiLimit and close > loLimit, hiLimit,
         iff(close < loLimit and close < hiLimit, loLimit, nz(ret[1], 0)))
nResMA = ema(ret, LengthMA)
pos = 0.0
pos := iff(close < nResMA - BandStep , -1,
       iff(close > nResMA + BandStep, 1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
barcolor(pos == -1 ? red: pos == 1 ? green : blue )
plot(nResMA, color= blue , title="Trend Trader AVR")
plot(nResMA+BandStep, color= red , title="Trend Trader UpBand")
plot(nResMA-BandStep, color= green, title="Trend Trader DnBand")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Trader-Bands-Backtest-Strategy-Based-on-Trend-Trader-Moving-Average.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Adaptive Trend Following StrategyPine Script · Trend following · 4h