Strategy vault / Trend following
Trend Trading Strategy Based on Triple Hull Moving Averages and Ichimoku Kinko Hyo
This strategy combines the Hull Moving Average and Ichimoku Kinko Hyo indicators to implement a trend-following trading system. The system can capture medium-term trends for trend trading.
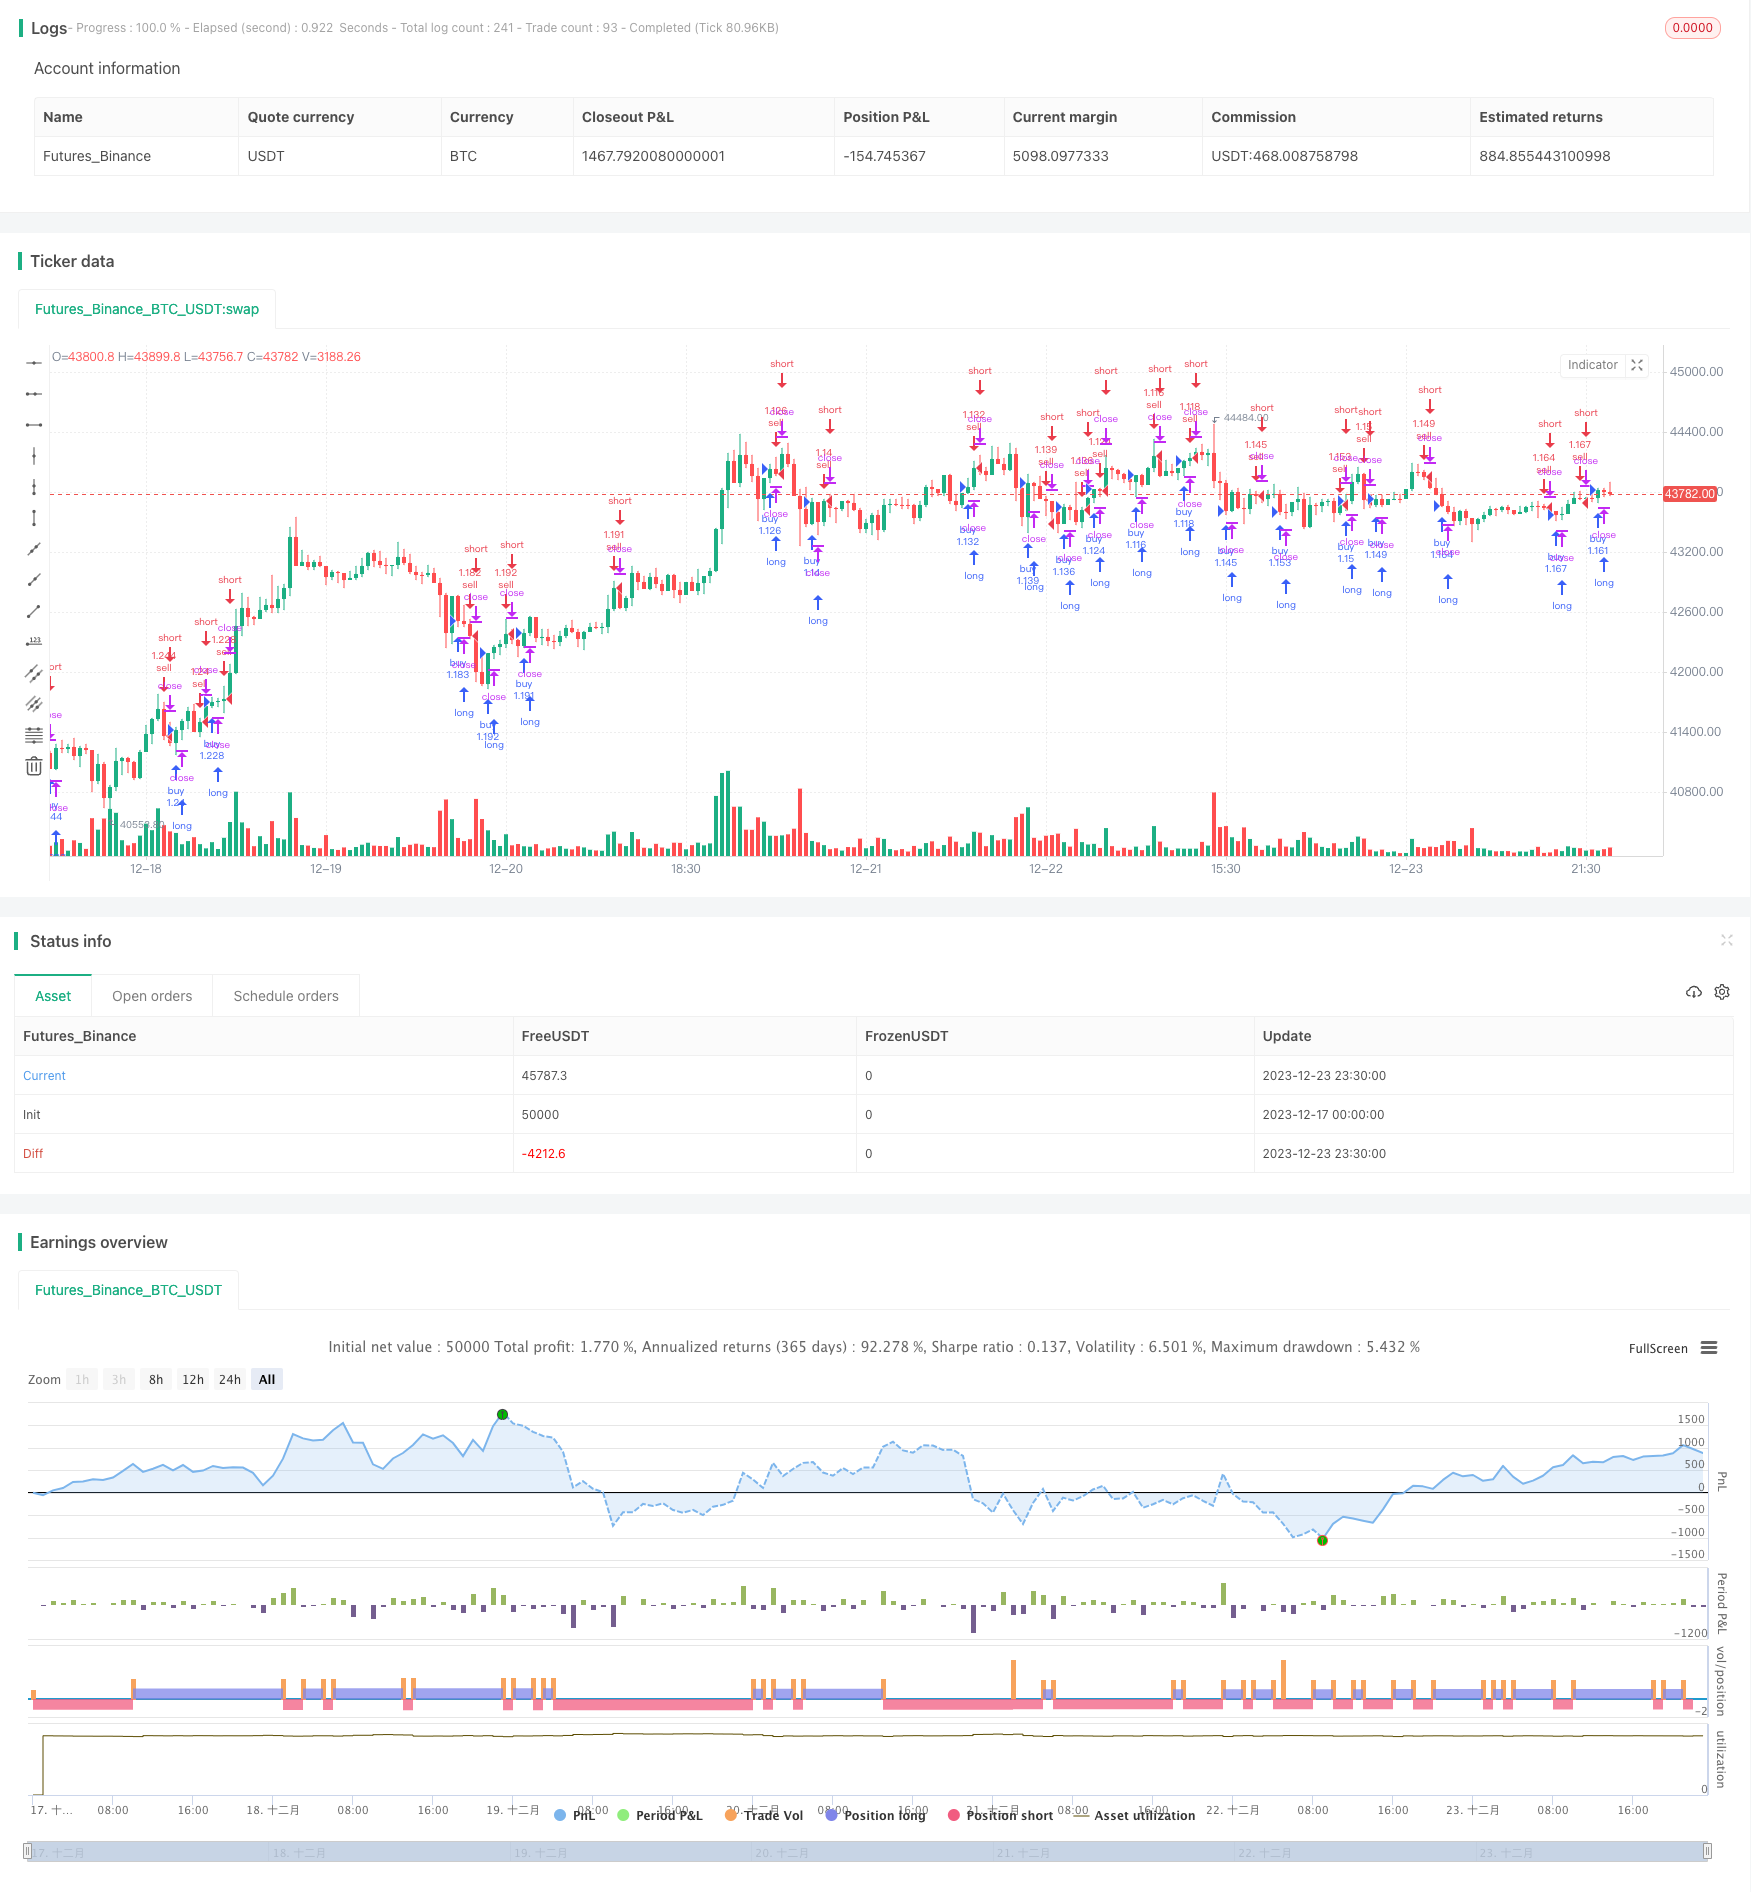
Overview
This strategy combines the Hull Moving Average and Ichimoku Kinko Hyo indicators to implement a trend-following trading system. The system can capture medium-term trends for trend trading.
Strategy Logic
This strategy uses the Hull Moving Average to determine the direction of the price trend. The Hull MA is an optimized version of the moving average that can respond more quickly to price changes. The strategy here employs a triple Hull MA system, containing 6-period, 3-period and 1.5-period Hull MAs.
In addition, the strategy also incorporates the Ichimoku Kinko Hyo conversion and lagging span lines. These two indicators reflect the medium to long term trend of the prices. The strategy combines the triple Hull MA and Ichimoku indicators to generate trading signals.
Specifically, the strategy calculates the triple Hull MA: n1, n2, n2ma. As well as two Ichimoku indicators: leadLine1 and leadLine2. It then computes post1 and post2 as the final trading metrics.
When post1 crosses over post2 upward, go long. When post1 crosses below post2, go short. This allows us to track and capture price medium-term trends for trend trading.
Advantage Analysis
The advantages of this strategy include:
- Combining dual indicators improves system stability.
- Hull MA responds fast and can capture trend changes.
- Ichimoku filters out false breakouts.
- The multiple Hull MAs can effectively track medium-term price trends.
- The strategy logic is simple and easy to understand and optimize.
Risk Analysis
There are also some risks with this strategy:
- It may generate multiple false signals during ranging markets.
- Inadequate parameter settings can lead to poor performance.
- Avoid using this strategy around major news events.
Countermeasures:
- Adjust parameters to filter out noise.
- Optimize parameters to find the best combination.
- Avoid trading around significant news releases.
Optimization Directions
This strategy can also be improved in the following aspects:
- Test Hull MA combinations of different lengths.
- Add or reduce Ichimoku indicators.
- Smooth optimizations for trading metrics post1 and post2.
- Incorporate stop loss to limit per trade loss.
Conclusion
This strategy combines the Hull MA and Ichimoku Kinko Hyo indicators to build a simple and practical trend following system. With fast responses, it can effectively capture medium-term price trends. Further testing and optimization, through parameter tuning and adding filters, can lead to better trading performance. ]
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 6 | Hull MA period |
| v_input_2 | 9 | Conversion Line Periods |
| v_input_3 | 26 | Base Line Periods |
| v_input_4 | 52 | Lagging Span 2 Periods |
| v_input_5 | 26 | Displacement |
Source Pine Script
/*backtest
start: 2023-12-17 00:00:00
end: 2023-12-24 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//                                                HULL & ICHIMOKU & MATHS
strategy("3 HULLs & ICHIMOKU divided by PRICE", shorttitle="3H&I/P", overlay=true, default_qty_type=strategy.percent_of_equity, max_bars_back=720, default_qty_value=100, calc_on_order_fills=true, calc_on_every_tick=true, pyramiding=0)
keh=input(title="Hull MA period",defval=6)
p=ohlc4[1]
n2ma=2*wma(p,round(keh/2))
nma=wma(p,keh)
diff=n2ma-nma
sqn=round(sqrt(keh))
n2ma1=2*wma(p[1],round(keh/2))
nma1=wma(p[1],keh)
diff1=n2ma1-nma1
sqn1=round(sqrt(keh))
n1=wma(diff,sqn)
n2=wma(diff1,sqn)
conversionPeriods = input(9, minval=1, title="Conversion Line Periods")
basePeriods = input(26, minval=1, title="Base Line Periods")
laggingSpan2Periods = input(52, minval=1, title="Lagging Span 2 Periods")
displacement = input(26, minval=1, title="Displacement")
donchian(len) => avg(lowest(len), highest(len))
conversionLine = donchian(conversionPeriods)
baseLine = donchian(basePeriods)
leadLine1 = avg(conversionLine, baseLine)
leadLine2 = donchian(laggingSpan2Periods)
post1=((n1[1]*3)+leadLine1)/p
post2=((n2[1]*3)+leadLine2)/p
if (post1<post2)
    strategy.entry("buy", strategy.long, comment="BUY")
if (post1>post2)
    strategy.entry("sell", strategy.short, comment="SELL")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Trading-Strategy-Based-on-Triple-Hull-Moving-Averages-and-Ichimoku-Kinko-Hyo.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Triple Supertrend Ichimoku Cloud Quantitative Trading StrategyPine Script · Trend following · 1d
- A Strict Trend Following Strategy Based on Ichimoku Kinko HyoPine Script · Trend following · 30m
- ADX Based One Hour TENKAN KIJUN Cross Trend Tracking StrategyPine Script · Trend following · 1h
- Cloud based Trend Strategy Using Ichimoku CloudPine Script · Trend following · 1h
- Cross Moving Average Golden Cross Death Cross StrategyPine Script · Trend following · 1d
- Crossing Moving Average Trend Tracking StrategyPine Script · Trend following · 2h