Strategy vault / Trend following
TrendSync Pro SMC Multi Timeframe Trend Following Strategy
TrendSync Pro (SMC) is a quantitative trading strategy based on a Higher Timeframe (HTF) filter and trend momentum, designed to capture strong market trend movements. The strategy provides traders with a systematic…
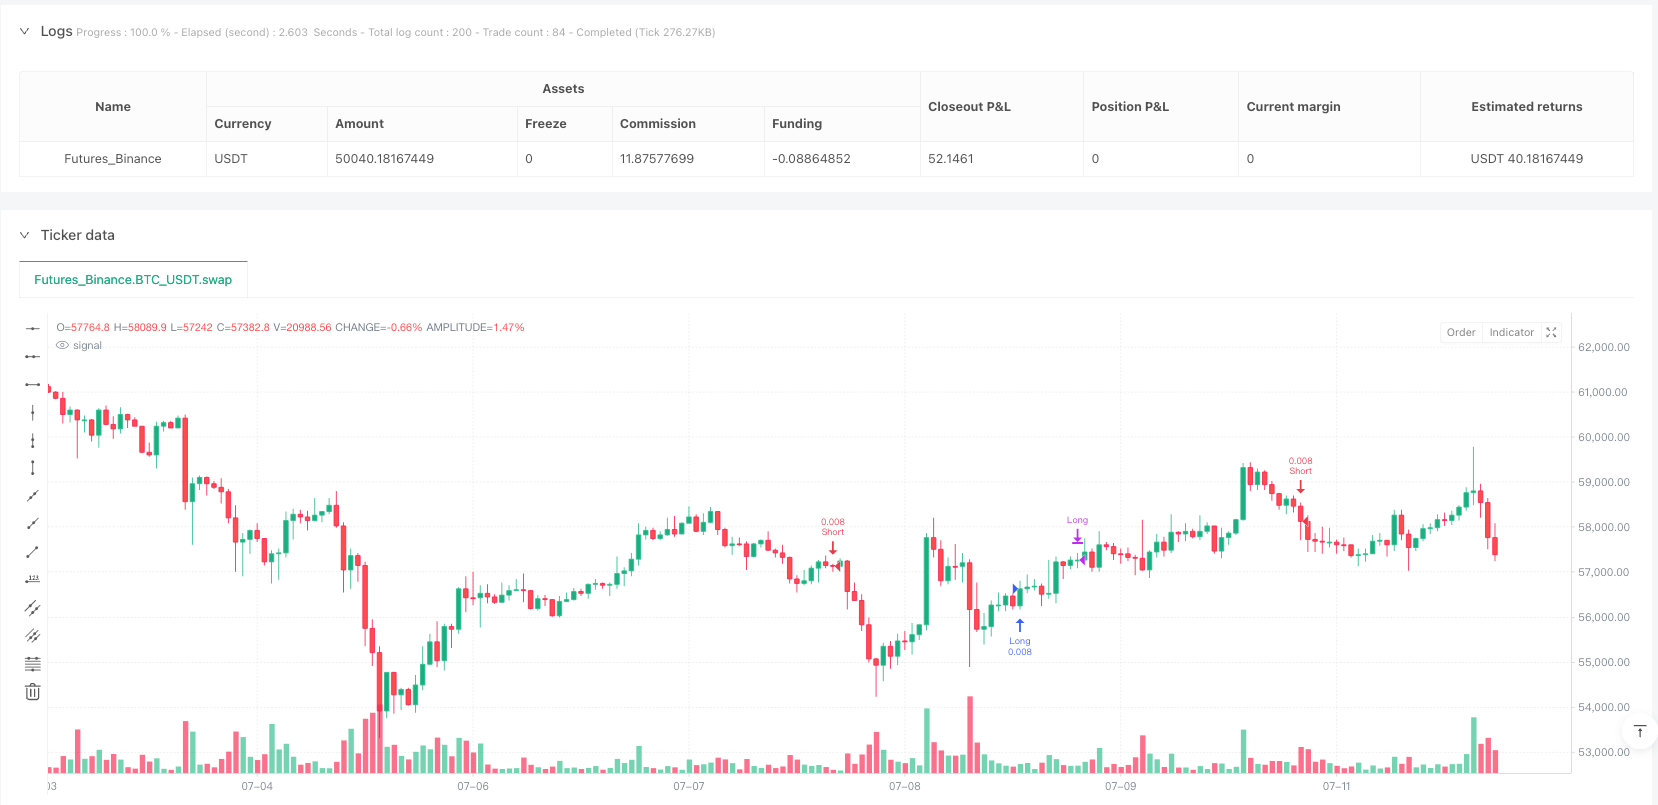
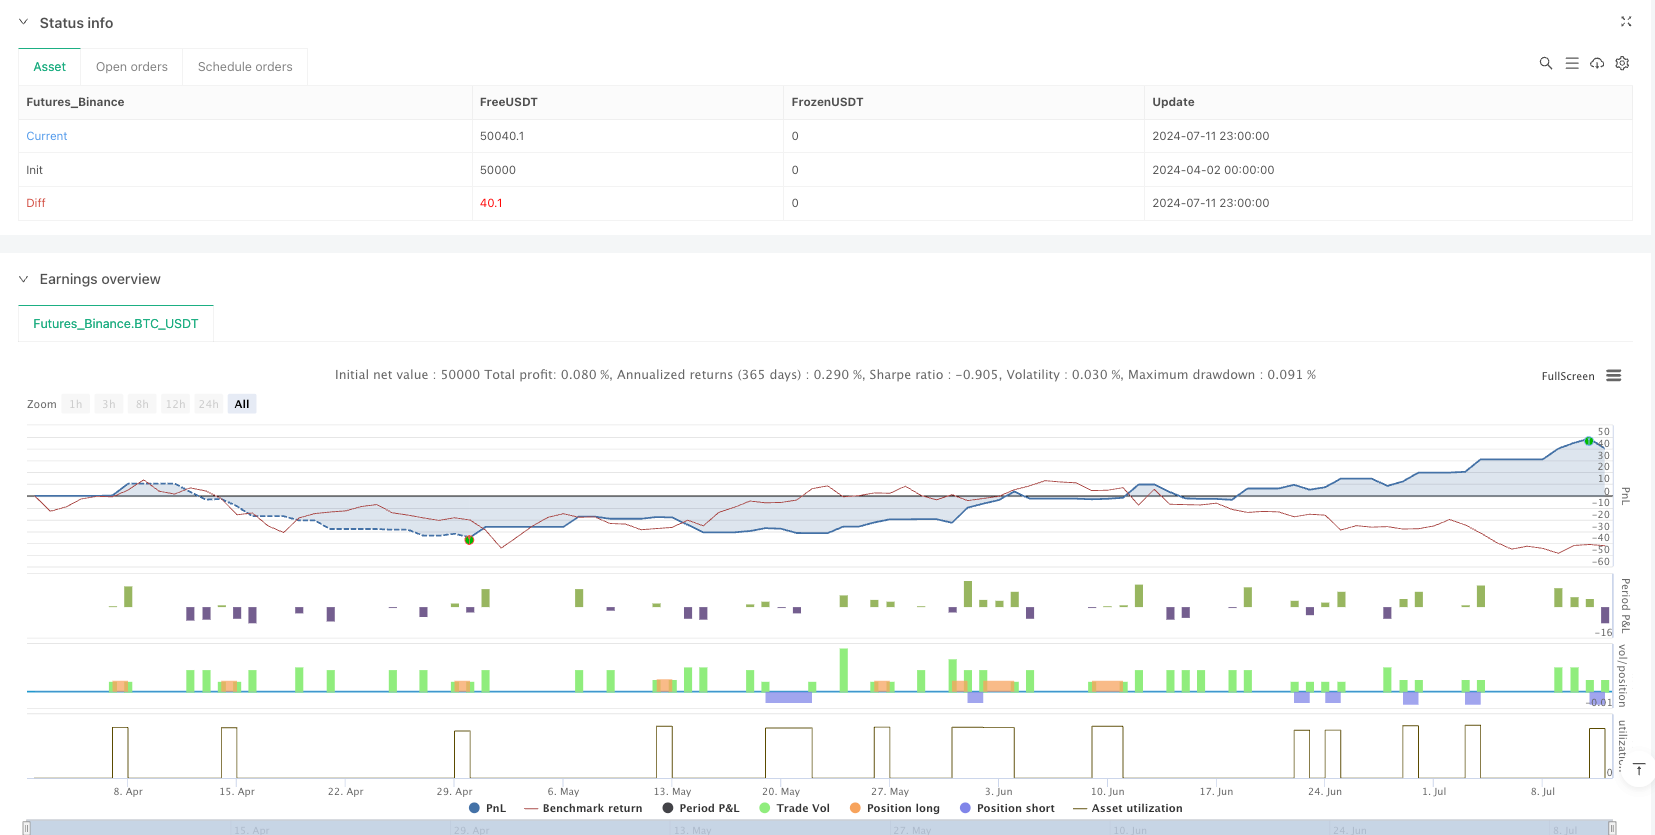
Overview
TrendSync Pro (SMC) is a quantitative trading strategy based on a Higher Timeframe (HTF) filter and trend momentum, designed to capture strong market trend movements. The strategy provides traders with a systematic trading approach by combining multi-timeframe analysis, trend line detection, and strict risk management.
Strategy Principles
The core principles of the strategy include the following key components:
Higher Timeframe (HTF) Filter: Use higher-level timeframes (such as 1-hour, 4-hour, or daily) to confirm the overall market trend direction, ensuring trades align with the primary trend.
Trend Line Detection: Dynamically identify market trend direction by analyzing key turning points (pivot highs and lows) and visualize trend lines.
Entry and Exit Logic:
- Long Entry Conditions: Price breaks above trend value with HTF trend upward
- Short Entry Conditions: Price breaks below trend value with HTF trend downward
Risk Management:
- Fixed Stop Loss: Set at 1% of entry price
- Take Profit Target: Set at 10% of entry price
- Optional dynamic stop loss using ATR (Average True Range)
Strategy Advantages
Multi-Timeframe Confirmation: Combining different timeframes reduces the probability of false signals.
Trend Following: Focus on capturing strong trending market movements rather than frequent, low-quality trades.
Strict Risk Management:
- Small stop loss (1%) protects capital
- High risk-reward ratio (1:10)
- Profitable even with a 50% win rate
Flexibility: Adjustable higher timeframe settings for different trading types (scalping, day trading, swing trading)
Visual Assistance: Provides trend line drawing to help traders intuitively understand market trends.
Strategy Risks
Market Condition Limitations:
- Poor performance in ranging or non-trending markets
- Ineffective in low volatility environments
Parameter Sensitivity:
- Trend period and higher timeframe selection directly impact strategy performance
- Requires parameter adjustments for different markets and trading instruments
Stop Loss Risks:
- Fixed 1% stop loss might be too tight in high volatility markets
- Increased likelihood of being "stopped out"
Strategy Optimization Directions
Dynamic Stop Loss:
- Introduce ATR-based dynamic stop loss methods
- Adjust stop loss range based on market volatility
Filter Enhancement:
- Integrate volume analysis
- Incorporate liquidity sweeps
- Add order block confirmation
Multi-Strategy Combination:
- Combine with ICT Power of 3 method
- Integrate VWAP and market profile analysis
- Incorporate liquidation heatmap (especially in crypto markets)
Machine Learning Optimization:
- Use machine learning algorithms to optimize parameter selection
- Develop adaptive parameter adjustment mechanisms
Summary
TrendSync Pro (SMC) is a strategy that prioritizes quality over quantity. By providing multi-timeframe confirmation, strict risk management, and trend-following logic, the strategy offers traders a systematic trading framework. The key is selective trading - capturing just 1-2 high-quality trade opportunities per day, rather than frequent but inefficient trading.
Source Pine Script
/*backtest
start: 2024-04-02 00:00:00
end: 2024-07-12 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy('TrendSync Pro (SMC)', overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=1)

// Created by Shubham Singh

// Inputs
bool show_trendlines = input.bool(true, "Show Trendlines", group="Visual Settings")
int trend_period = input(20, 'Trend Period', group="Strategy Settings")
string htf = input.timeframe("60", "Higher Timeframe", group="Strategy Settings")

// Risk Management
float sl_percent = input.float(1.0, "Stop Loss (%)", minval=0.1, maxval=10, step=0.1, group="Risk Management")
float tp_percent = input.float(2.0, "Take Profit (%)", minval=0.1, maxval=10, step=0.1, group="Risk Management")

// Created by Shubham Singh

// Trendline Detection
var line trendline = na
var float trend_value = na
var bool trend_direction_up = false  // Initialize with default value

pivot_high = ta.pivothigh(high, trend_period, trend_period)
pivot_low = ta.pivotlow(low, trend_period, trend_period)

if not na(pivot_high)
    trend_value := pivot_high
    trend_direction_up := false


if not na(pivot_low)
    trend_value := pivot_low
    trend_direction_up := true


// Created by Shubham Singh

// Higher Timeframe Filter
htf_close = request.security(syminfo.tickerid, htf, close)
htf_trend_up = htf_close > htf_close[1]
htf_trend_down = htf_close < htf_close[1]

// Trading Logic
long_condition = ta.crossover(close, trend_value) and htf_trend_up and trend_direction_up
short_condition = ta.crossunder(close, trend_value) and htf_trend_down and not trend_direction_up
// Created by Shubham Singh

// Entry/Exit with SL/TP
if strategy.position_size == 0
    if long_condition
        strategy.entry("Long", strategy.long)
        strategy.exit("Long Exit", "Long", stop=close*(1-sl_percent/100), limit=close*(1+tp_percent/100))

    if short_condition
        strategy.entry("Short", strategy.short)
        strategy.exit("Short Exit", "Short", stop=close*(1+sl_percent/100), limit=close*(1-tp_percent/100))
// Created by Shubham Singh

// Manual Trendline Exit
if strategy.position_size > 0 and ta.crossunder(close, trend_value)
    strategy.close("Long")
if strategy.position_size < 0 and ta.crossover(close, trend_value)
strategy.close("Short")Published by ianzeng123 on the FMZ strategy square · last modified 2025-04-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/TrendSync-Pro-SMC-Multi-Timeframe-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- VWAP Moving Average Crossover with Dynamic ATR Stop Loss and Take Profit StrategyPine Script · Trend following · 1d
- Multi Dimensional Technical Indicator Composite Trend Tracking Quantitative Trading StrategyPine Script · Trend following · 5m
- Super Trend V StrategyPine Script · Trend following · 1d
- Trend Confirmation Tracking StrategyPine Script · Trend following · 1h