Triple EMA Crossover Breakout Strategy
The Triple EMA Crossover Breakout strategy uses triple exponential moving average (EMA) indicators to determine market trend direction and enter at trend breakout points. It also combines candlestick patterns to…
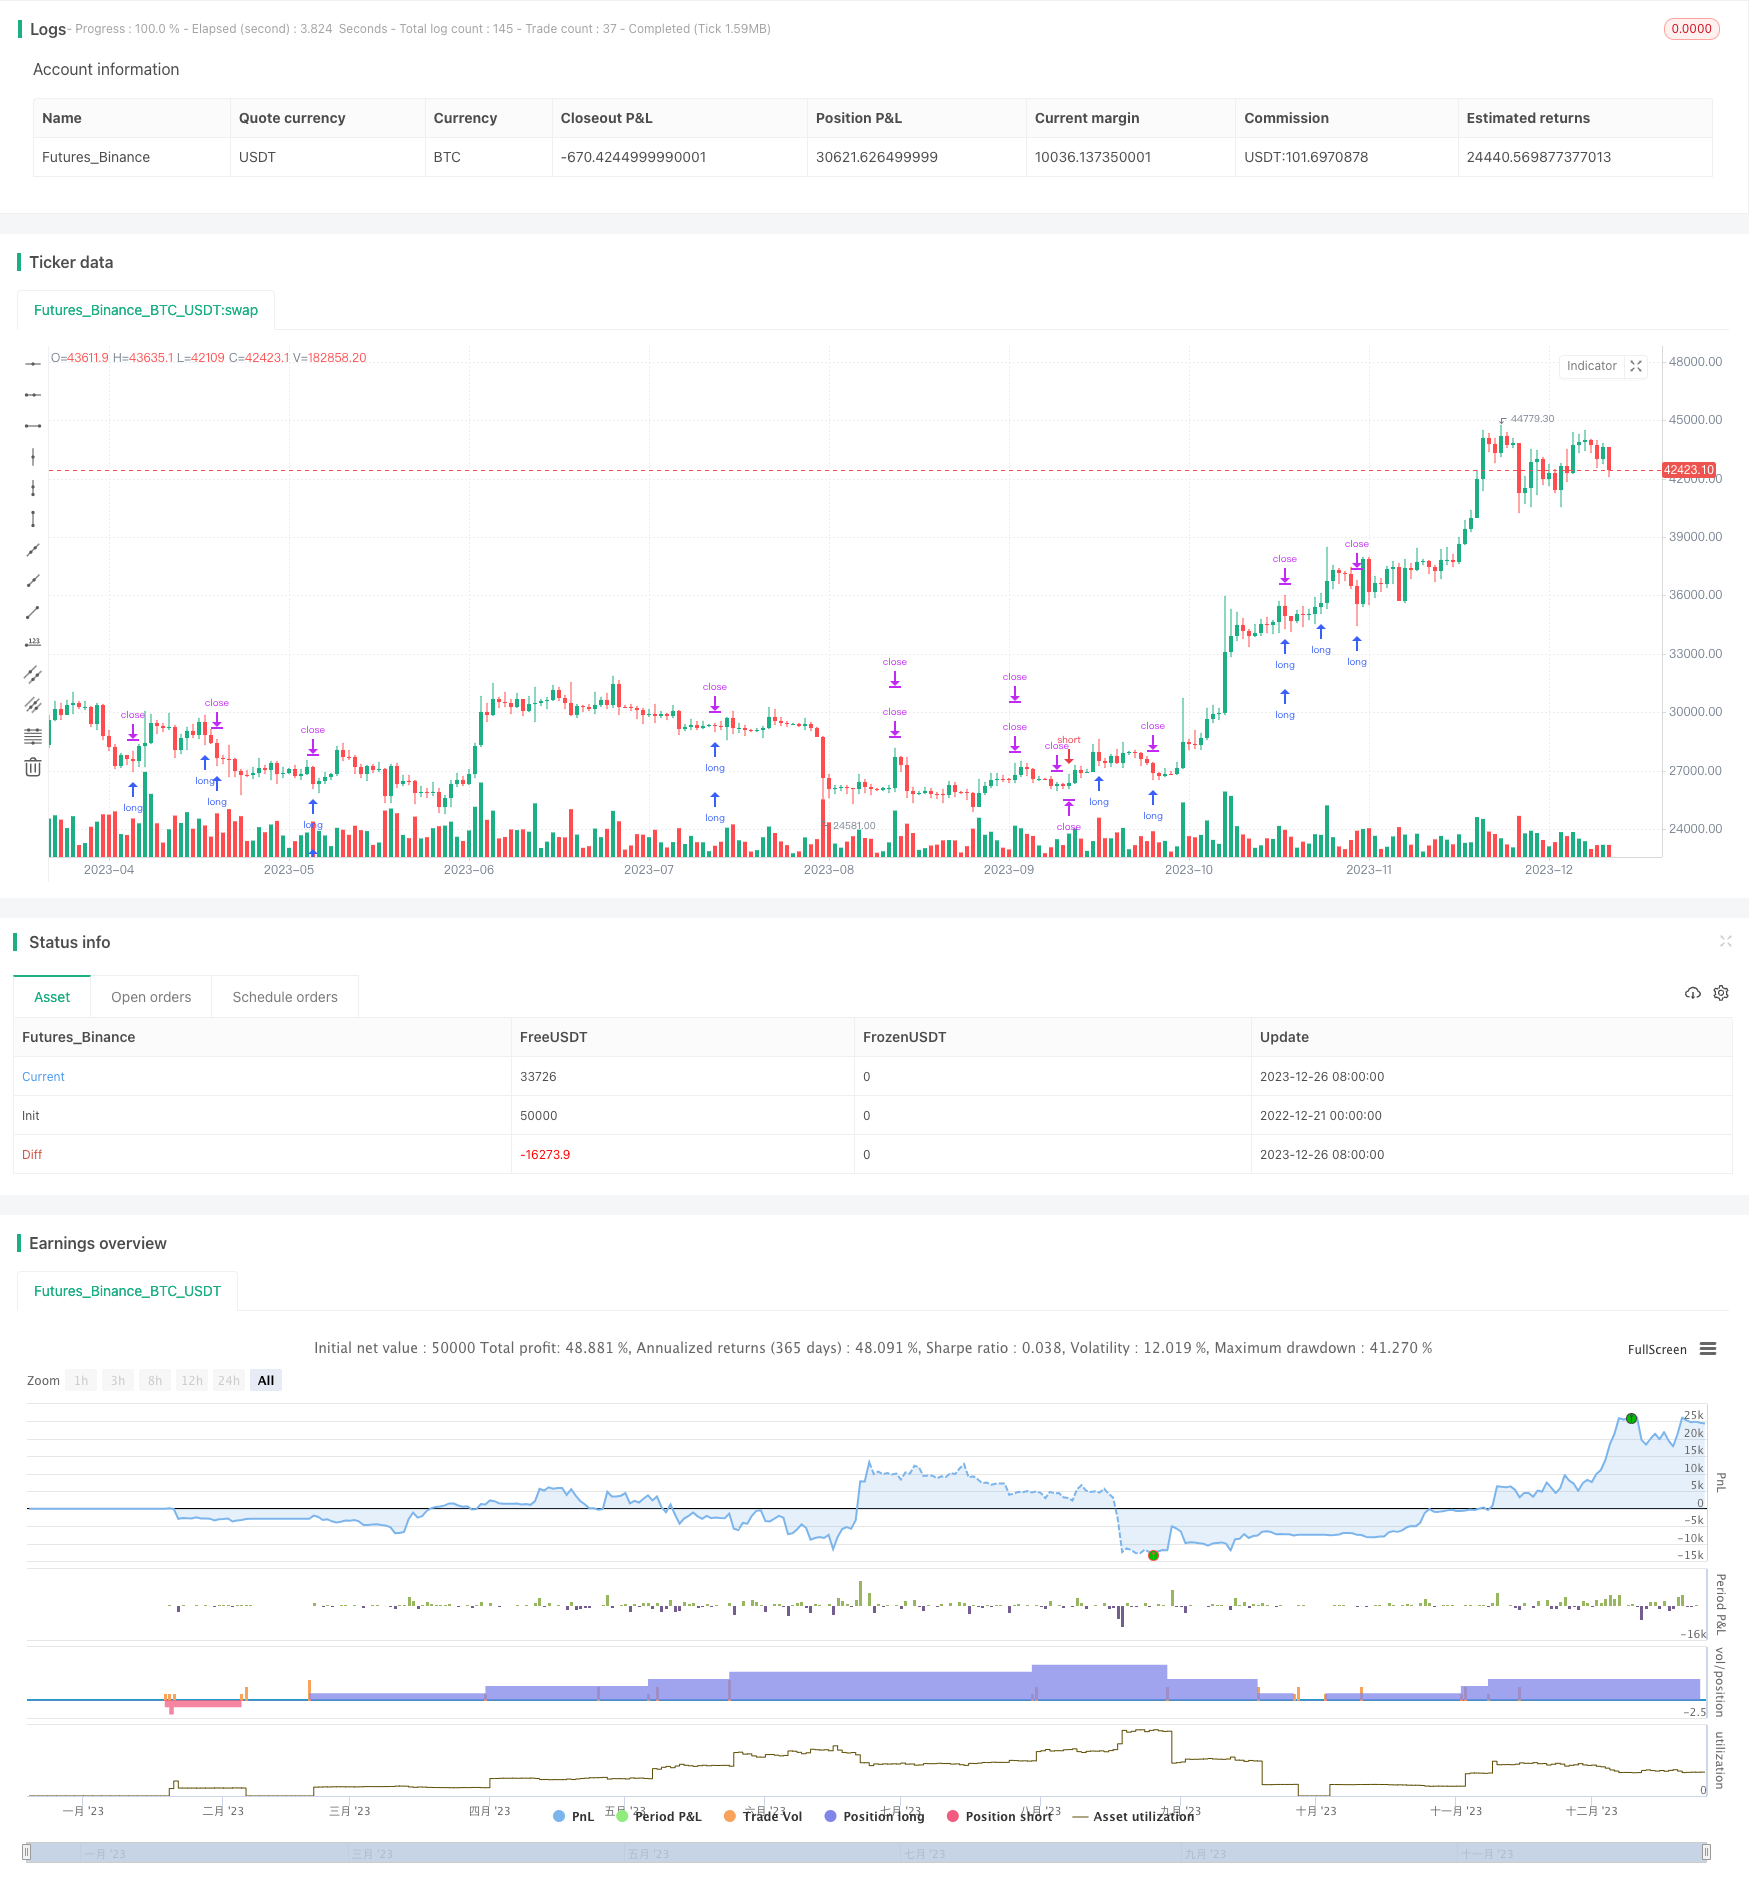
Overview
The Triple EMA Crossover Breakout strategy uses triple exponential moving average (EMA) indicators to determine market trend direction and enter at trend breakout points. It also combines candlestick patterns to filter signal reliability.
Strategy Logic
The strategy is mainly based on the following principles:
Use three EMAs with different periods (200-day, 50-day, 20-day) to determine major, medium-term and short-term market trends.
When the short-term EMA (20-day) crosses above the medium-term EMA (50-day), a buy signal is generated. When it crosses below, a sell signal is generated.
Combine candlestick patterns to check signal reliability. Only when the closing price of the second candle is higher (lower) than the previous candle's high (low) price, the breakout is considered reliable.
Set stop loss and take profit levels to limit risks beyond reasonable price fluctuations.
Advantage Analysis
Using multiple EMAs improves trend judgment accuracy.
Filtering fake signals with candlestick patterns avoids unnecessary trading risks.
Stop loss and take profit controls single trade loss effectively.
Risk Analysis
In ranging markets, EMAs may generate excessive fake signals and fail to determine market direction.
The single indicator system has limited capacity in complex market situations.
It ignores trading costs which could lead to unprofitability in high-fee markets.
Optimization
Introduce other indicators like MACD and KDJ to form a combined system and improve judgment accuracy.
Optimize parameters through backtesting for specific symbols and timeframes to make the strategy fit better.
Add trading volume to avoid low-volume fake signals.
Conclusion
The Triple EMA Crossover Breakout Strategy has clear, easy-to-understand logic to determine market trends and find entry timing using EMA crossovers. But it also has some limitations in dealing with complex market situations. It's recommended to combine with other indicators and optimize parameters to adapt to more diverse trading environments.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0.5 | ENTRY LEVEL 1 |
| v_input_2 | 0.25 | ENTRY LEVEL 2 |
| v_input_3 | false | ENTRY LEVEL 3 |
| v_input_4 | -0.35 | STOP LEVEL |
| v_input_5 | 0.88 | TP LEVEL |
| v_input_6 | false | Don't Use EMA |
Source Pine Script
/*backtest
start: 2022-12-21 00:00:00
end: 2023-12-27 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("GHG RETRACEMENT MODE 1", overlay=true)

entryLevel1 = input(0.5, "ENTRY LEVEL 1")
entryLevel2 = input(0.25, "ENTRY LEVEL 2")
entryLevel3 = input(0.0, "ENTRY LEVEL 3")

stopLevel = input(-0.35, "STOP LEVEL")
tpLevel = input(0.88, "TP LEVEL")
dontUseEma = input(false, "Don't Use EMA")


get_level(level, level100, level0) =>
    level * (level100 - level0) + level0

buySignal = close[2] < open[2] and close[1] > open[1] and close[0] > open[0] and high[0] > open[2] and high[1] < high[2]
sellSignal = close[2] > open[2] and close[1] < open[1] and close[0] < open[0] and low[0] < open[2] and low[1] > low[2]

if buySignal and (close[0] > ta.ema(close, 200) or dontUseEma)
    l = label.new(bar_index, na)
    entryPrice1 = get_level(entryLevel1, high[0], low[2])
    entryPrice2 = get_level(entryLevel2, high[0], low[2])
    entryPrice3 = get_level(entryLevel3, high[0], low[2])

    exitPrice = get_level(tpLevel, high[0], low[2])
    stopPrice = get_level(stopLevel, high[0], low[2])

    strategy.order("BUY 1", strategy.long, comment="BUY 1", limit=entryPrice1)
    strategy.exit("exit", "BUY 1", limit=high[0], stop=stopPrice)
    strategy.order("BUY 2", strategy.long, comment="BUY 2", limit=entryPrice2)
    strategy.exit("exit", "BUY 2", limit=high[0], stop=stopPrice)

    label.set_text(l, "Buy => " + str.tostring(close[2]) + "\nSL=> " + str.tostring(stopPrice) + "\nTP => " + str.tostring(exitPrice) )
    label.set_color(l, color.green)
    label.set_yloc(l, yloc.belowbar)
    label.set_style(l, label.style_label_up)

if sellSignal and (close[0] < ta.ema(close, 200) or dontUseEma)
    a = label.new(bar_index, na)
    entryPrice1 = get_level(entryLevel1, low[0], high[2])
    entryPrice2 = get_level(entryLevel2, low[0], high[2])
    entryPrice3 = get_level(entryLevel3, low[0], high[2])

    exitPrice = get_level(tpLevel, low[0], high[2])
    stopPrice = get_level(stopLevel,low[0], high[2])

    strategy.order("SELL 1", strategy.short, comment="SELL 1", limit=entryPrice1)
    strategy.exit("exit", "SELL 1", limit=low[0], stop=stopPrice)
    strategy.order("SELL 2", strategy.short, comment="SELL 2", limit=entryPrice2)
    strategy.exit("exit", "SELL 2", limit=low[0], stop=stopPrice)

    label.set_text(a,"Sell => " + str.tostring(close[2]) + "\nSL=> " + str.tostring(stopPrice) + "\nTP => " + str.tostring(exitPrice) )
    label.set_color(a, color.red)
    label.set_yloc(a, yloc.abovebar)
    label.set_style(a, label.style_label_down)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Triple-EMA-Crossover-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Dual Moving Average Breakthrough StrategyPine Script · Breakout · 1d
- EMA MACD Quantitative Strategy With Dual Track Running and Leading the Market IndexPine Script · Breakout · 1d
- Kana Candle Breakout Strategy Based on Moving Average and Support ResistancePine Script · Breakout · 1h
- MA Trendline Breakthrough StrategyPine Script · Breakout · 1d