Strategy vault / Machine learning
Triple Exponential Moving Average Profit Taking and Stop Loss Strategy
The Triple Exponential Moving Average Profit Taking and Stop Loss Strategy is a trend-following strategy based on three exponential moving averages with different periods for market entry and exit. It also uses the…
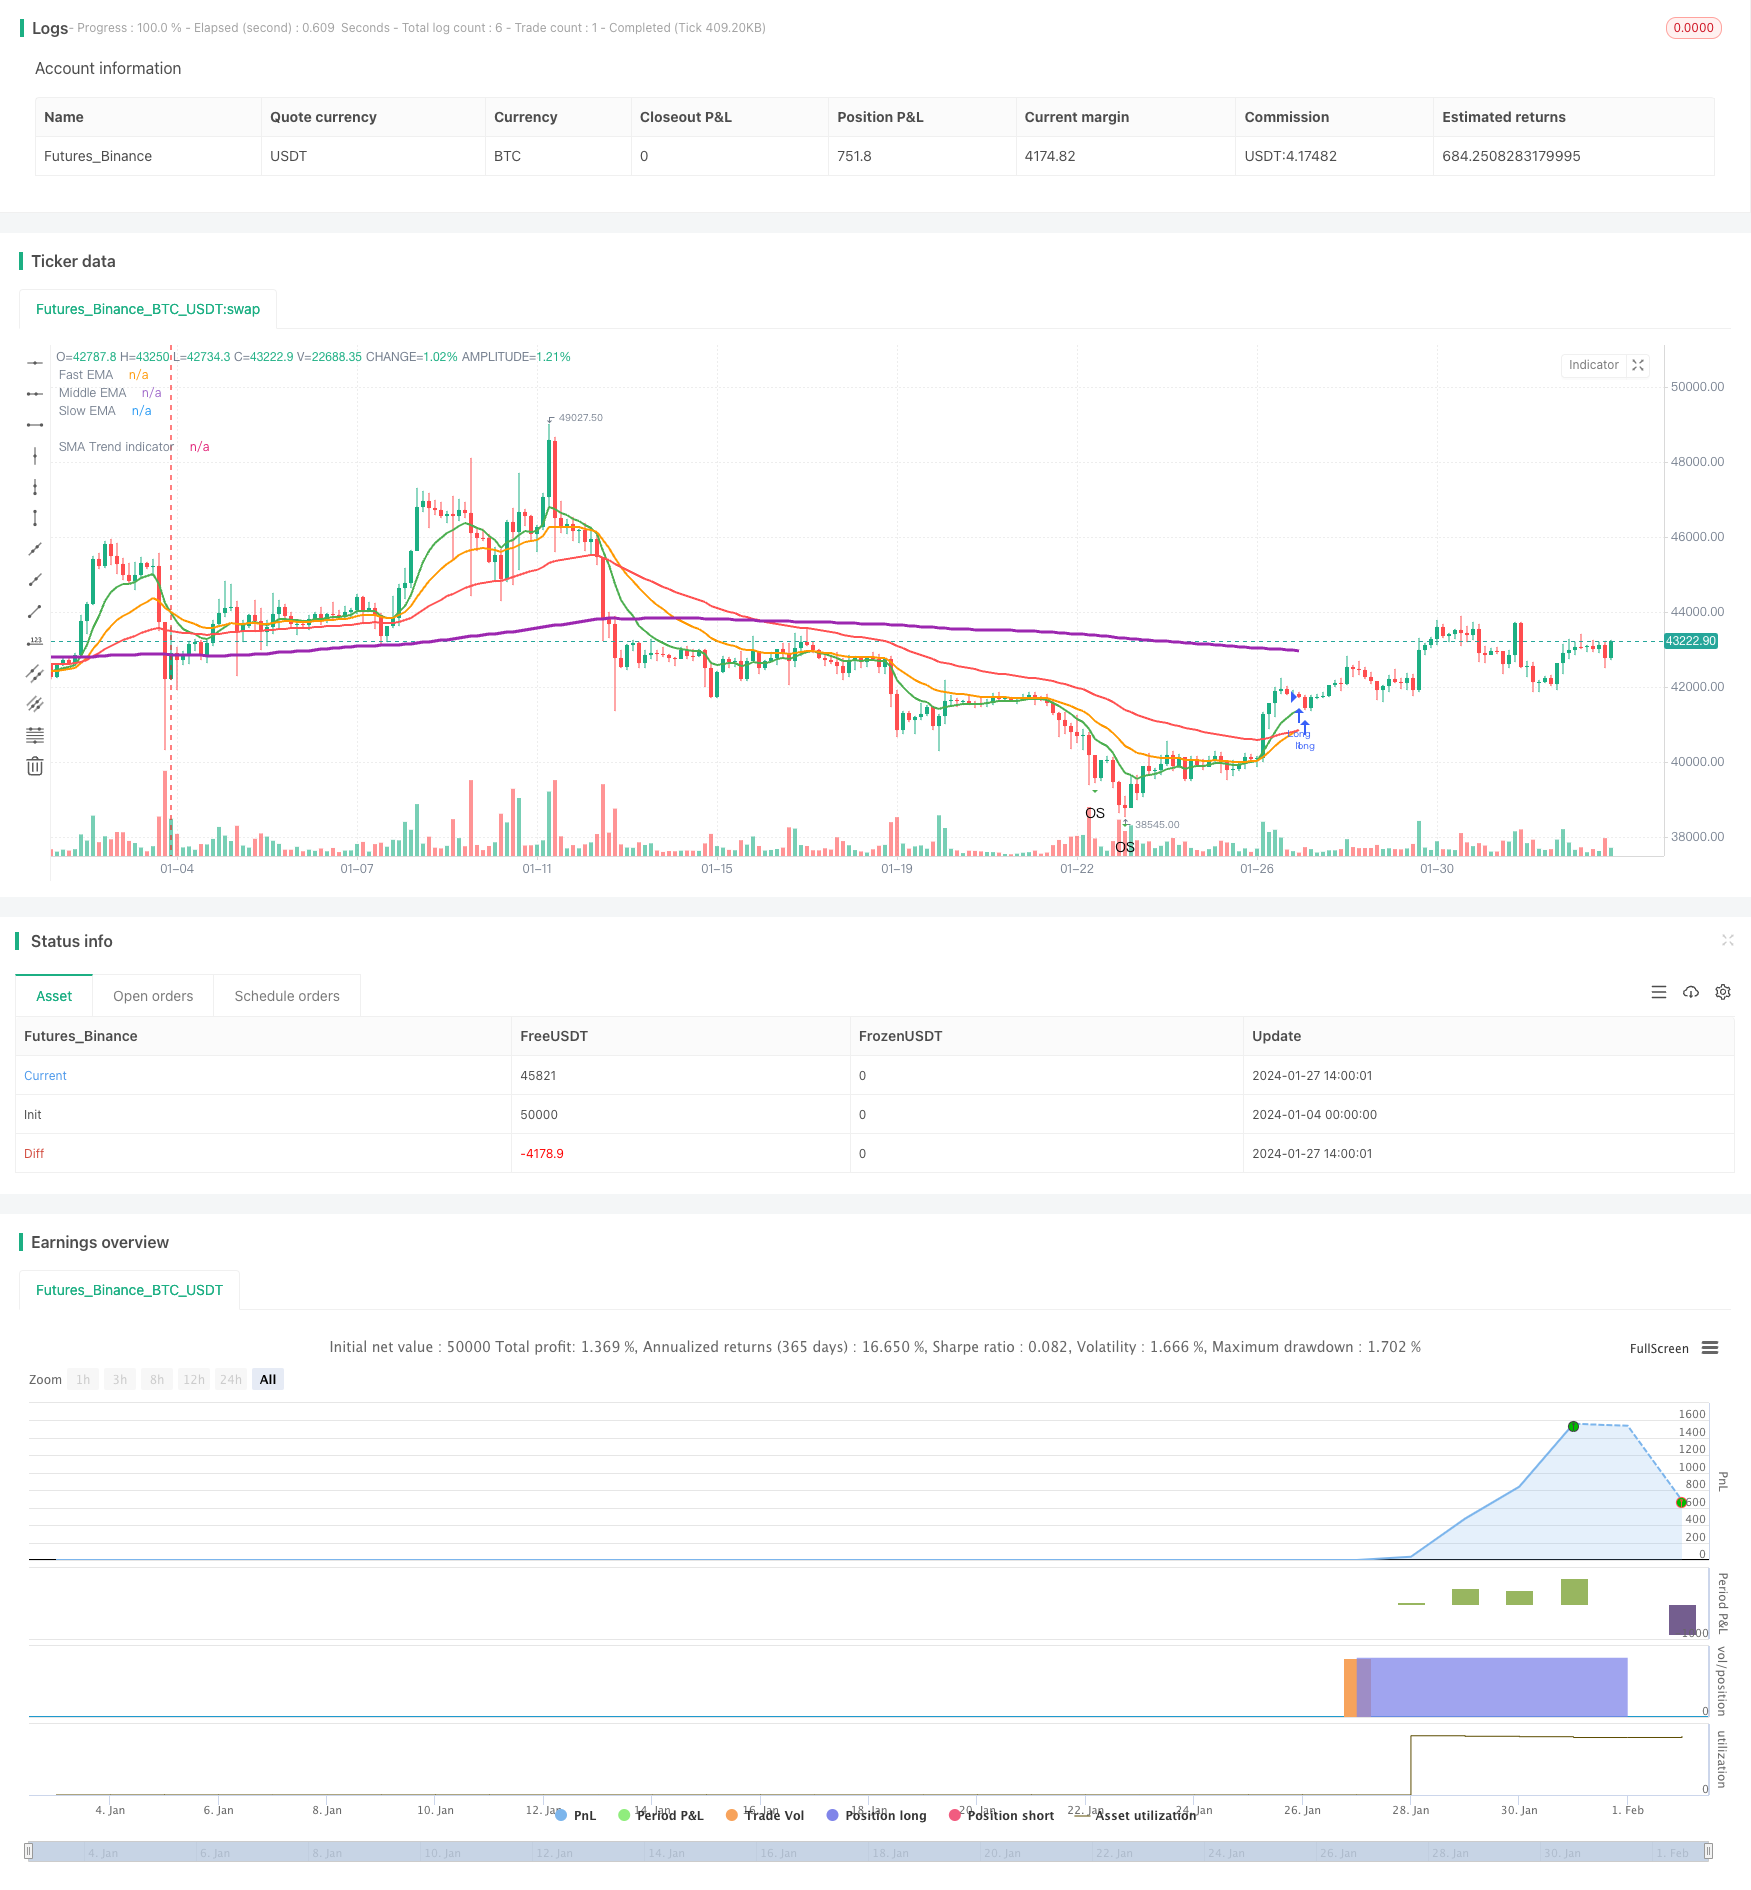
Overview
The Triple Exponential Moving Average Profit Taking and Stop Loss Strategy is a trend-following strategy based on three exponential moving averages with different periods for market entry and exit. It also uses the Average True Range indicator to set profit-taking and stop-loss levels for risk management.
Strategy Logic
The strategy uses three exponential moving averages: fast line, middle line, and slow line. It goes long when the middle line crosses above the slow line, and closes position when the fast line crosses below the middle line. This is a typical trend-following strategy that determines trend directionality through the crossing of the three moving averages.
At the same time, the strategy leverages the Average True Range indicator to calculate profit-taking and stop-loss levels. Specifically, the take profit for long positions is entry price + Average True Range * profit factor, and for short positions it is entry price - Average True Range * profit factor. The stop loss logic is similar. This effectively limits the risk of large losses.
Advantage Analysis
- Decision indicators are intuitive and easy to understand.
- Systematic and easy to automate.
- Balances trend-following and risk control.
Risk Analysis
- There is some lag and inability to timely capture reversals.
- Prone to stop loss in ranging markets.
- Parameter tuning needs optimization, otherwise results may be poor.
Risk mitigation measures include: shortening moving average periods, optimizing profit/stop factor, and adding auxiliary indicators.
Optimization Directions
- Test combinations of moving averages to find optimal parameters.
- Add other technical indicators like MACD, RSI etc.
- Use machine learning to auto optimize parameters.
- Dynamically adjust profit/stop level based on true range.
- Incorporate sentiment to avoid overcrowding.
Conclusion
Overall this is an effective trend-following strategy with stable performance and easy implementation via simple parameters. The dynamic profit taking and stop loss based on Average True Range limits per-side risk. But parameter optimization and indicator combinations need to be done carefully to prevent overfitting or decision lag. On balance, this strategy has good risk-reward profile and is worth considering.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | timestamp(01 Jan 2017 00:00 +0000) | Start Time |
| v_input_2 | timestamp(01 Jan 2022 00:00 +0000) | End Time |
| v_input_3 | 55 | Slow EMA Length |
| v_input_4 | 21 | Middle EMA Length |
| v_input_5 | 9 | Fast EMA Length |
| v_input_6 | 200 | Trend indicator MA Length |
| v_input_7 | 14 | ATR Length |
| v_input_8 | 3 | Take profit ATR multiplier |
| v_input_9 | 2 | Stop loss ATR multiplier |
| v_input_10 | 14 | RSI Length |
Source Pine Script
/*backtest
start: 2024-01-04 00:00:00
end: 2024-02-03 00:00:00
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//© Densz
strategy("3EMA with TP & SL (ATR)", overlay=true )

// INPUTS
startTime           =       input(title="Start Time", type = input.time, defval = timestamp("01 Jan 2017 00:00 +0000"))
endTime             =       input(title="End Time", type = input.time, defval = timestamp("01 Jan 2022 00:00 +0000"))

slowEMALength       =       input(title="Slow EMA Length", type = input.integer, defval = 55)
middleEMALength     =       input(title="Middle EMA Length", type = input.integer, defval = 21)
fastEMALength       =       input(title="Fast EMA Length", type = input.integer, defval = 9)

trendMALength       =       input(title="Trend indicator MA Length", type = input.integer, defval = 200)

atrLength           =       input(title="ATR Length", type = input.integer, defval = 14)
tpATRMult           =       input(title="Take profit ATR multiplier", type = input.integer, defval = 3)
slATRMult           =       input(title="Stop loss ATR multiplier", type = input.integer, defval = 2)

rsiLength           =       input(title="RSI Length", type = input.integer, defval = 14)

// Indicators
slowEMA             =       ema(close, slowEMALength)
middEMA             =       ema(close, middleEMALength)
fastEMA             =       ema(close, fastEMALength)
atr                 =       atr(atrLength)

rsiValue            =       rsi(close, rsiLength)
isRsiOB             =       rsiValue >= 80
isRsiOS             =       rsiValue <= 20

sma200              =       sma(close, trendMALength)

inDateRange         =       true

// Plotting
plot(slowEMA, title="Slow EMA", color=color.red, linewidth=2, transp=50)
plot(middEMA, title="Middle EMA", color=color.orange, linewidth=2, transp=50)
plot(fastEMA, title="Fast EMA", color=color.green, linewidth=2, transp=50)

plot(sma200, title="SMA Trend indicator", color=color.purple, linewidth=3, transp=10)
plotshape(isRsiOB, title="Overbought", location=location.abovebar, color=color.red, transp=0, style=shape.triangledown, text="OB")
plotshape(isRsiOS, title="Oversold", location=location.belowbar, color=color.green, transp=0, style=shape.triangledown, text="OS")

float takeprofit    =       na
float stoploss      =       na

var line tpline     =       na
var line slline     =       na

if strategy.position_size != 0
    takeprofit := takeprofit[1]
    stoploss := stoploss[1]
    line.set_x2(tpline, bar_index)
    line.set_x2(slline, bar_index)
    line.set_extend(tpline, extend.none)
    line.set_extend(slline, extend.none)

// STRATEGY
goLong  = crossover(middEMA, slowEMA) and inDateRange
closeLong = crossunder(fastEMA, middEMA) and inDateRange


if goLong
    takeprofit := close + atr * tpATRMult
    stoploss := close - atr * slATRMult
    // tpline := line.new(bar_index, takeprofit, bar_index, takeprofit, color=color.green, width=2, extend=extend.right, style=line.style_dotted)
    // slline := line.new(bar_index, stoploss, bar_index, stoploss, color=color.red, width=2, extend=extend.right, style=line.style_dotted)
    // label.new(bar_index, takeprofit, "TP", style=label.style_labeldown)
    // label.new(bar_index, stoploss, "SL", style=label.style_labelup)
    strategy.entry("Long", strategy.long, when = goLong)
    strategy.exit("TP/SL", "Long", stop=stoploss, limit=takeprofit)
if closeLong
    takeprofit := na
    stoploss := na
    strategy.close(id = "Long", when = closeLong)

if (not inDateRange)
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Triple-Exponential-Moving-Average-Profit-Taking-and-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Dynamic Adaptive Quantitative Trading StrategyPine Script · Machine learning · 1h
- ADX EFI 50 Moving Average Channel Pullback StrategyPine Script · Machine learning · 1h
- Multi indicator Combination StrategyPine Script · Machine learning · 1d
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- MACD Robot Trading StrategyPine Script · Machine learning · 1d