Triple Moving Average Trend Following and Momentum Integration Quantitative Trading Strategy
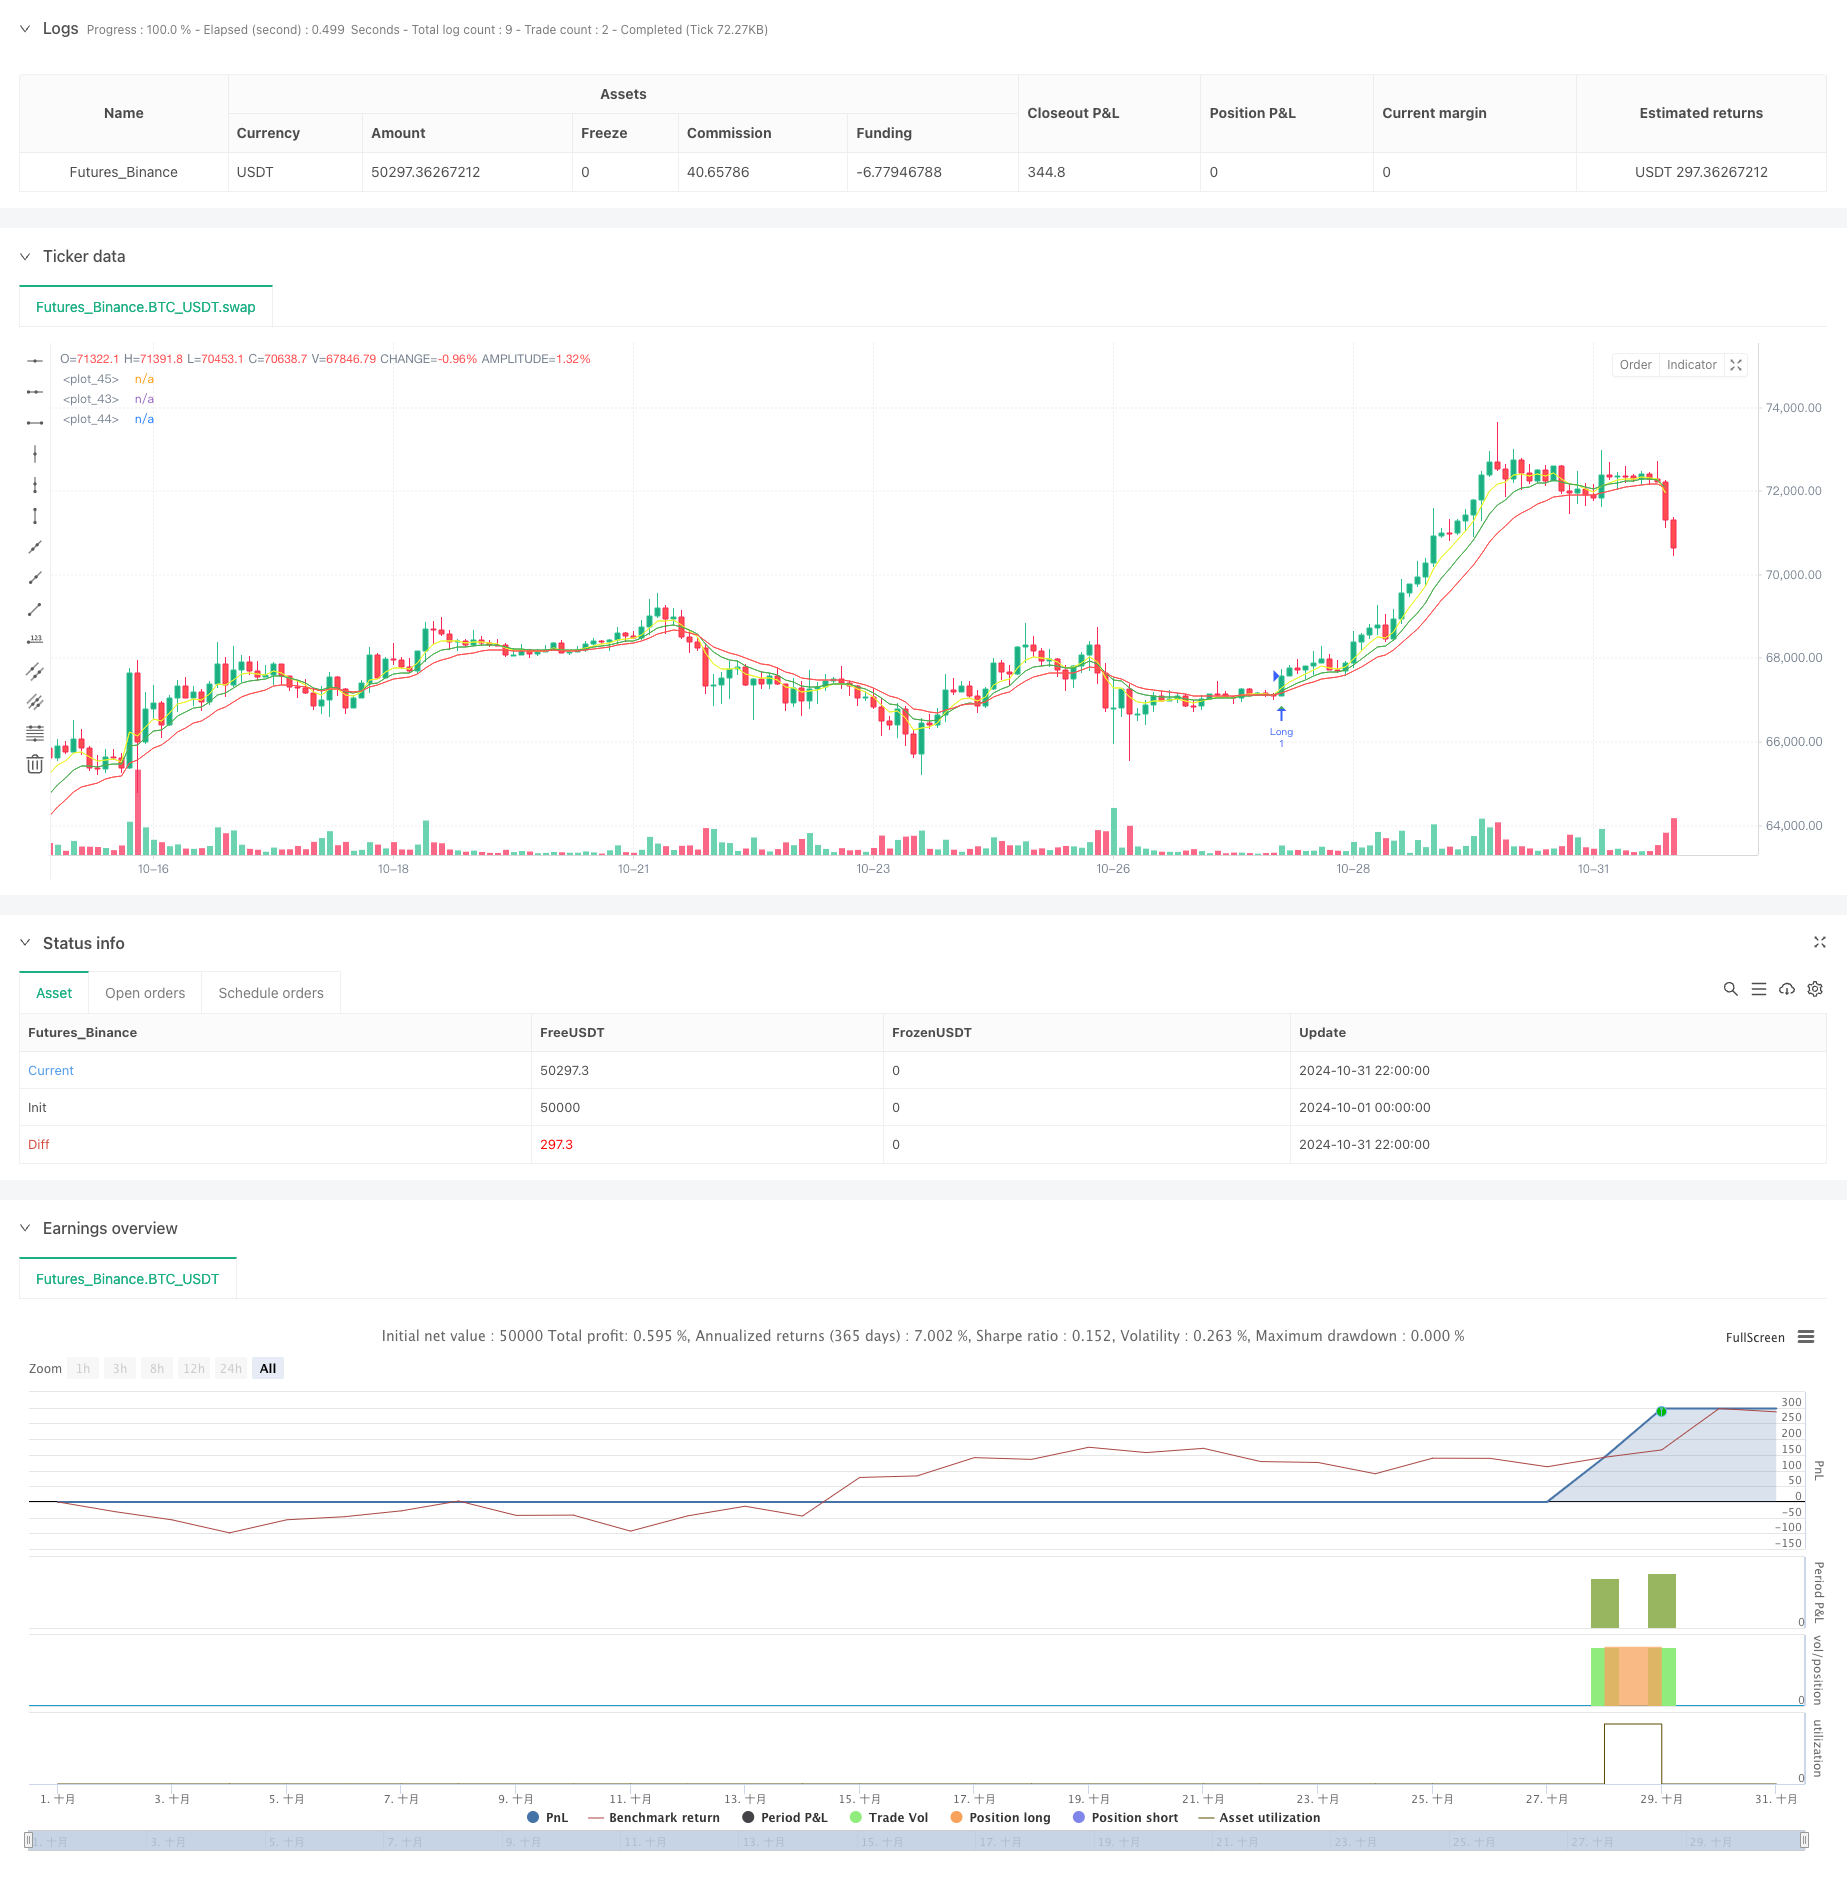
This is a quantitative trading strategy that combines trend following and momentum analysis. The strategy utilizes Triple Exponential Moving Average (TEMA), multiple moving average crossovers, and a MACD variant to…
Overview
This is a quantitative trading strategy that combines trend following and momentum analysis. The strategy utilizes Triple Exponential Moving Average (TEMA), multiple moving average crossovers, and a MACD variant to identify market trends and entry points. It implements strict risk control mechanisms, including fixed stop-loss, profit targets, and trailing stops to optimize risk-reward balance.
Strategy Principles
The strategy determines trading signals through three core technical indicator systems:
- Triple Exponential Moving Average (TEMA) system confirms overall trend direction. It calculates three layers of EMA and combines their dynamic changes to judge trend strength.
- Fast/Slow MA crossover system uses 9-period and 15-period EMAs to capture medium-term trend reversal points.
- Price crossing with 5-period EMA serves as final confirmation signal for precise entry timing.
Trade signals are triggered when all conditions are met:
- MACD crosses above its signal line with upward TEMA trend
- Short-term EMA crosses above long-term EMA
- Price crosses above 5-period EMA
Strategy Advantages
- Multiple confirmation mechanisms greatly reduce false signals and improve trading accuracy.
- Combines benefits of trend following and momentum analysis to capture both major trends and short-term opportunities.
- Implements comprehensive stop-loss mechanisms including fixed stops and dynamic trailing stops for effective risk control.
- High parameter adaptability for different market environments.
- Clear entry logic that's easy to understand and execute.
Strategy Risks
- Multiple confirmation requirements may lead to delayed entries, missing opportunities in fast-moving markets.
- Fixed stop-loss points need adjustment for different market volatilities to avoid premature exits.
- May generate frequent false signals in range-bound, choppy markets.
- Trailing stops might exit quality trends too early during severe market fluctuations.
Optimization Directions
- Introduce volatility indicators for dynamic adjustment of stops and profit targets to better match market conditions.
- Add volume indicators as auxiliary confirmation to improve signal reliability.
- Implement market environment recognition for different parameter combinations in various market states.
- Develop counter-trend position building mechanism for moderate accumulation during pullbacks.
- Optimize trailing stop algorithm for better adaptation to market volatility.
Summary
The strategy builds a robust trading system by integrating multiple technical indicator systems. Its core strengths lie in multiple confirmation mechanisms and comprehensive risk control systems. While there are certain lag risks, the strategy has significant improvement potential through parameter optimization and functional expansion. Suitable for traders seeking stable returns.
Source Pine Script
/*backtest
start: 2024-10-01 00:00:00
end: 2024-10-31 23:59:59
period: 2h
basePeriod: 2h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("ITG Scalper Strategy", shorttitle="lokesh_ITG_Scalper_Strategy", overlay=true)

// General inputs
len = input(14, title="TEMA period")
FfastLength = input.int(13, title="Filter fast length")
FslowLength = input.int(18, title="Filter slow length")
FsignalLength = input.int(14, title="Filter signal length")
sl_points = 7 // 5 points stop loss
tp_points = 100 // 100 points target profit
trail_points = 15 // Trailing stop loss every 10 points

// Validate input
if FfastLength < 1
    FfastLength := 1
if FslowLength < 1
    FslowLength := 1
if FsignalLength < 1
    FsignalLength := 1

// Get real close price
realC = close

// Triple EMA definition
ema1 = ta.ema(realC, len)
ema2 = ta.ema(ema1, len)
ema3 = ta.ema(ema2, len)

// Triple EMA trend calculation
avg = 3 * (ema1 - ema2) + ema3

// Filter formula
Fsource = close
FfastMA = ta.ema(Fsource, FfastLength)
FslowMA = ta.ema(Fsource, FslowLength)
Fmacd = FfastMA - FslowMA
Fsignal = ta.sma(Fmacd, FsignalLength)

// Plot EMAs for visual reference
shortema = ta.ema(close, 9)
longema = ta.ema(close, 15)
yma = ta.ema(close, 5)
plot(shortema, color=color.green)
plot(longema, color=color.red)
plot(yma, color=#e9f72c)

// Entry conditions
firstCrossover = ta.crossover(Fmacd, Fsignal) and avg > avg[1]
secondCrossover = ta.crossover(shortema, longema)  // Assuming you meant to cross shortema with longema
thirdCrossover = ta.crossover(close, yma)

var bool entryConditionMet = false

if (firstCrossover)
    entryConditionMet := true

longSignal = entryConditionMet and secondCrossover and thirdCrossover

// Strategy execution
if (longSignal)
    strategy.entry("Long", strategy.long)
    entryConditionMet := false  // Reset the entry condition after taking a trade

// Calculate stop loss and take profit prices
var float long_sl = na
var float long_tp = na

if strategy.position_size > 0  // Long position
    long_sl := close - sl_points
    long_tp := close + tp_points

    // Adjust stop loss with trailing logic
    if (close - long_sl > trail_points)
        long_sl := close - trail_points

    strategy.exit("Exit Long", "Long", stop=long_sl, limit=long_tp)

// Plotting Buy signals
plotshape(series=longSignal, style=shape.triangleup, location=location.belowbar, color=color.green, size=size.small, title="Buy Signal")

// Alerts
alertcondition(longSignal, title="Buy Signal", message="Buy Signal")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Triple-Moving-Average-Trend-Following-and-Momentum-Integration-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- MACD Momentum Indicator Backtest StrategyPine Script · Momentum · 1h
- MACD of Relative Strength StrategyPine Script · Momentum · 1d
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Multi Level Technical Indicator Momentum Trading Strategy Based on Enhanced MACD Volume Strength and EMA Signal SystemPine Script · Momentum · 1h