Strategy vault / Mean reversion
Triple Validated RSI Mean Reversion with Moving Average Filter Strategy
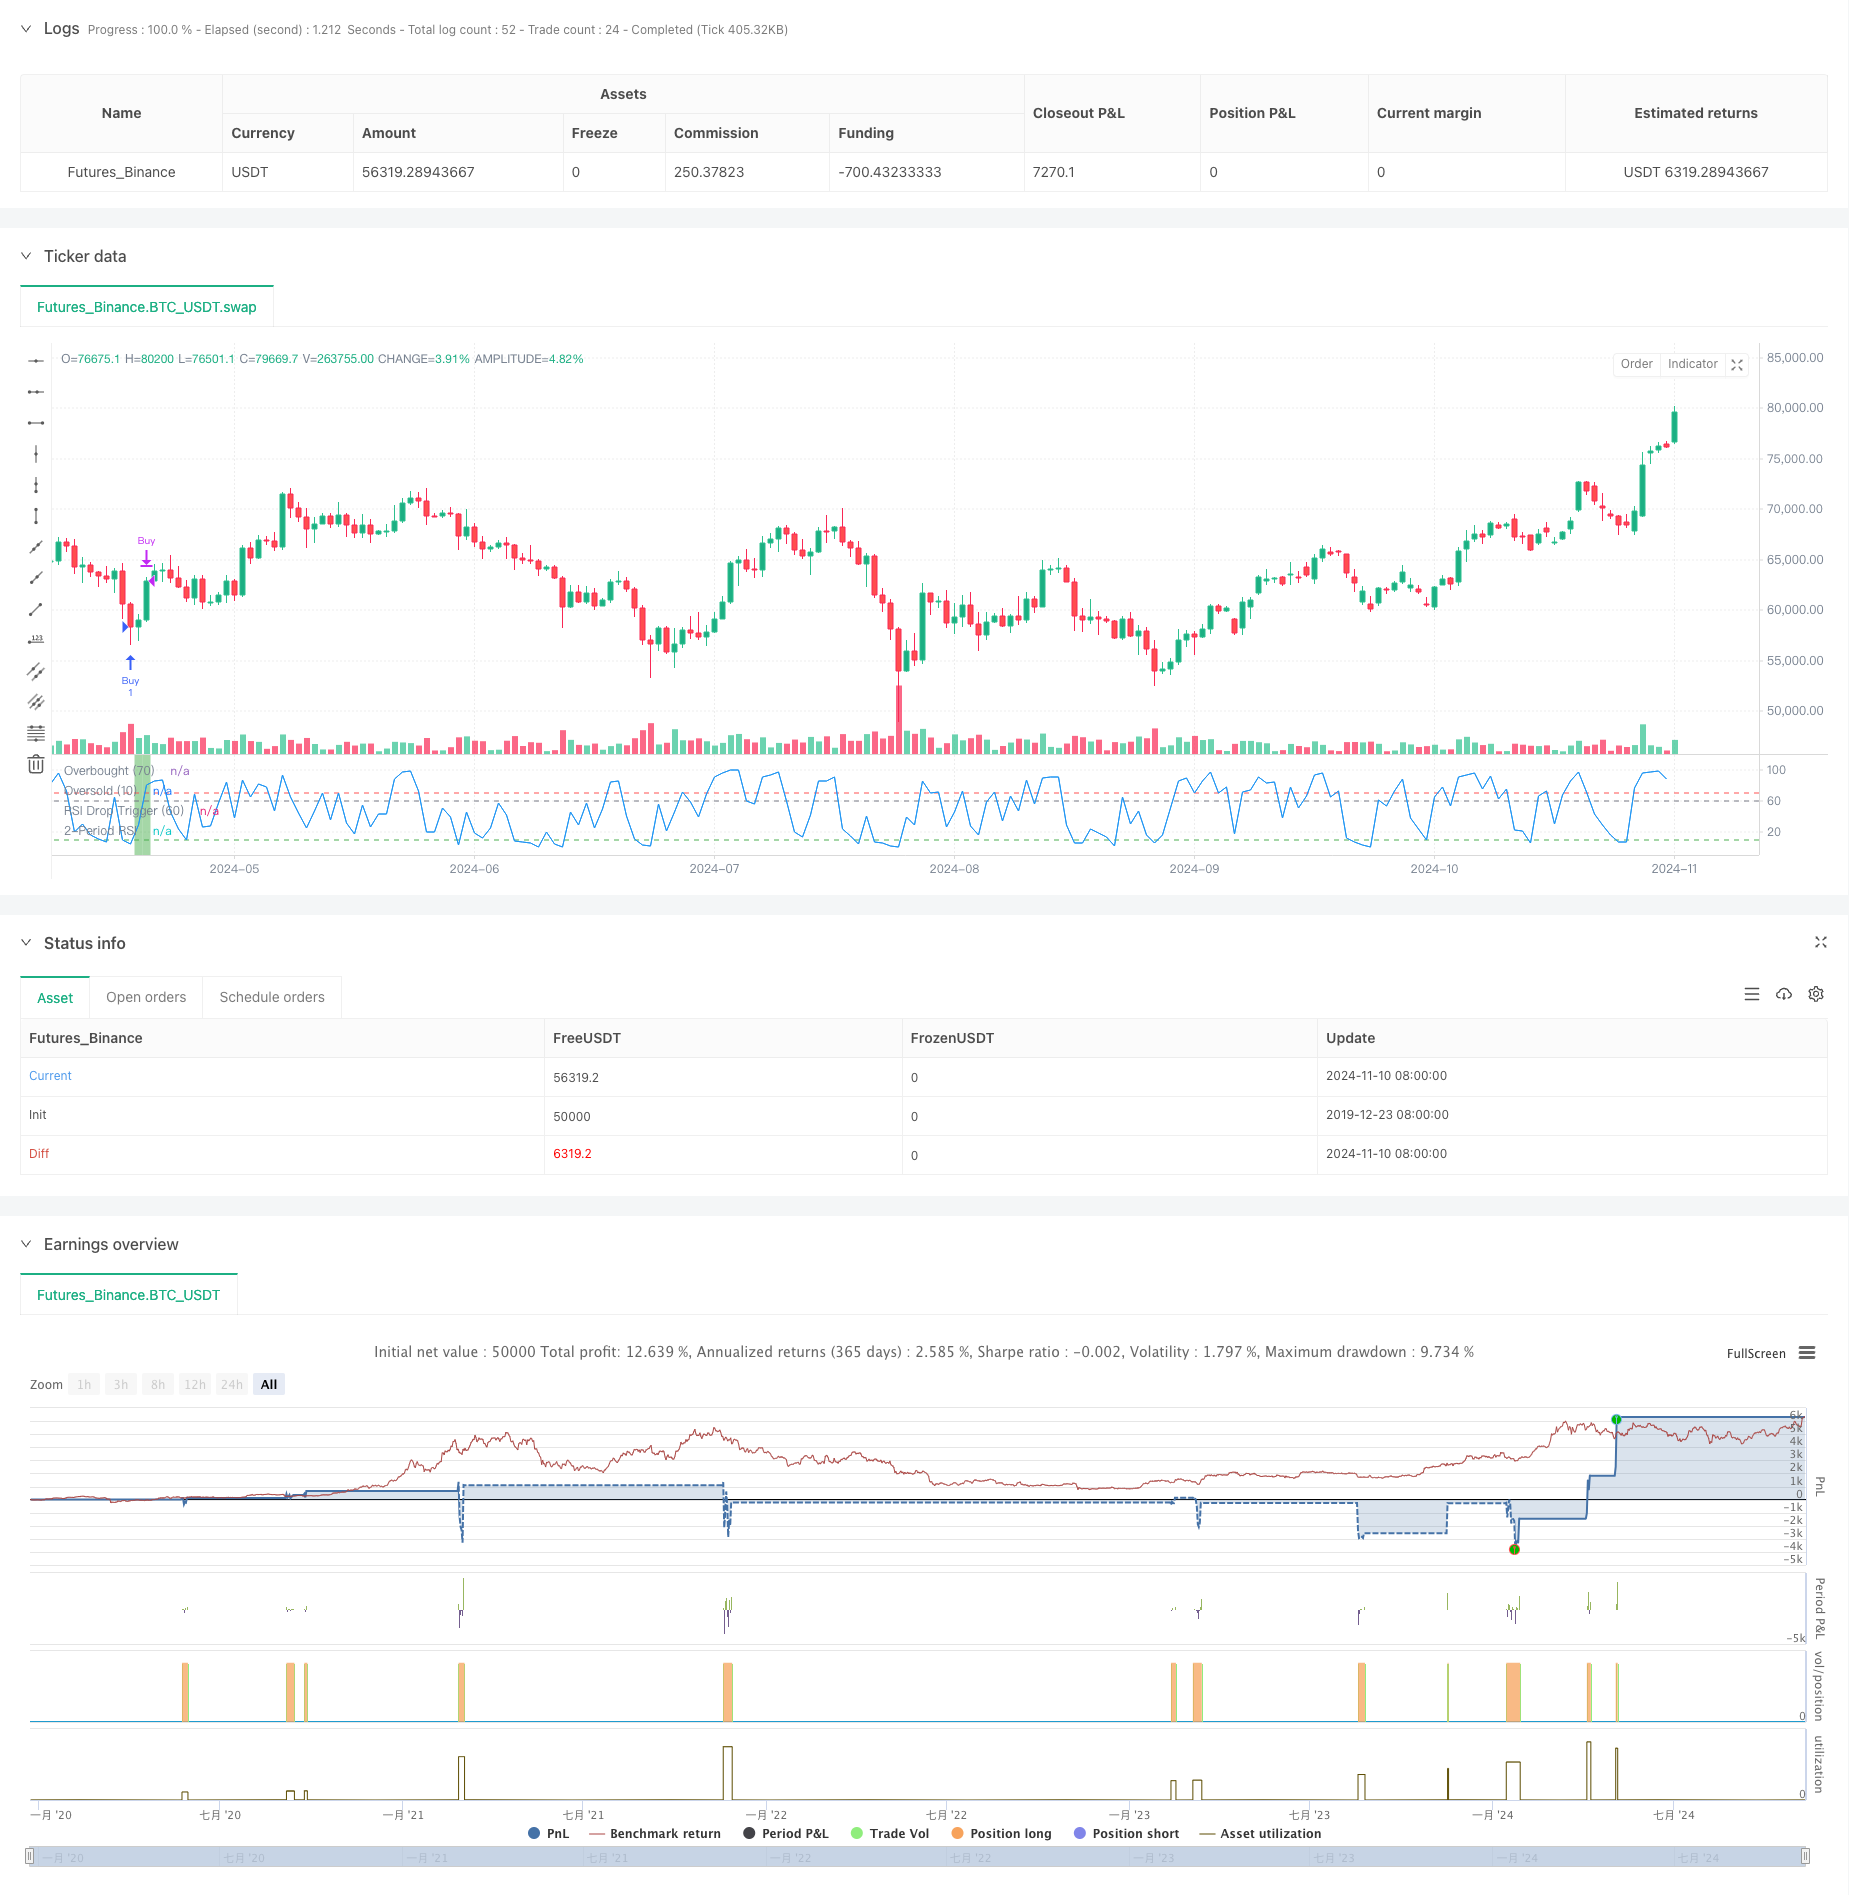
This strategy is a short-term mean reversion trading system that combines a 200-day moving average with a 2-period RSI indicator. The core concept is to identify oversold correction opportunities within long-term…
Overview
This strategy is a short-term mean reversion trading system that combines a 200-day moving average with a 2-period RSI indicator. The core concept is to identify oversold correction opportunities within long-term uptrends through a triple validation mechanism.
Strategy Principles
The strategy employs a triple validation mechanism: first, price must be above the 200-day moving average to confirm a long-term uptrend; second, RSI must decline for three consecutive days with the initial decline starting above 60; finally, RSI must fall below 10 indicating extreme oversold conditions. When all three conditions are met simultaneously, a long signal is generated. The position is closed when RSI rises above 70, indicating overbought conditions.
Strategy Advantages
- Triple validation mechanism significantly improves signal reliability
- Combination of long and short-term indicators avoids false signals
- Clear logic and simple parameters make it easy to understand and execute
- Moving average filter ensures trades align with the main trend
- Extreme oversold conditions trigger entries, increasing probability of success
Strategy Risks
- Frequent trading may result in high transaction costs
- May miss continuous upward movements in strong trend markets
- RSI indicator may lag in certain market conditions
- Excessive false signals possible during high volatility Risk management through stop-loss settings, position duration control, and trading frequency optimization is recommended.
Optimization Directions
- Consider adding volume indicators for confirmation
- Optimize RSI parameters and test different periods
- Introduce adaptive mechanisms to adjust parameters based on market volatility
- Add trend strength filters to improve trade quality
- Implement stop-loss mechanisms for better risk control
Summary
The strategy creates a robust trading system through clever combination of moving averages and RSI indicators. While the triple validation mechanism effectively improves trading reliability, attention to risk management and parameter optimization remains crucial. The overall design is rational with good practical value and optimization potential.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-11 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Larry Connors RSI 3 Strategy", overlay=false)

// Define the moving averages and the RSI
sma200 = ta.sma(close, 200)
rsi2 = ta.rsi(close, 2)

// Conditions for the strategy
condition1 = close > sma200  // Close above the 200-day moving average

// RSI drops three days in a row and the first day's drop is from above 60
rsi_drop_3_days = rsi2[2] > rsi2[1] and rsi2[1] > rsi2 and rsi2[2] > 60  // The 3-day RSI drop condition
condition2 = rsi_drop_3_days

// The 2-period RSI is below 10 today
condition3 = rsi2 < 10

// Combined buy condition
buyCondition = condition1 and condition2 and condition3

// Sell condition: The 2-period RSI is above 70
sellCondition = rsi2 > 70

// Execute the buy signal when all buy conditions are met
if buyCondition
    strategy.entry("Buy", strategy.long)

// Execute the sell signal when the sell condition is met
if sellCondition
    strategy.close("Buy")

// Plotting the RSI for visual confirmation
plot(rsi2, title="2-Period RSI", color=color.blue)
hline(70, "Overbought (70)", color=color.red)
hline(10, "Oversold (10)", color=color.green)
hline(60, "RSI Drop Trigger (60)", color=color.gray)

// Set background color when a position is open
bgcolor(strategy.opentrades > 0 ? color.new(color.green, 50) : na)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Triple-Validated-RSI-Mean-Reversion-with-Moving-Average-Filter-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Advanced Strategy with Volume and Price Pullback Multiple Take ProfitPine Script · Mean reversion · 1h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d