Strategy vault / Trend following
True Range Based Weighted Moving Average Cross Period Strategy
This strategy uses True Range and Weighted Moving Average (WMA) to build a cross period indicator for trend judgement. At the same time, it has a pyramid position accumulation mechanism with multiple stop loss…
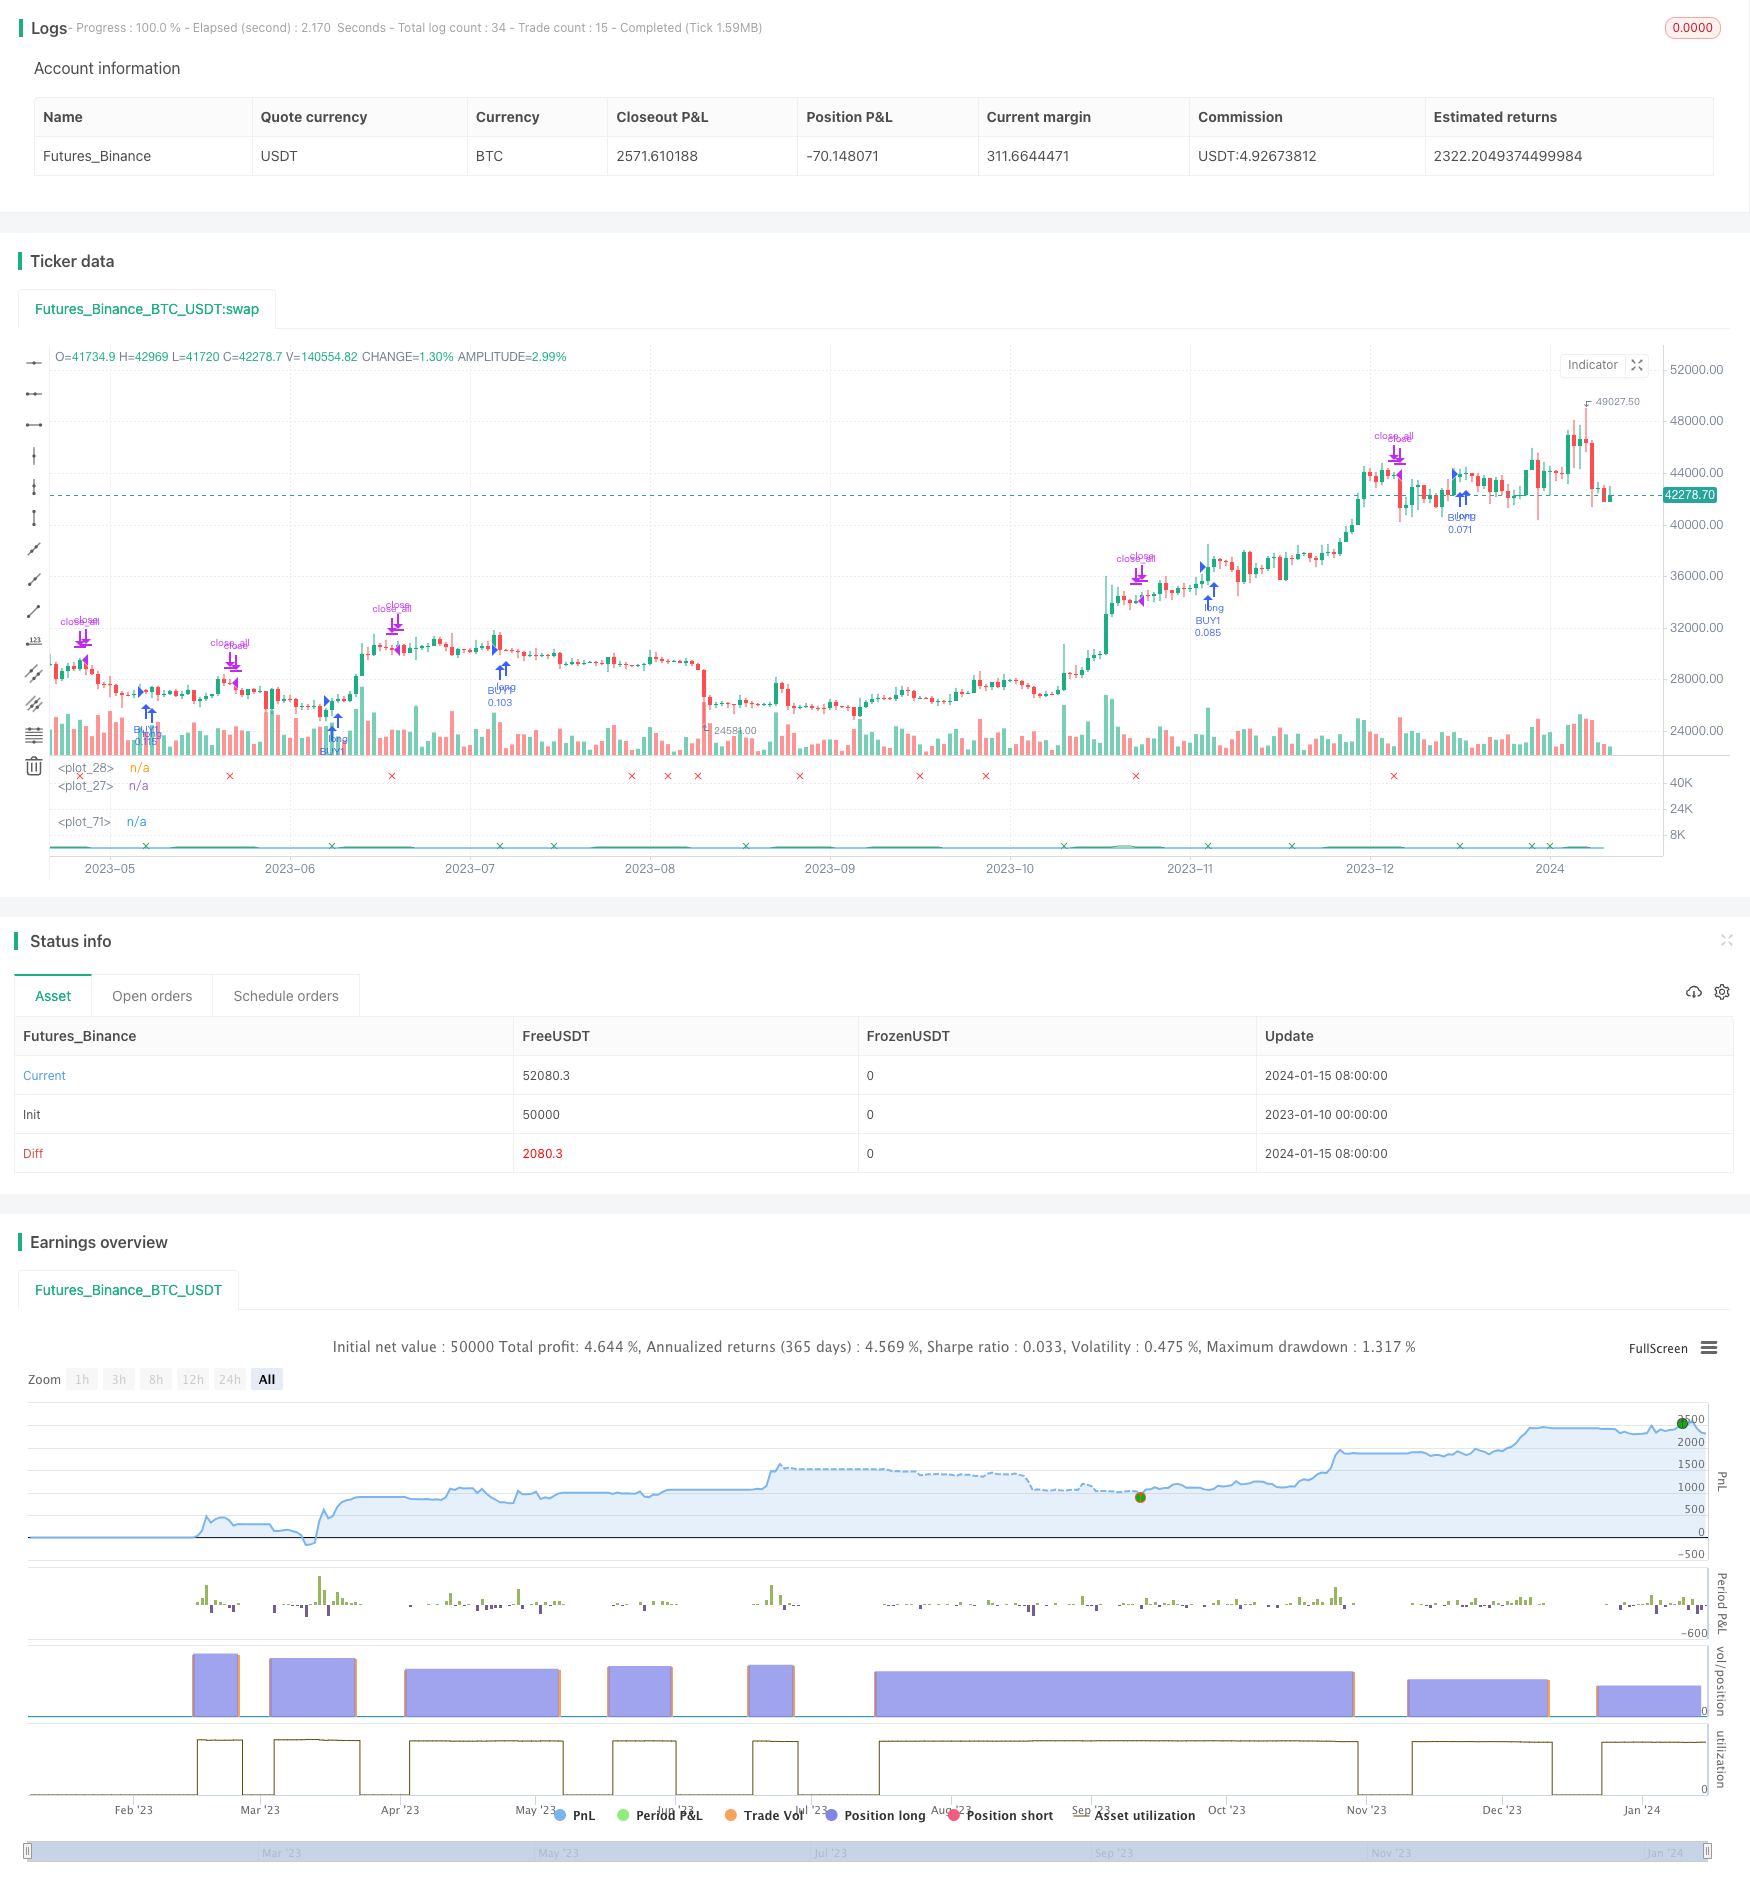
Overview
This strategy uses True Range and Weighted Moving Average (WMA) to build a cross period indicator for trend judgement. At the same time, it has a pyramid position accumulation mechanism with multiple stop loss mechanisms to pursue stable profits.
Strategy Principle
The strategy first calculates the up amplitude (sube) and down amplitude (baja), and then calculates the WMA of the fast line (corto) cycle and the slow line (largo) cycle respectively. The difference between the fast and slow lines is calculated again through WMA to get the indicator (ind). When the indicator crosses above 0, a buy signal is generated. When it crosses below 0, a sell signal is generated.
After entering the market, the strategy presets 5 positions, which are accumulated in a pyramid (doubled) manner. At the same time, a stop loss mechanism is set so that the subsequent positions opened will be judged whether the current floating profit is lower than the stop loss line, so as to control risks.
Advantage Analysis
The strategy integrates mechanisms such as cross-cycle judgment, pyramid position accumulation, and multiple stop losses, which can effectively control risks and pursue stable profits.
Cross-cycle judgments establish a trend judgment system through fast and slow lines combination, which can effectively filter market noise and identify trend turning points. Pyramid positions can profit more at the beginning of the trend, and multiple stop loss mechanisms can effectively control single loss.
Risk Analysis
The main risk of this strategy is the possibility of a sudden event causing a rapid market reversal that triggers a stop loss cutoff and causes losses. In addition, improper parameter settings will also affect the stability of the strategy.
The risk of market reversal can be dealt with by appropriately relaxing the stop loss line. Optimizing parameter settings and adjusting cycle parameters, number of positions, etc. can improve the stability of the strategy.
Optimization Direction
The strategy can be optimized in the following aspects:
Increase statistical indicators for judgement, use indicators like volatility and volume to correct parameters and make the strategy more adaptive.
Increase machine learning model for judgement, use LSTM and other deep learning models to assist judgement and improve strategy accuracy.
Optimize position management mechanisms, consider adjusting the amplitude of position increase according to floating profit percentage to make position growth more reasonable.
Incorporate futures hedging models to further control risks through spot and futures arbitrage.
Summary
In summary, this is a cross-cycle trend strategy based on True Range indicators with pyramid position accumulation and multiple stop loss mechanisms, which can effectively control risks and pursue stable profits. It is a very practical quantitative trading strategy. However, attention is still needed to reversal risks and parameter optimization problems. Further optimizations can be done in statistics, machine learning and other aspects.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_2 | timestamp(31 Dec 2025 00:00 -0700) | End Time |
| v_input_3 | 10 | corto |
| v_input_4 | 30 | largo |
| v_input_5 | 10 | suavizado |
| v_input_6 | 50000 | contrato1 |
| v_input_float_1 | 6.5 | porc_tp |
| v_input_7 | -6 | safe |
| v_input_1 | timestamp(01 Jan 2022 00:00 -0700) | (?Backtest Window)Start Time |
Source Pine Script
/*backtest
start: 2023-01-10 00:00:00
end: 2024-01-16 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © MaclenMtz

//@version=5
strategy("[MACLEN] Rangos", shorttitle="Rangos [https://t.me/Bitcoin_Maclen]", overlay=false )

//------WINDOW----------

i_startTime = input(defval = timestamp("01 Jan 2022 00:00 -0700"), title = "Start Time", group = "Backtest Window")
i_endTime = input(defval = timestamp("31 Dec 2025 00:00 -0700"), title = "End Time")
window = true

//-----------------------------

sube = close>close[1] ? ta.tr : 0
baja = close<close[1] ? ta.tr : 0

corto = input(10)
largo = input(30)
suavizado = input(10)

fastDiff = ta.wma(sube, corto) - ta.wma(baja,corto)
slowDiff = ta.wma(sube, largo) - ta.wma(baja, largo)
ind = ta.wma(fastDiff - slowDiff, suavizado)

iColor = ind>0 ? color.green : ind<0 ? color.red : color.black
plot(ind, color=iColor)
plot(0, color=color.white)

long = ind[1]<ind and ind[2]<ind[1] and ind<0
short = ind[1]>ind and ind[2]>ind[1] and ind>0

plotshape(long and not long[1], style = shape.xcross, color=color.green, location=location.bottom, size=size.tiny)
plotshape(short and not short[1], style = shape.xcross, color=color.red, location=location.top, size=size.tiny)

//Contratos
contrato1 = input(50000)/(16*close)
c1 = contrato1
c2 = contrato1
c3 = contrato1*2
c4 = contrato1*4
c5 = contrato1*8

//cap_enopentrade = strategy.opentrades == 1 ? c1: strategy.opentrades == 2 ? c1+c2: strategy.opentrades == 3 ? c1+c2+c3: strategy.opentrades == 4 ? c1+c2+c3+c4: strategy.opentrades == 5 ? c1+c2+c3+c4+c5 : 0
openprofit_porc = math.round((close-strategy.position_avg_price)/strategy.position_avg_price * 100,2)

porc_tp = input.float(6.5)
safe = input(-6)

//----------------Strategy---------------------------

if strategy.opentrades == 0
    strategy.entry('BUY1', strategy.long, qty=c1, when = long and not long[1] and window)

if strategy.opentrades == 1
    strategy.entry('BUY2', strategy.long, qty=c2, when = long and not long[1] and window and openprofit_porc<safe)

if strategy.opentrades == 2
    strategy.entry('BUY3', strategy.long, qty=c3, when = long and not long[1] and window and openprofit_porc<safe)

if strategy.opentrades == 3
    strategy.entry('BUY4', strategy.long, qty=c4, when = long and not long[1] and window and openprofit_porc<safe)

if strategy.opentrades == 4
    strategy.entry('BUY5', strategy.long, qty=c5, when = long and not long[1] and window and openprofit_porc<safe)

min_prof = strategy.openprofit>0

strategy.close_all(when=short and min_prof)

plot(openprofit_porc)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/True-Range-Based-Weighted-Moving-Average-Cross-Period-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h