Two Way Contract Grid Trading V102
Function Futures grid trading At the same time, arbitrage is done by shorting and going long Because the probability of liquidation in a bidirectional strategy is very low Buy order timeout judgment Multiple Betting…
Two-way contract grid tradingv1.0.2
Function
Futures grid trading At the same time, arbitrage is done by shorting and going long Because the probability of liquidation in a bidirectional strategy is very low
- Buy order timeout judgment
- Multiple Betting
- Auto Copy Trading
- Trend orders (to be developed, paid version))
- Dynamically modify the order quantity based on price change speed (under development, paid version))
- Golden cross and death cross trend added (to be developed, paid version))
Backtest Data
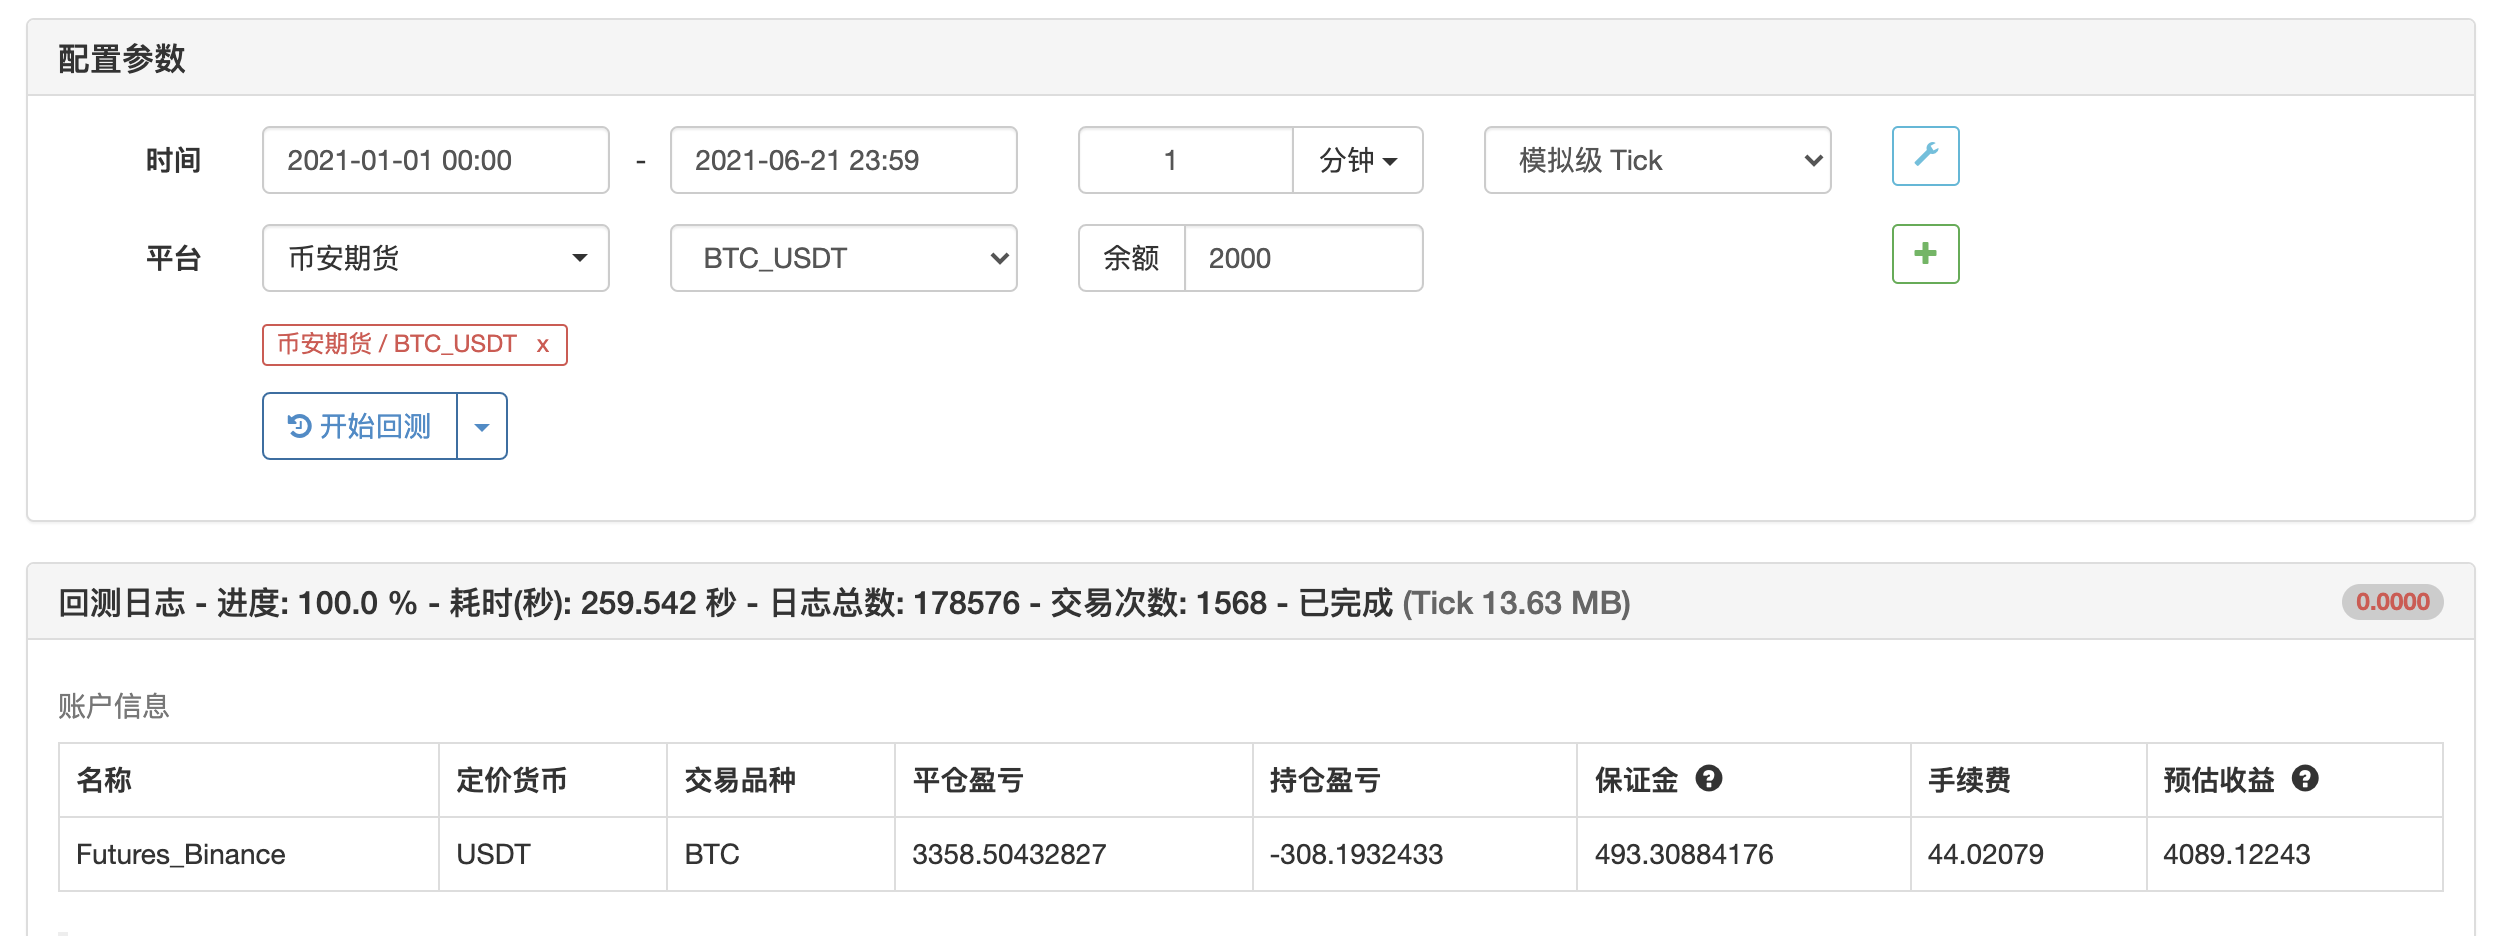
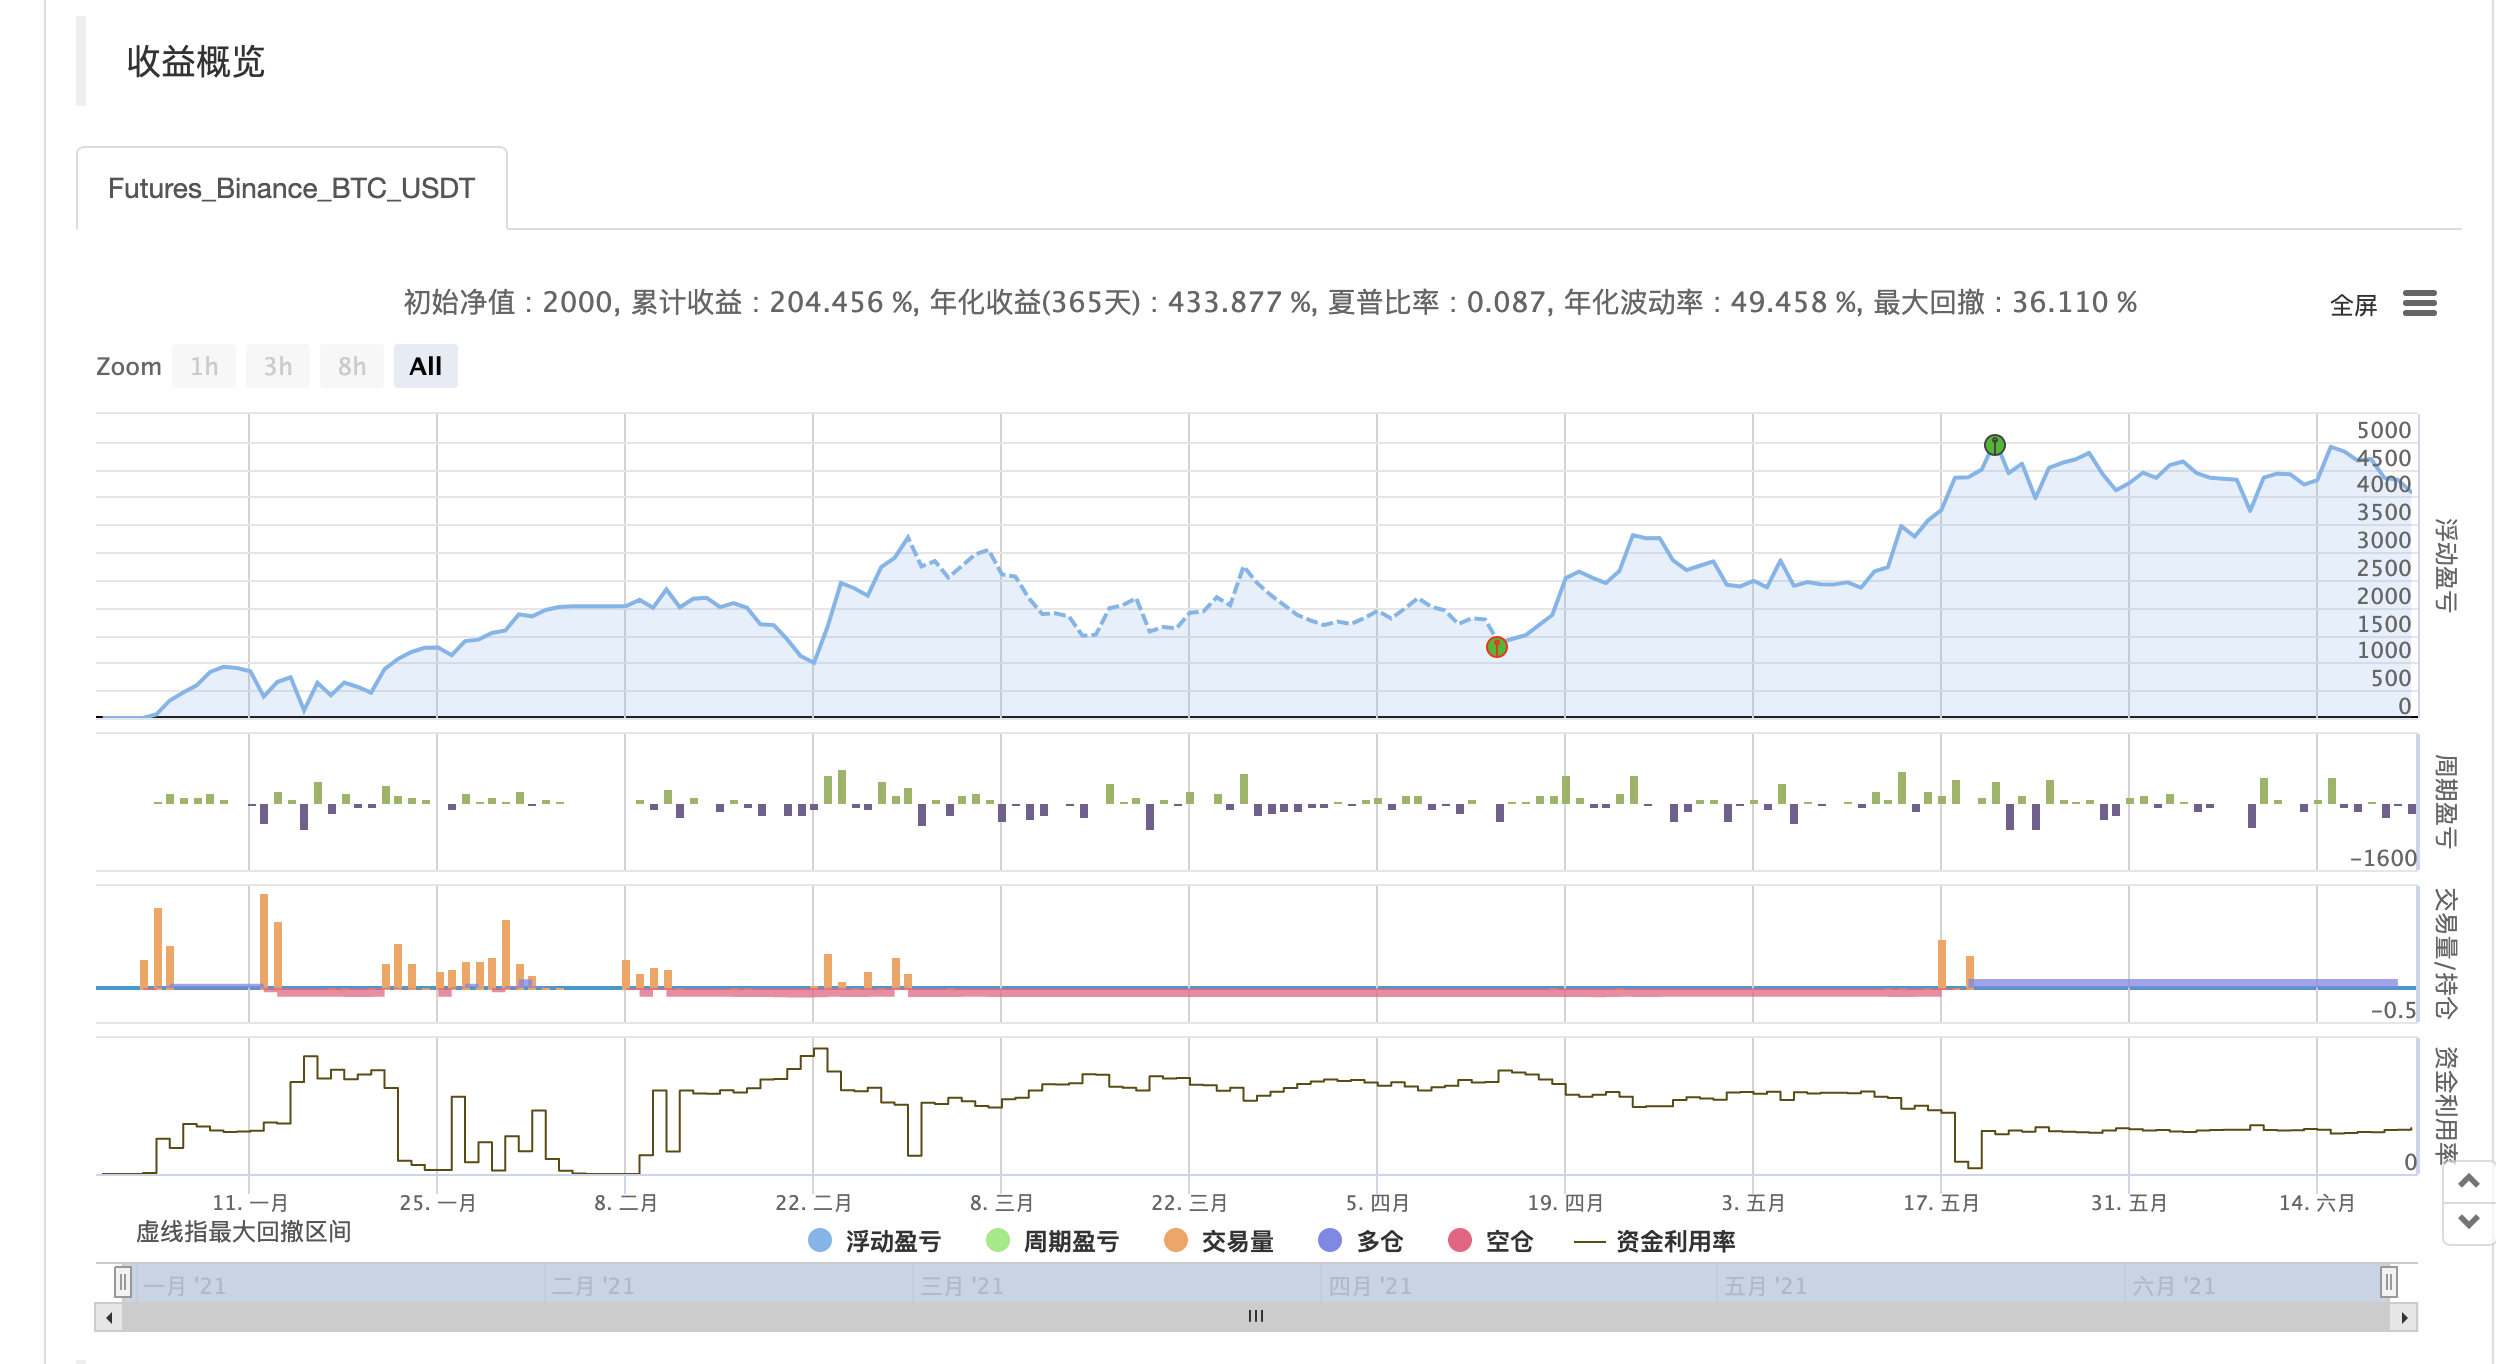
2000uDouble in Half a Year Profits are very obvious, can withstand both large rises and falls
Maintenance
Continuous Optimization
Source JavaScript
/*backtest
start: 2021-01-01 00:00:00
end: 2021-06-21 23:59:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":2000}]
*/

// First Purchase
let FIRST_BUY = true;
// There is already a buy order
let MANY_BUYING = false;
// A short order already exists
let SHORT_BUYING = false;
// Long order creation time
let MANY_BUY_TIME = null;
// Short order creation time
let SHORT_BUY_TIME = null;
// Buy long short positions
let MANY_EMPTY_STEP_TIME = null;
// Short Short Position
let SHORT_EMPTY_STEP_TIME = null;
// Check the empty position time
let CHECK_TIME = null;

let QUANTITY = [0.001, 0.002, 0.004, 0.008, 0.016, 0.032, 0.064];
// Next purchase price(Long position)
let MANY_NEXT_BUY_PRICE = 0;
// Next purchase price(Short position)
let SHORT_NEXT_BUY_PRICE = 0;
// Current Position(Long position)
let MANY_STEP = 0;
// Current Position(Short position)
let SHORT_STEP = 0;
// Take Profit Ratio
let PROFIT_RATIO = 1;
// Add Position Ratio
let DOUBLE_THROW_RATIO = 1.5;
// The downward percentage of the amount spent after selling
let BUY_PRICE_RATIO = 1;
// Trade order list(Long position)
let MANY_ORDER_LIST = [];
// Trade order list(Short position)
let SHORT_ORDER_LIST = [];

function getManyQuantity() {
    if (MANY_STEP < QUANTITY.length) {
        return QUANTITY[MANY_STEP]
    }
    return QUANTITY[0]
}

function getShortQuantity() {
    if (SHORT_STEP < QUANTITY.length) {
        return QUANTITY[SHORT_STEP]
    }
    return QUANTITY[0]
}

function firstManyBuy(ticker) {
    if (MANY_BUYING) {
        return
    }
    exchange.SetDirection("buy")
    let orderId = exchange.Buy(ticker.Last, getManyQuantity())
    if (!orderId) {
        return
    }
    MANY_BUYING = true
    while (true) {
        exchange.SetDirection("buy")
        let order = exchange.GetOrder(orderId)
        if (null === order) {
            continue
        }
        if (1 === order.Status || 2 === order.Status) {
            MANY_NEXT_BUY_PRICE = order.Price * ((100 - DOUBLE_THROW_RATIO) / 100)
            MANY_STEP = MANY_STEP + 1
            MANY_BUYING = false
            MANY_EMPTY_STEP_TIME = null
            let sellPrice = order.Price * ((100 + PROFIT_RATIO) / 100)
            MANY_ORDER_LIST.push({
                buyPrice: order.Price,
                sellPrice: sellPrice,
                quantity: order.Amount,
                isSell: false,
            })
            break
        }
    }
}

function firstShortBuy(ticker) {
    if (SHORT_BUYING) {
        return
    }
    exchange.SetDirection("sell")
    let orderId = exchange.Sell(ticker.Last, getShortQuantity())
    if (!orderId) {
        return
    }
    SHORT_BUYING = true
    while (true) {
        let order = exchange.GetOrder(orderId)
        if (null === order) {
            continue
        }
        if (1 === order.Status || 2 === order.Status) {
            SHORT_NEXT_BUY_PRICE = order.Price * ((100 + DOUBLE_THROW_RATIO) / 100)
            SHORT_STEP = SHORT_STEP + 1
            SHORT_BUYING = false
            SHORT_EMPTY_STEP_TIME = null
            let sellPrice = order.Price * ((100 - PROFIT_RATIO) / 100)
            SHORT_ORDER_LIST.push({
                buyPrice: order.Price,
                sellPrice: sellPrice,
                quantity: order.Amount,
                isSell: false,
            })
            break
        }
    }
}

function manyBuy(ticker) {
    if (MANY_BUYING) {
        return
    }
    Log('ticker: ' + ticker.Last + ' MANY_NEXT_BUY_PRICE: ' + MANY_NEXT_BUY_PRICE)
    if (ticker.Last > MANY_NEXT_BUY_PRICE) {
        return
    }
    exchange.SetDirection("buy")
    let orderId = exchange.Buy(ticker.Last, getManyQuantity())
    if (!orderId) {
        return
    }
    MANY_BUYING = true
    MANY_BUY_TIME = Unix()
    while (true) {
        let now = Unix()
        let order = exchange.GetOrder(orderId)
        let expire = MANY_BUY_TIME + (60 * 30)
        if (null === order) {
            continue
        }
        // Purchase successfully processed
        if (1 === order.Status || 2 === order.Status) {
            MANY_NEXT_BUY_PRICE = order.Price * ((100 - DOUBLE_THROW_RATIO) / 100)
            MANY_STEP = MANY_STEP + 1
            MANY_BUYING = false
            MANY_EMPTY_STEP_TIME = null
            let sellPrice = order.Price * ((100 + PROFIT_RATIO) / 100)
            MANY_ORDER_LIST.push({
                buyPrice: order.Price,
                sellPrice: sellPrice,
                quantity: order.Amount,
                isSell: false,
            })
            break
        }
        // Buy timeout processing
        if (now >= expire) {
            exchange.CancelOrder(orderId)
            MANY_BUYING = false
            MANY_BUY_TIME = null
            MANY_NEXT_BUY_PRICE = ticker.Last * ((100 - DOUBLE_THROW_RATIO) / 100)
            return
        }
    }
}

function shortBuy(ticker) {
    if (SHORT_BUYING) {
        return
    }
    Log('ticker: ' + ticker.Last + ' SHORT_NEXT_BUY_PRICE: ' + SHORT_NEXT_BUY_PRICE)
    if (ticker.Last < SHORT_NEXT_BUY_PRICE) {
        return
    }
    exchange.SetDirection("sell")
    let orderId = exchange.Sell(ticker.Last, getShortQuantity())
    if (!orderId) {
        return
    }
    SHORT_BUYING = true
    SHORT_BUY_TIME = Unix()
    while (true) {
        let now = Unix()
        let expire = SHORT_BUY_TIME + (60 * 30)
        let order = exchange.GetOrder(orderId)
        if (null === order) {
            continue
        }
        // Purchase successfully processed
        if (1 === order.Status || 2 === order.Status) {
            SHORT_NEXT_BUY_PRICE = order.Price * ((100 + DOUBLE_THROW_RATIO) / 100)
            SHORT_STEP = SHORT_STEP + 1
            SHORT_BUYING = false
            SHORT_EMPTY_STEP_TIME = null
            let sellPrice = order.Price * ((100 - PROFIT_RATIO) / 100)
            SHORT_ORDER_LIST.push({
                buyPrice: order.Price,
                sellPrice: sellPrice,
                quantity: order.Amount,
                isSell: false,
            })
            break
        }
        // Buy timeout processing
        if (now >= expire) {
            exchange.CancelOrder(orderId)
            SHORT_BUYING = false
            SHORT_BUY_TIME = null
            SHORT_NEXT_BUY_PRICE = ticker.Last * ((100 + DOUBLE_THROW_RATIO) / 100)
            return
        }
    }
}


function manySell(ticker) {
    // Traverse sell orders
    for (let item of MANY_ORDER_LIST) {
        if (item.isSell) {
            continue
        }
        if (ticker.Last >= item.sellPrice) {
            item.isSell = true;
            exchange.SetDirection("closebuy")
            let orderId = exchange.Sell(ticker.Last, item.quantity)
            if (!orderId) {
                return
            }
            while (true) {
                let order = exchange.GetOrder(orderId)
                if (null === order) {
                    continue
                }
                if (1 === order.Status || 2 === order.Status) {
                    MANY_NEXT_BUY_PRICE = ticker.Last * ((100 - BUY_PRICE_RATIO) / 100)
                    MANY_STEP = MANY_STEP - 1
                    if (0 === MANY_STEP) {
                        MANY_EMPTY_STEP_TIME = Unix()
                    }
                    break
                }
            }
        }
    }
}

function shortSell(ticker) {
    // Traverse sell orders
    for (let item of SHORT_ORDER_LIST) {
        if (item.isSell) {
            continue
        }
        if (ticker.Last <= item.sellPrice) {
            item.isSell = true;
            exchange.SetDirection("closesell")
            let orderId = exchange.Buy(ticker.Last, item.quantity)
            if (!orderId) {
                return
            }
            while (true) {
                let order = exchange.GetOrder(orderId)
                if (null === order) {
                    continue
                }
                if (1 === order.Status || 2 === order.Status) {
                    SHORT_NEXT_BUY_PRICE = ticker.Last * ((100 + BUY_PRICE_RATIO) / 100)
                    SHORT_STEP = SHORT_STEP - 1
                    if (0 === SHORT_STEP) {
                        SHORT_EMPTY_STEP_TIME = Unix()
                    }
                    break
                }
            }
        }
    }
}

function check(ticker) {
    let now = Unix()
    if (null !== CHECK_TIME) {
        let expire = CHECK_TIME + (60 * 10)
        if (now < expire) {
            return
        }
    }
    CHECK_TIME = now

    if (null !== MANY_EMPTY_STEP_TIME) {
        let expire = MANY_EMPTY_STEP_TIME + (60 * 30)
        if (now >= expire) {
            MANY_NEXT_BUY_PRICE = ticker.Last * ((100 - DOUBLE_THROW_RATIO) / 100)
            Log('No long positions, Adjust Buying Price: ' + MANY_NEXT_BUY_PRICE)
        }
    }

    if (null !== SHORT_EMPTY_STEP_TIME) {
        let expire = SHORT_EMPTY_STEP_TIME + (60 * 30)
        if (now >= expire) {
            SHORT_NEXT_BUY_PRICE = ticker.Last * ((100 + DOUBLE_THROW_RATIO) / 100)
            Log('No short positions, Adjust Buying Price: ' + SHORT_NEXT_BUY_PRICE)
        }
    }
}

function onTick() {
    // Write strategy logic here, will be called repeatedly, e.g., to print market information
    let ticker = exchange.GetTicker()
    if (!ticker) {
        return
    }
    if (FIRST_BUY) {
        // First long buy
        firstManyBuy(ticker)
        // First short buy
        firstShortBuy(ticker)
        FIRST_BUY = false
        return
    }

    // Long Buy
    manyBuy(ticker)
    // Short Buy
    shortBuy(ticker)
    // Long Sell
    manySell(ticker)
    // Short Sell
    shortSell(ticker)
    // Empty Position Detection
    check(ticker)
}

function main() {
    // Open contract
    exchange.SetContractType("swap")

    while(true){
        onTick()
        // Sleepfunctions are mainly used to control the polling frequency of digital currency strategies and prevent access to exchangesAPIinterfaces are too frequent
        Sleep(60000)
    }
}
Published by wind on the FMZ strategy square · last modified 2021-06-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a grid bot with inventory caps and order deduplication from strategies/Two-Way-Contract-Grid-Trading-V102.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bybit Inverse Contract Dynamic Grid Special GridJavaScript · Grid
- Grid Pending Order Plus Martin Multiple IncreaseJavaScript · Grid · 1d
- Single Commodity Small Shop Strategy V20 Annualized 130JavaScript · Grid · 1d
- Mesh Deformation Strategy for Single Sided MeshJavaScript · Grid
- Mesh Deformation Strategy for Single Sided Mesh NotesJavaScript · Grid · 1d
- U Based Grid Amplitude FilteringJavaScript · Grid