Up Down K Line Pattern High Frequency Arbitrage Strategy
This strategy utilizes a K-line pattern based judgment method to implement high frequency market making arbitrage. Its main idea is to open and close trades for high frequency market making by judging bullish/bearish…
Overview
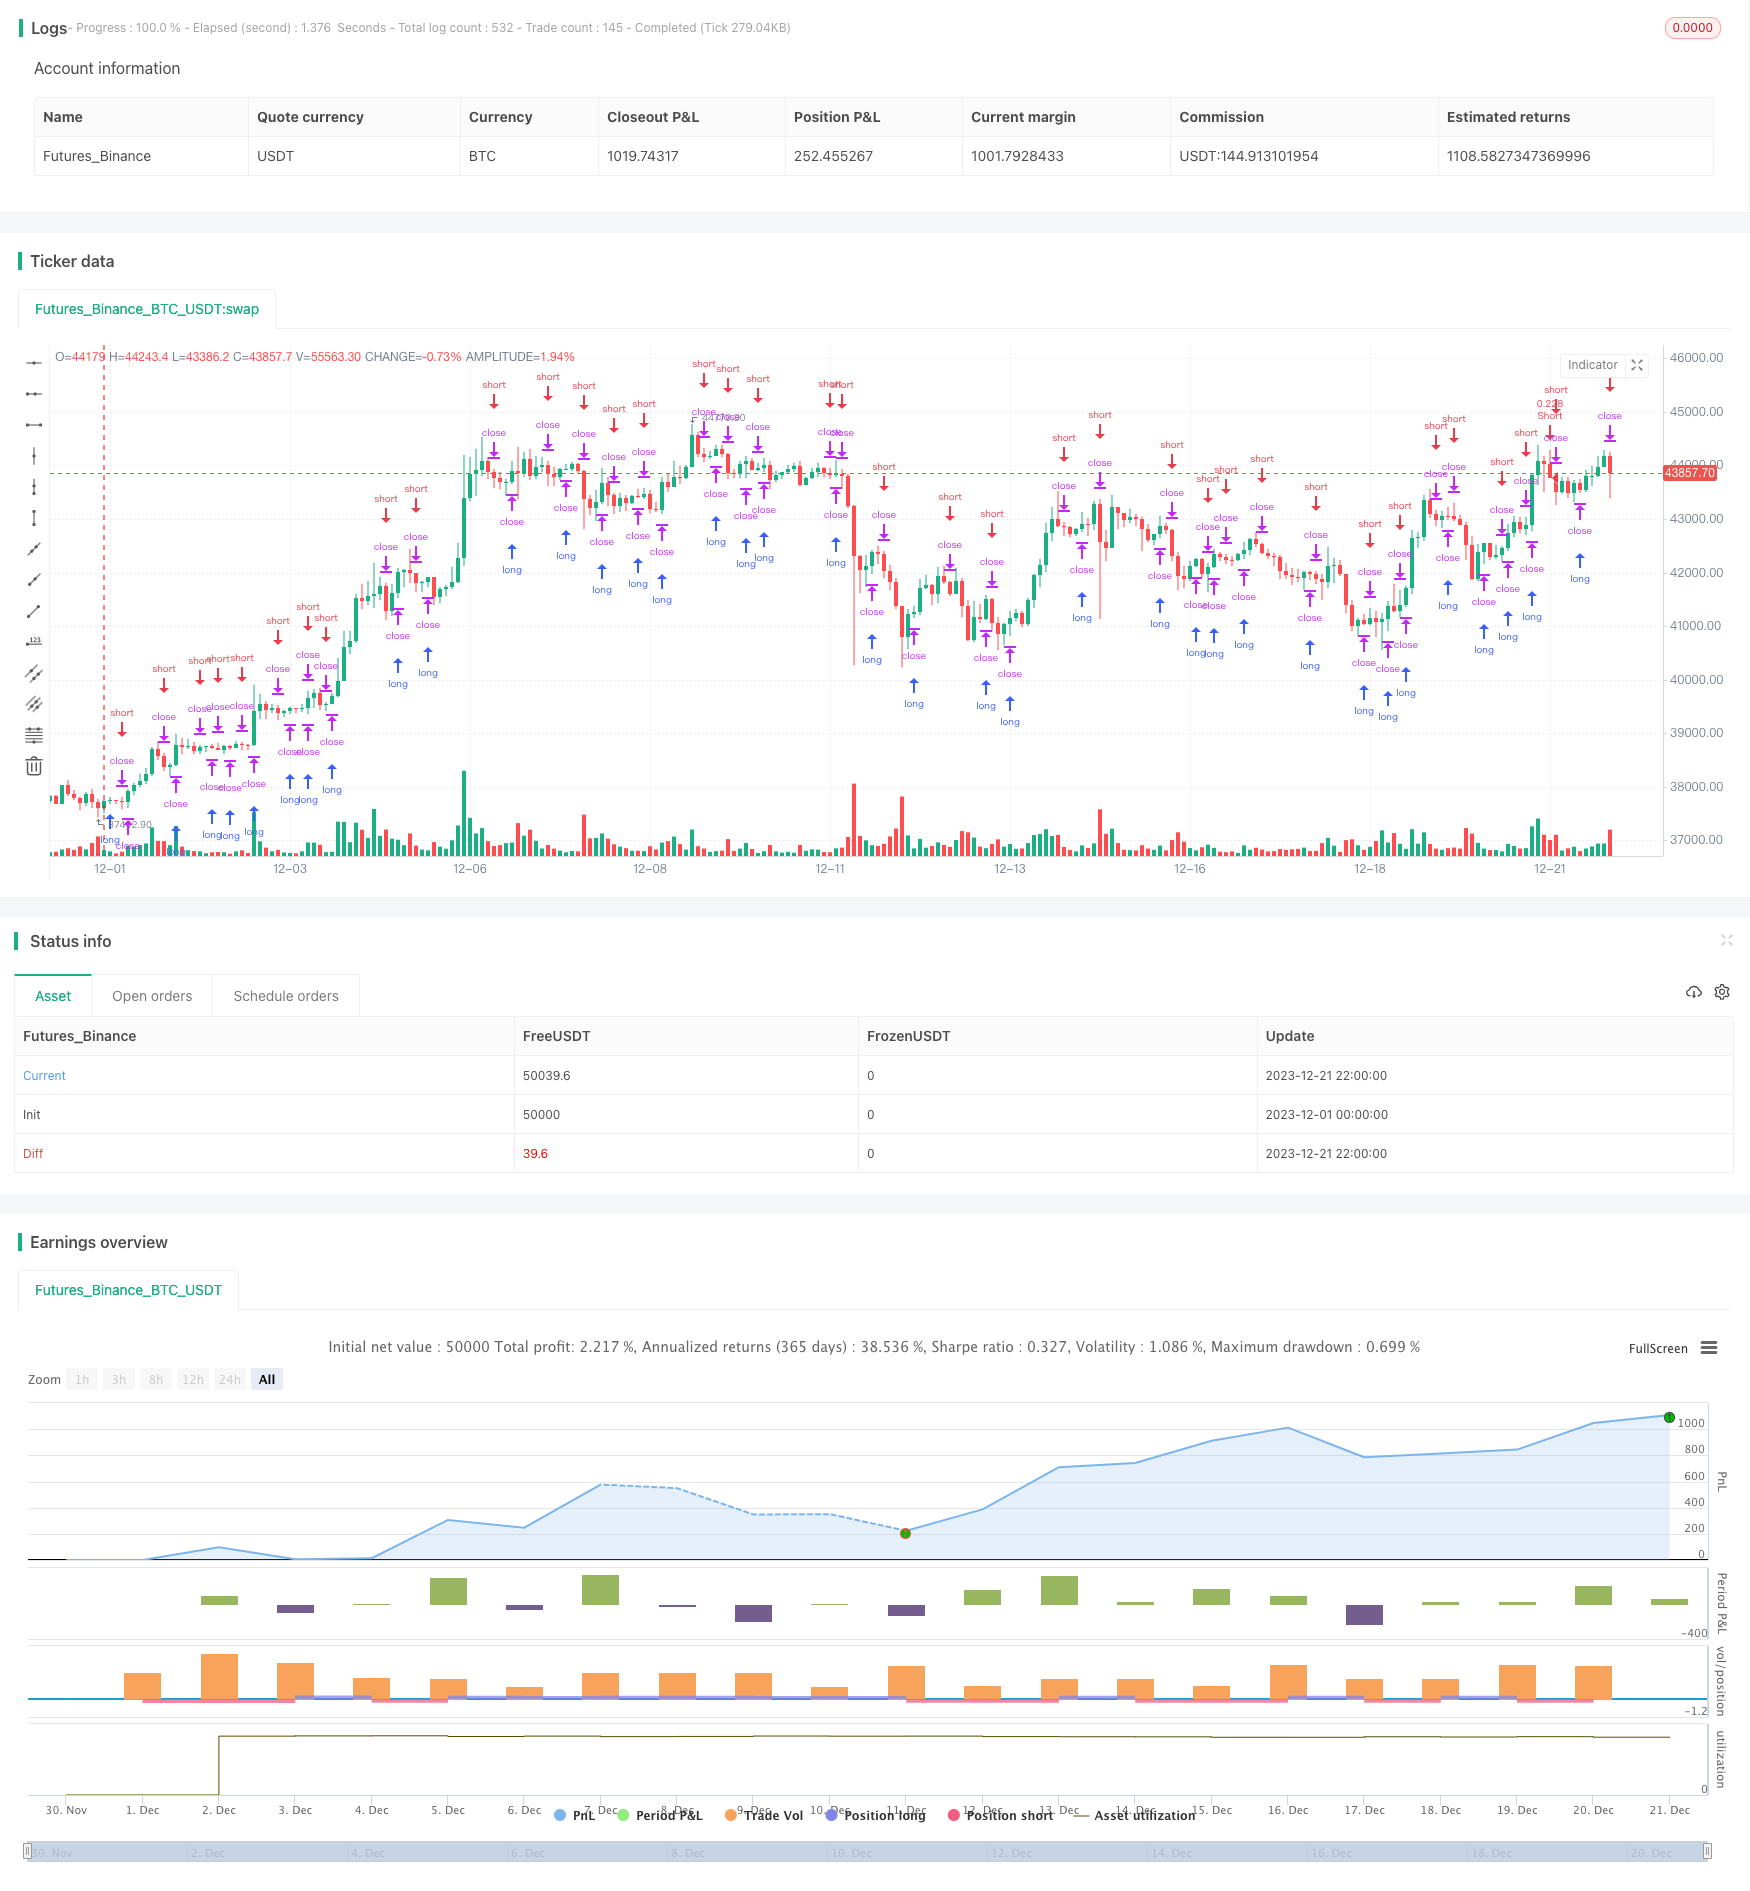
This strategy utilizes a K-line pattern based judgment method to implement high frequency market making arbitrage. Its main idea is to open and close trades for high frequency market making by judging bullish/bearish patterns across different K-line timeframes. Specifically, the strategy concurrently monitors multiple K-line timeframes and takes corresponding long or short positions when it observes consecutive rising or falling K-lines.
Strategy Logic
The core logic of this strategy lies in judging bullish/bearish patterns across different K-line timeframes. Specifically, it concurrently tracks 1-min, 5-min and 15-min K-lines. The strategy determines current sentiment by checking if prices have risen or fallen compared to N previous K-lines. If prices consecutively rise, it indicates a bullish sentiment; if prices consecutively fall, it signals a bearish view. Upon bullish signals, the strategy goes long; upon bearish signals, the strategy goes short. In this way, the strategy could capture trend and mean-reversion opportunities across different timeframes for high frequency arbitrage.
The core logic is implemented by tracking two indicators ups and dns, which record the number of consecutive rising and falling K-lines. Parameters consecutiveBarsUp and consecutiveBarsDown allow customization of the threshold for determining a trend. When ups is greater than or equal to consecutiveBarsUp, it signals a bullish pattern; when dns exceeds consecutiveBarsDown, it indicates a bearish pattern. In addition, the strategy specifies back-testing time range and order execution messages etc.
Advantages
The advantages of this strategy include:
- Capture high frequency arbitrage opportunities for market making
- Simple and effective logic based on K-line patterns
- Concurrent monitoring of multiple timeframes improves capture rate
- Intuitive parameter tuning
- Configurable back-testing time range for optimization
Risks
There are also several risks to be aware of:
- General risks of high frequency trading like data issues, order failures etc.
- Improper parameter tuning might lead to over-trading or missing good chances
- Cannot handle more complex market conditions like whipsaws
Possible ways to mitigate the risks include:
- Incorporate more logic to determine prudent entry/exit
- Optimize parameter to balance trade frequency and profitability
- Consider more factors like volume, volatility to judge trends
- Test different stop loss mechanism to limit per trade loss
Enhancement Opportunities
This strategy can be enhanced from the following dimensions:
- Add more factors to judge patterns beyond simple rise/fall counts, like amplitude, energy etc.
- Evaluate other entry/exit indicators like MACD, KD etc.
- Incorporate technical factors like MA, channels to filter signals
- Optimize parameters across timeframes to find best combinations
- Develop stop loss and take profit mechanisms to improve stability
- Introduce quant risk controls like maximum positions, trade frequency etc.
- Test across different products to find best fitting
Conclusion
This strategy realizes a simple yet effective high frequency arbitrage strategy based on K-line pattern judgment. Its core lies in capturing intraday bullish/bearish trends across timeframes for arbitrage. Despite some inherent risks, this easy to understand strategy serves a good starting point for algorithmic trading. Further enhancements around optimization and risk management will likely generate more stable and profitable results.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | consecutiveBarsUp |
| v_input_2 | true | consecutiveBarsDown |
| v_input_3 | timestamp(2021-01-01T00:00:00) | startDate |
| v_input_4 | timestamp(2021-12-31T00:00:00) | finishDate |
| v_input_5 | {{strategy.order.alert_message}} | Buy message |
| v_input_6 | {{strategy.order.alert_message}} | Sell message |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-21 23:59:59
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4

// Strategy
strategy("Up/Down Strategy", initial_capital = 10000, default_qty_value = 10000, default_qty_type = strategy.cash)

consecutiveBarsUp = input(1)
consecutiveBarsDown = input(1)

price = close

ups = 0.0
ups := price > price[1] ? nz(ups[1]) + 1 : 0

dns = 0.0
dns := price < price[1] ? nz(dns[1]) + 1 : 0

// Strategy Backesting
startDate  = input(timestamp("2021-01-01T00:00:00"), type = input.time)
finishDate = input(timestamp("2021-12-31T00:00:00"), type = input.time)

time_cond  = true

// Messages for buy and sell
message_buy  = input("{{strategy.order.alert_message}}", title="Buy message")
message_sell = input("{{strategy.order.alert_message}}", title="Sell message")

// Strategy Execution

if (ups >= consecutiveBarsUp) and time_cond
    strategy.entry("Long", strategy.long, stop = high + syminfo.mintick, alert_message = message_buy)

if (dns >= consecutiveBarsDown) and time_cond
    strategy.entry("Short", strategy.short, stop = low + syminfo.mintick, alert_message = message_sell)

//plot(strategy.equity, title="equity", color=color.red, linewidth=2, style=plot.style_areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a spread arbitrage engine with WebSocket order routing and leg-risk controls from strategies/Up-Down-K-Line-Pattern-High-Frequency-Arbitrage-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bitcoin Trading Strategy Based on Ichimoku CloudPine Script · Arbitrage · 1h
- multiple auxiliary RSI indicator strategyPine Script · Arbitrage · 1d
- Time based Strategy with ATR Take ProfitPine Script · Arbitrage · 1h
- Adaptive Regularized Moving Average Cross Market Arbitrage StrategyPine Script · Arbitrage · 1h
- Dual Reversal Arbitrage StrategyPine Script · Arbitrage · 1h
- High Performance Algorithmic Trading Strategy Based on Quantitative ModelsPine Script · Arbitrage · 1d