Visual Comparison between Strategy and Buy Hold Returns
This strategy makes a detailed and visual comparison between a given strategy and the buy & hold returns of the traded security.
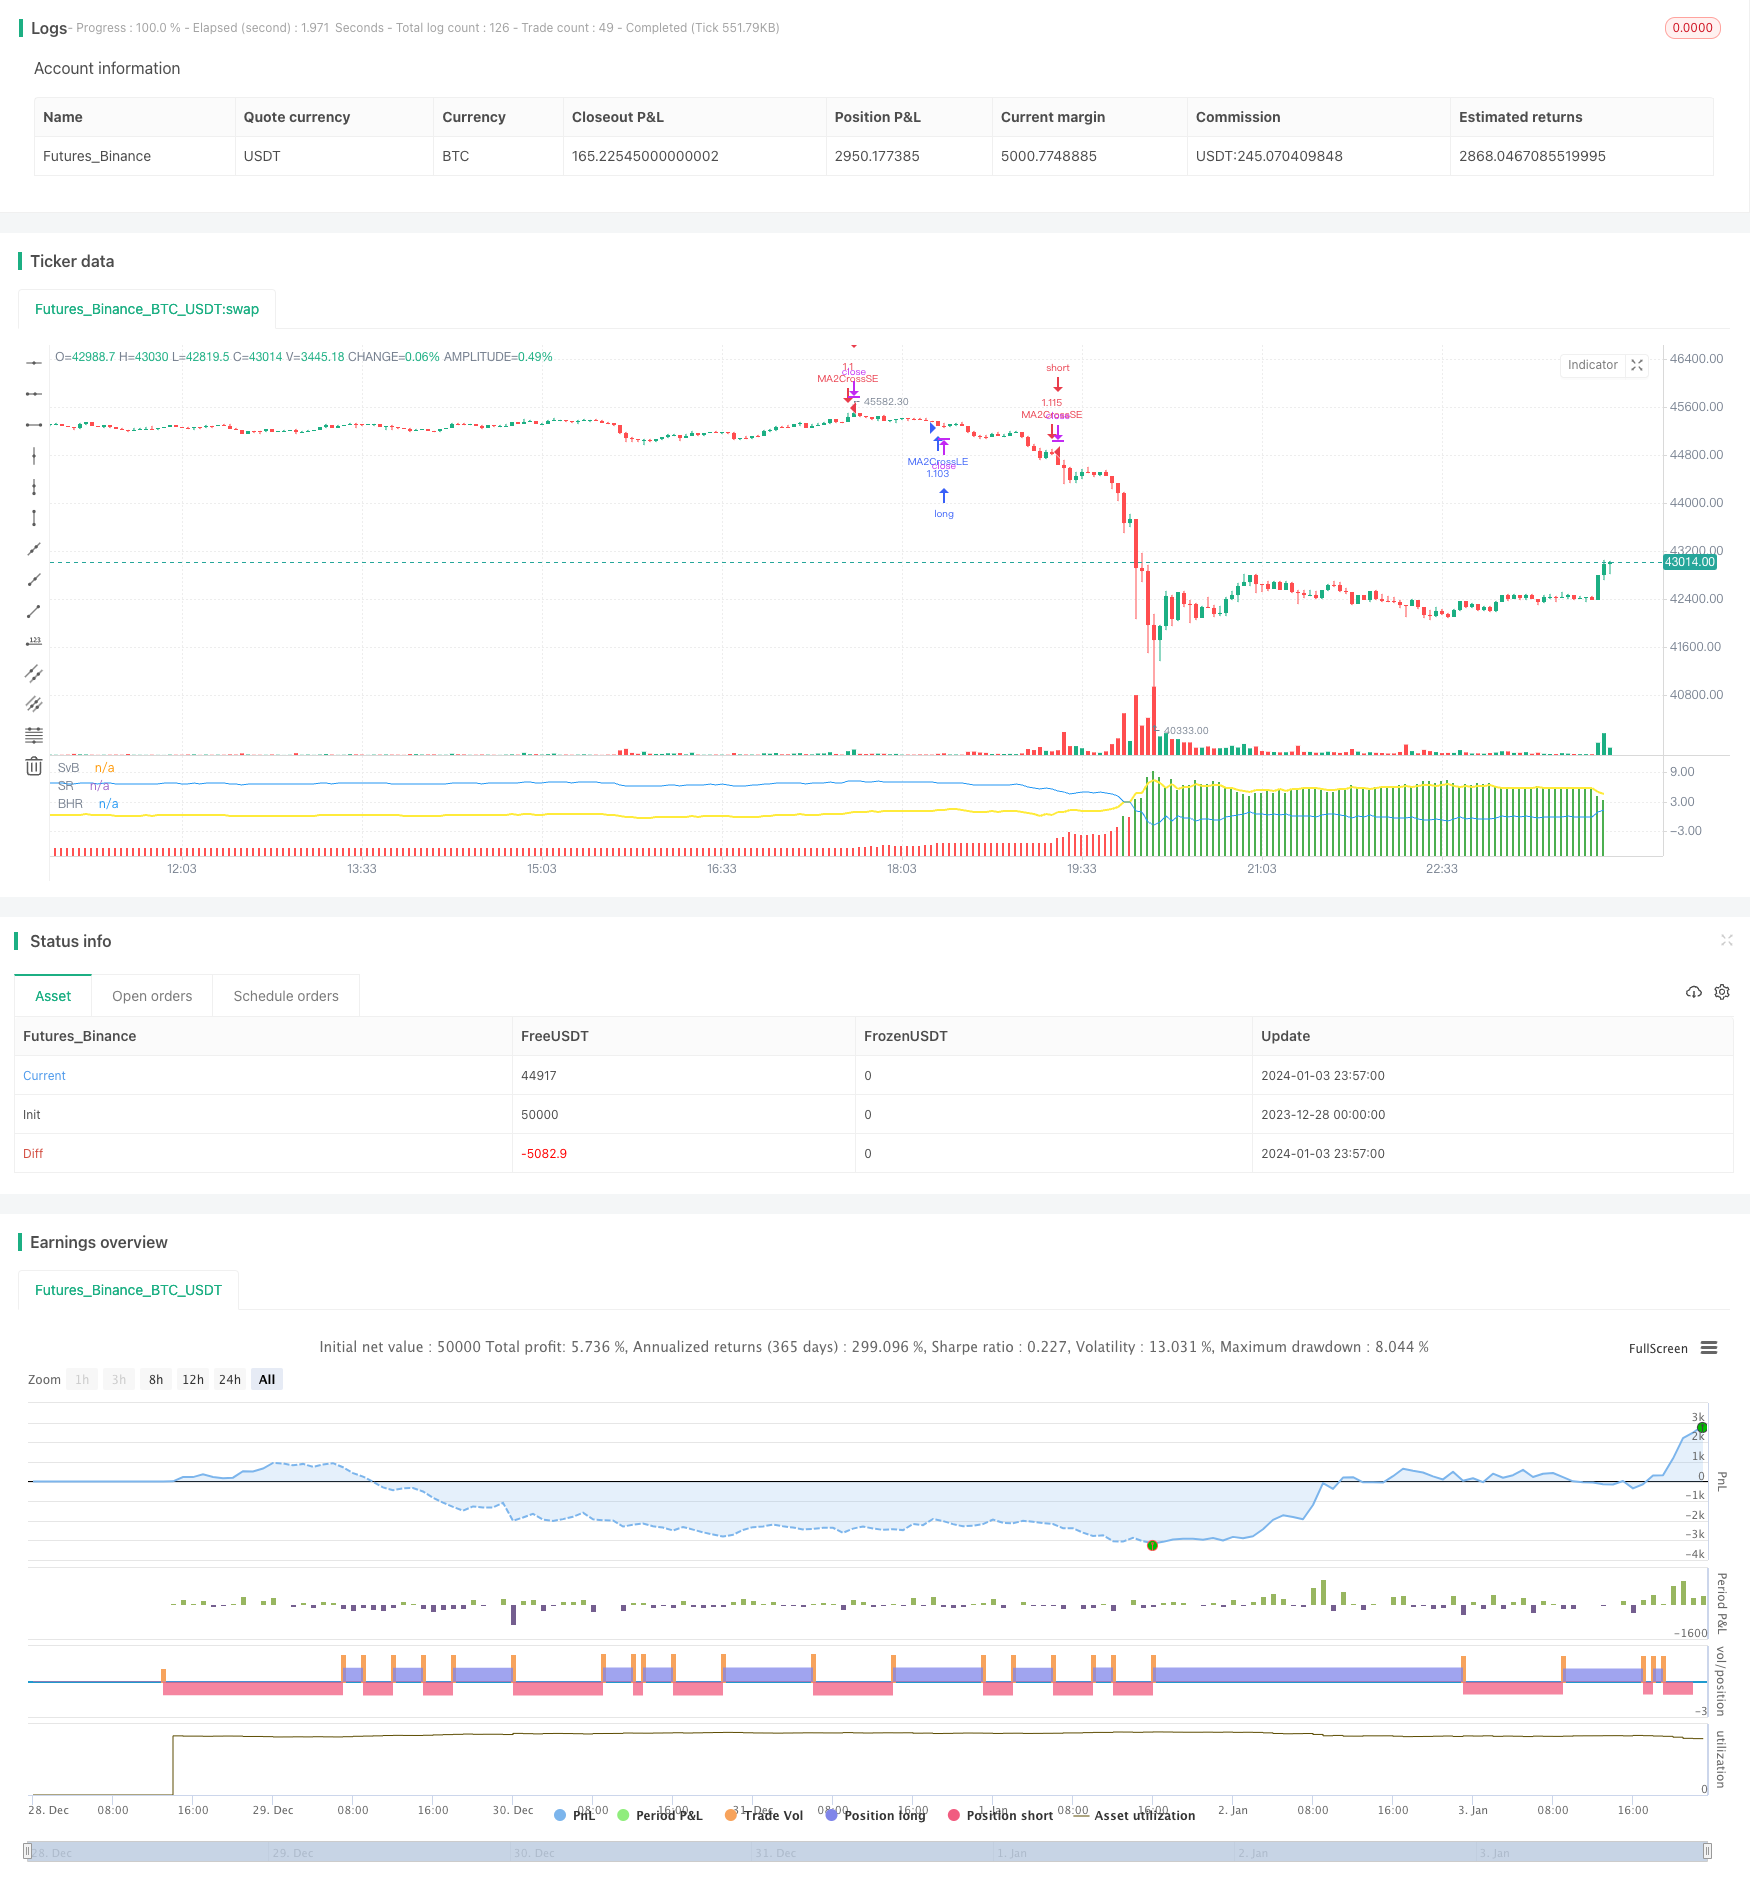
Overview
This strategy makes a detailed and visual comparison between a given strategy and the buy & hold returns of the traded security.
Strategy Logic
The core logic of this strategy is to plot four key elements for comparison between the given strategy and buy & hold strategy:
- Strategy P/L: strategy net profit + strategy open profit
- Buy & Hold P/L: unrealized return
- Difference: Strategy P/L - Buy & Hold P/L
- Strategy vs Buy Hold Stats
- Percent of bars strategy P/L is above Buy & Hold
- Percent of bars strategy P/L is below Buy & Hold
- All Time Average Difference
By comparing the above four elements, we can have an intuitive understanding on whether our strategy outperforms or underperforms a simple buy & hold strategy.
Advantage Analysis
Compared with a simple comparison of buy & hold returns, this strategy has the following advantages:
More comprehensive and detailed comparison metrics, including per bar comparisons and overall statistical comparisons, so that we know clearly when and where our strategy beats or loses to buy & hold.
Intuitive visual charts that plot the strategy P/L, buy & hold P/L and the difference between them. It allows us to visually tell the performance of our strategy faster.
Customizable comparison date range where we can focus on comparing our strategy vs buy & hold on specific periods.
Simple and easy to use. The comparison logic is built-in so that we only need to replace the strategy script section with our own. No need to code the comparison logic ourselves.
Risk Analysis
This strategy relies mainly on the built-in buy & hold return metrics of the trading platform for comparison. Any bias with that benchmark will affect the final result. Also, there may exist flaws in the statistical calculations of this strategy that fail to accurately reflect the comparison.
More benchmarks and statistical methods can be introduced for further validation. If the trading platform introduces significant changes to the buy & hold metric, the comparison logic here needs to be adjusted as well.
Optimization Directions
This strategy can be further optimized from the following aspects:
Introduce more benchmarks for 3-way or multi-way comparison, e.g. comparing against an index or industry peers.
Include more statistical metrics like annual win rate, maximum drawdown duration difference etc. for assessing the strategy from more dimensions.
Make more components like benchmarks, metrics etc customizable by users instead of just the date range.
Improve charting visualization since simple line charts here make it hard to spot detailed comparisons on specific bars. Column plots or additional markings can help.
Conclusion
With detailed comparison metrics and intuitive visual charts, this strategy allows us to have a very clear view on where and how our custom strategy differs from a simple buy & hold approach. The customizable date range also provides flexibility in analyzing the pros & cons of our strategy in different periods.
Further enriching the benchmarks, metrics and visualizations can turn this into an extremely powerful toolkit for strategy analysis. It provides a template and framework for making strategy analysis and enhancements much more efficient.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Enable Info Panel |
| v_input_2 | true | Enable Indicator Panel |
| v_input_3 | 1970 | From Year |
| v_input_4 | true | From Month |
| v_input_5 | true | From Day |
| v_input_6 | 2050 | To Year |
| v_input_7 | 12 | To Month |
| v_input_8 | 31 | To Day |
Source Pine Script
/*backtest
start: 2023-12-28 00:00:00
end: 2024-01-04 00:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("VS Buy Hold", precision=2)

bnh_info_panel = input(true, title='Enable Info Panel')
bnh_indicator_panel = input(true, title='Enable Indicator Panel')

//COMPARISON DATE RANGE//
bnh_FromYear = input(1970, title="From Year", minval=1970)
bnh_FromMonth = input(1, title="From Month", minval=1, maxval=12)
bnh_FromDay = input(1, title="From Day", minval=1, maxval=31)

bnh_ToYear = input(2050, title="To Year", minval=2010)
bnh_ToMonth = input(12, title="To Month", minval=1, maxval=12)
bnh_ToDay = input(31, title="To Day", minval=1, maxval=31)

bnh_start = timestamp(bnh_FromYear, bnh_FromMonth, bnh_FromDay, 00, 00)
bnh_finish = timestamp(bnh_ToYear, bnh_ToMonth, bnh_ToDay, 23, 59)
bnh_timeCond = time >= bnh_start and time <= bnh_finish ? true: false

//Note: If you are going to use the COMPARISON DATE RANGE above, apply bnh_timeCond
//      to your strategy parameters.


/////////////////////////////////////////////////////////////////////////////////////
//////////////////////////////STRATEGY SCRIPT START//////////////////////////////////

//=========================PLACEHOLDER MA CROSS STRATEGY=========================//
fastLength = 50
slowLength = 200
price = close

mafast = sma(price, fastLength)
maslow = sma(price, slowLength)
strategy.initial_capital = 50000
positionSize = strategy.initial_capital / close

if (crossover(mafast, maslow) and bnh_timeCond) // <= bnh_timeCond added as a condition
    strategy.entry("MA2CrossLE", strategy.long, positionSize, comment="MA2CrossLE")

if (crossunder(mafast, maslow) and bnh_timeCond) // <= bnh_timeCond added as a condition
    strategy.entry("MA2CrossSE", strategy.short, positionSize, comment="MA2CrossSE")

//////////////////////////////STRATEGY SCRIPT END////////////////////////////////////
/////////////////////////////////////////////////////////////////////////////////////


//STRATEGY EQUITY
strategy_pnl = strategy.netprofit + strategy.openprofit
bnh_strategy_pnl_pcnt = (strategy_pnl / strategy.initial_capital) * 100


//BUY AND HOLD EQUITY
float bnh_start_bar = na
bnh_start_bar := na(bnh_start_bar[1]) and bnh_timeCond? close : bnh_start_bar[1]
bnl_buy_hold_equity = ((close - bnh_start_bar)/bnh_start_bar) * 100


//STRATEGY VS BUY AND HOLD STATS
bnh_vs_diff = bnh_strategy_pnl_pcnt - bnl_buy_hold_equity

bnh_bar_counter = 0
bnh_bar_counter := bnh_vs_diff > 0 ? nz(bnh_bar_counter[1]) + 1 : bnh_bar_counter[1]

bnh_bar_counter2 = 0
bnh_bar_counter2 := bnh_vs_diff <= 0 ? nz(bnh_bar_counter2[1]) + 1 : bnh_bar_counter2[1]

bnh_pcnt_above = (bnh_bar_counter/(bnh_bar_counter + bnh_bar_counter2))*100
bnh_pcnt_below = (bnh_bar_counter2/(bnh_bar_counter + bnh_bar_counter2))*100

bnh_average_diff = cum(bnh_vs_diff) / (bnh_bar_counter + bnh_bar_counter2)


//PLOTS AND LABELS
bnh_diff_color = bnh_vs_diff > 0 ? color.green : color.red
plot(bnh_vs_diff, style=plot.style_columns, color=bnh_diff_color, transp=60, title='SvB')
plot(bnh_strategy_pnl_pcnt, color=color.yellow, linewidth=2, title="SR")
plot(bnl_buy_hold_equity, color=color.blue, title="BHR")

// draw_IndicatorLabel(_text, _x, _y, label_color, font_color)=>
//     string_text = _text
//     var label la_indicator = na
//     label.delete(la_indicator)
//     la_indicator := label.new(
//          x=_x, y=_y,
//          text=string_text, xloc=xloc.bar_index, yloc=yloc.price,
//          color=label_color, style=label.style_labeldown, textcolor=font_color, size=size.small)

// draw_InfoPanel(_text, _x, _y, font_size)=>
//     var label la_panel = na
//     label.delete(la_panel)
//     la_panel := label.new(
//          x=_x, y=_y,
//          text=_text, xloc=xloc.bar_time, yloc=yloc.price,
//          color=color.new(#383838, 5), style=label.style_labelup, textcolor=color.white, size=font_size)

// if bnh_indicator_panel
//     draw_IndicatorLabel("Difference", bar_index, bnh_vs_diff, color.new(color.gray, 40), color.white)
//     draw_IndicatorLabel("Strategy P/L", bar_index, bnh_strategy_pnl_pcnt, color.new(color.yellow, 50), color.white)
//     draw_IndicatorLabel("Buy & Hold P/L", bar_index, bnl_buy_hold_equity, color.new(color.blue, 50), color.white)

// info_panel_x = time_close + round(change(time) * 200)
// info_panel_y = max(max(bnl_buy_hold_equity, bnh_strategy_pnl_pcnt), bnh_vs_diff) + abs(bnh_vs_diff * 0.25)


// title = "STRATEGY vs BUY & HOLD STATS"
// row0 = "-----------------------------------------------------"
// row1 = 'Bars Above Buy & Hold: ' + tostring(bnh_pcnt_above, '#.##') + '%'
// row2 = 'Bars Below Buy & Hold: ' + tostring(bnh_pcnt_below, '#.##') + '%'
// row3 = 'All Time Ave. Difference: ' + tostring(bnh_average_diff, '#.##') + '%'

// panel_text = '\n' + title + '\n' + row0 + '\n' + row1 + '\n\n' + row2 + '\n\n' + row3 + '\n'

// if bnh_info_panel
//     draw_InfoPanel(panel_text, info_panel_x, info_panel_y, size.normal)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Visual-Comparison-between-Strategy-and-Buy-Hold-Returns.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Angle Attack Follow Line IndicatorPine Script · Other · 15m
- Customizable Backtest Start Time StrategyPine Script · Other · 2d
- Gann High LowPine Script · Other · 4h
- MACD StrategyPine Script · Other
- Monthly Performance PnL Calendar StrategyPine Script · Other · 1d
- QQE MOD SSL Hybrid Waddah Attar ExplosionPine Script · Other · 4h