Strategy vault / Trend following
Volatility Bands and VWAP Multi Timeframe Stock Trend Trading Strategy
The strategy is mainly used for trend tracking of stock products. By calculating the ATR volatility and combining VWAP prices of different periods, it sets buy and sell conditions to judge and track trends. The…
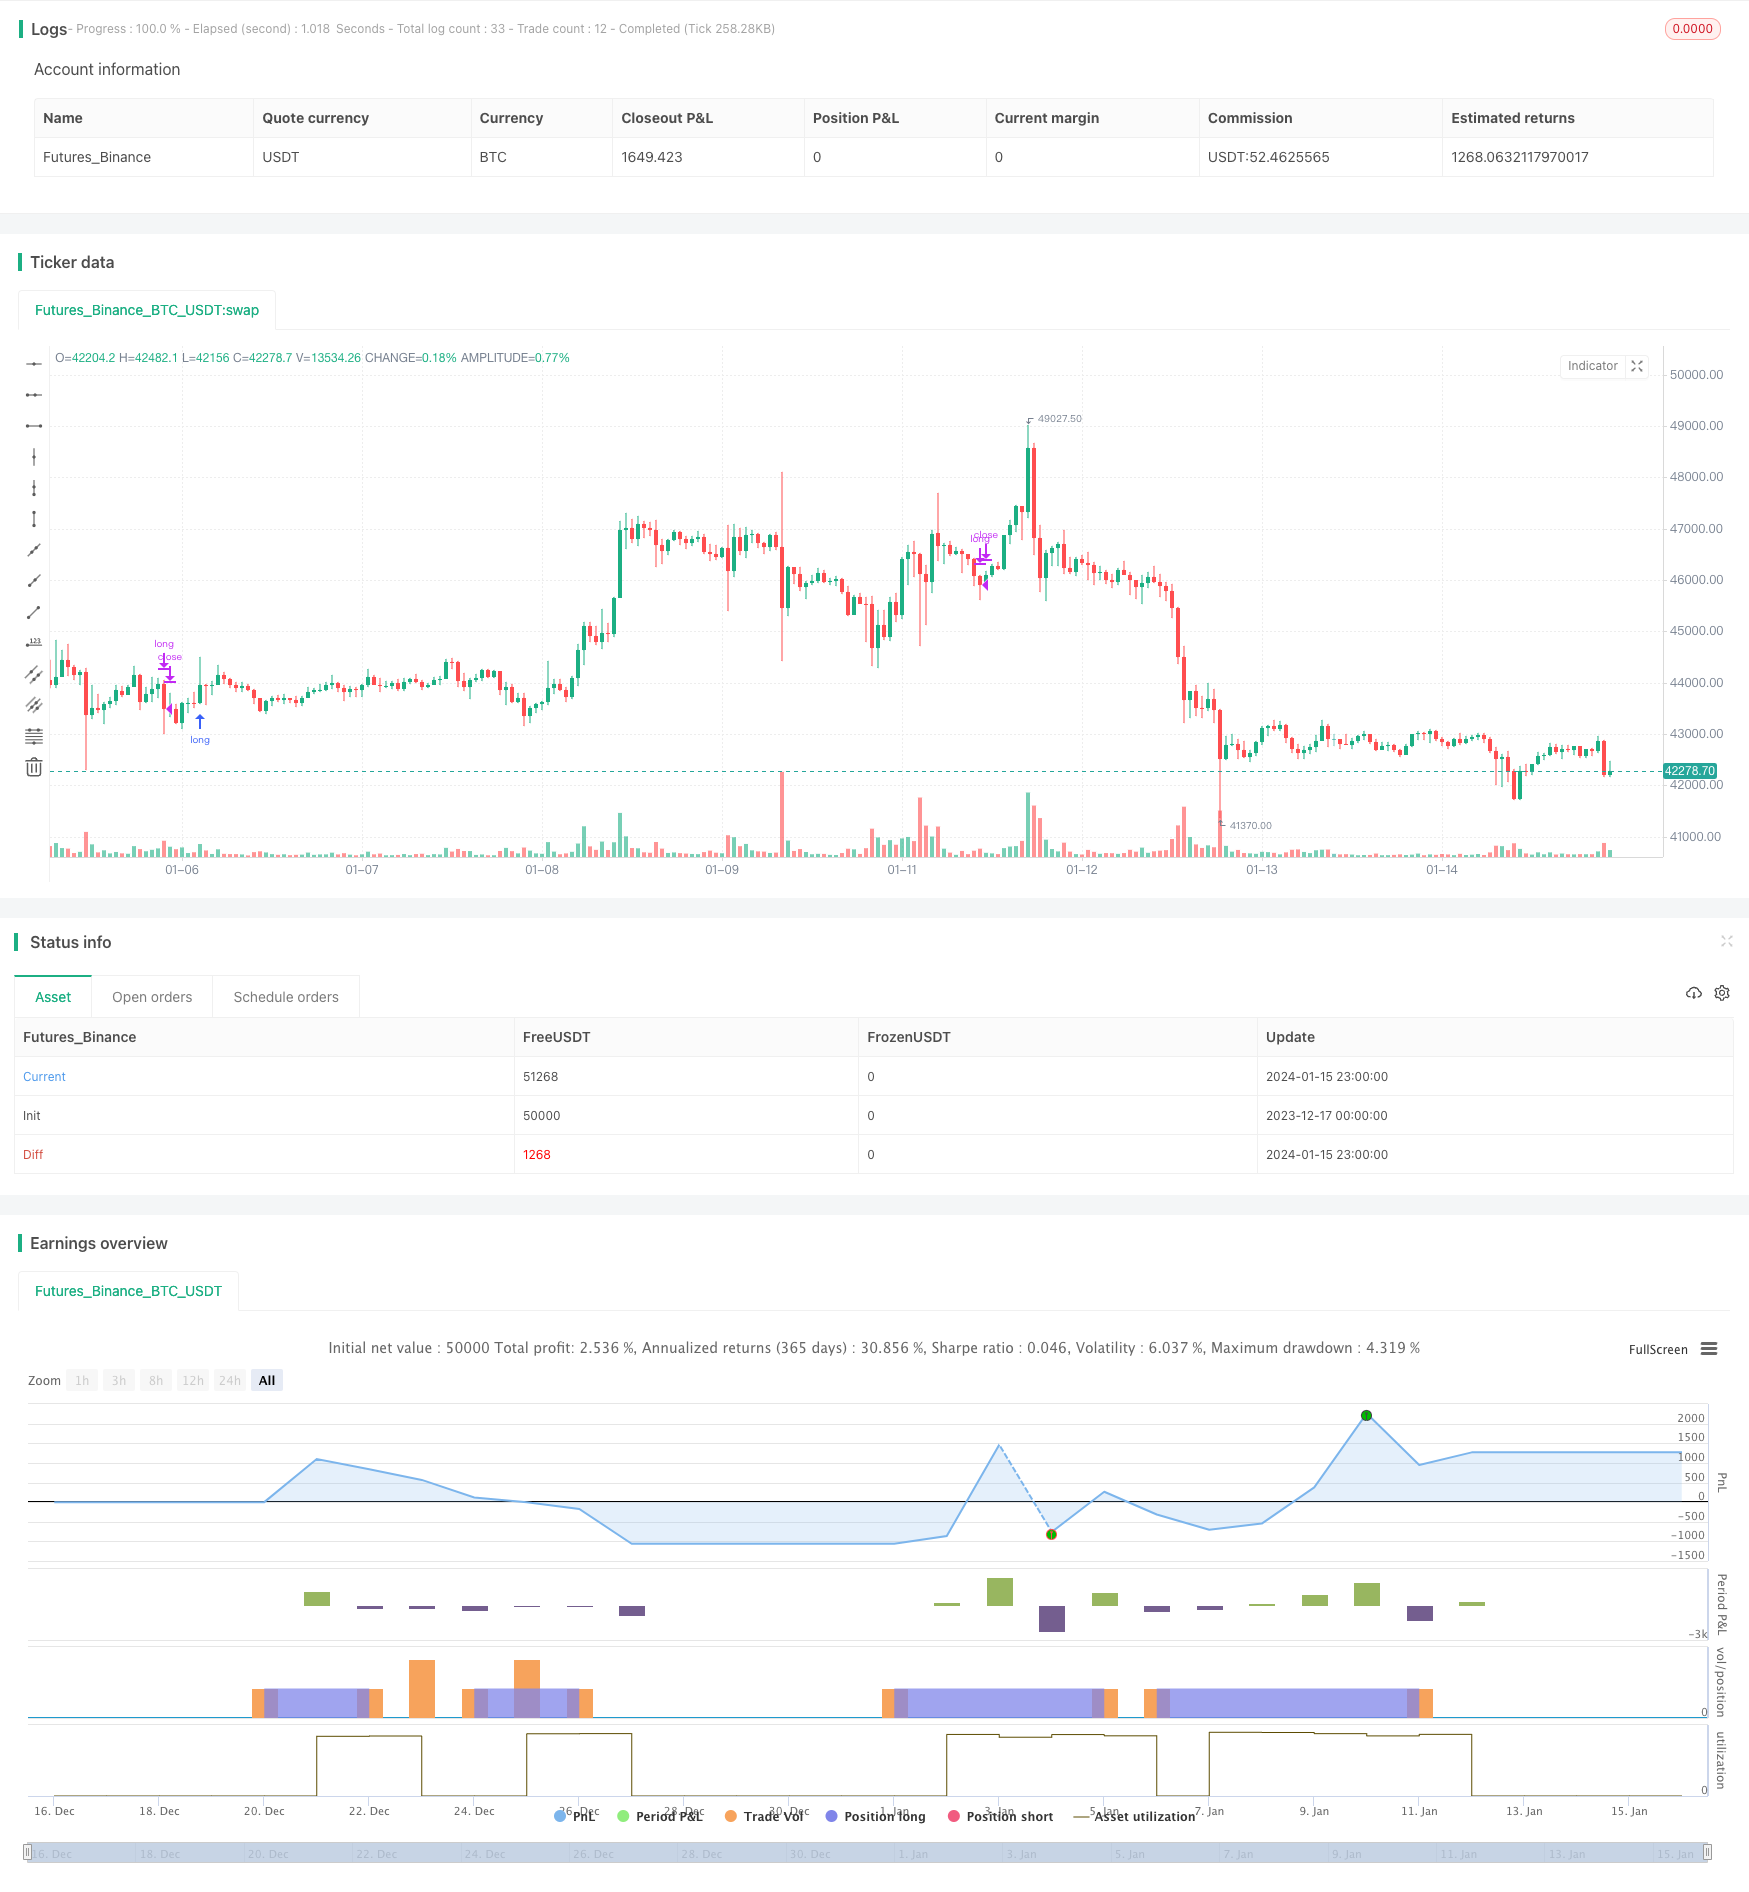
This strategy calculates the ATR volatility of price and combines different period VWAP to set long entry and exit conditions for stock trend trading.
Strategy Overview
The strategy is mainly used for trend tracking of stock products. By calculating the ATR volatility and combining VWAP prices of different periods, it sets buy and sell conditions to judge and track trends. The strategy is flexible enough to switch between long term and short term, suitable for capturing medium and long term trends.
Strategy Logic
The strategy uses the ATR indicator to calculate price volatility and judges the trend direction based on whether the price breaks through the volatility channel. At the same time, it introduces VWAP prices of different cycles to determine the consistency of long and short term trends. The specific logic is as follows:
- Calculate the ATR volatility channel of the price
- Judge if the price breaks through the volatility channel
- Breaking through the upper rail indicates a bullish trend
- Breaking through the lower rail indicates a bearish trend
- Introduce weekly and daily VWAP prices
- When the price breaks through the upper volatility rail, if both daily and weekly VWAPs are above the price, a long signal is generated
- When the price breaks through the lower volatility rail, if both daily and weekly VWAPs are below the price, a short signal is generated
The above is the core logic of the strategy. The ATR volatility judges the short-term trend and the VWAP price judges the long-term trend. The two are combined to determine the consistency of the trend and thus generate trading signals.
Advantages of the Strategy
- Use a combination of ATR and VWAP to judge trends, more reliable
- Customizable ATR period parameter to adjust strategy sensitivity
- Introducing multi-timeframe VWAP to determine long and short term trend consistency
- Flexible to switch between long term and short term
- Suitable for tracking medium and long term stock trends
Risks and Optimization
- As a trend following strategy, it may generate more trades during consolidation, bringing slippage risks
- ATR and VWAP parameter settings impact strategy performance, require careful testing against different products
- Consider adding stop loss to control single trade loss
- Can combine with MA and other indicators to filter entry signals and reduce unnecessary trades
Summary
The strategy realizes stock trend tracking through dual confirmation of ATR volatility and VWAP. There is ample room for optimization by adjusting parameters or incorporating other technical indicators. Overall, the strategy logic is clear and robust for tracking medium to long term trends.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 27 | length |
| v_input_2 | false | mult |
| v_input_3 | true | From Day |
| v_input_4 | true | From Month |
| v_input_5 | 2000 | From Year |
| v_input_6 | 31 | To Day |
| v_input_7 | 12 | To Month |
| v_input_8 | 2021 | To Year |
| v_input_9_ohlc4 | 0 | srcX: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
Source Pine Script
/*backtest
start: 2023-12-17 00:00:00
end: 2024-01-16 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © exlux99

//@version=4
strategy(title="VWAP MTF STOCK STRATEGY", overlay=true )

// high^2 / 2 - low^2 -2

h=pow(high,2) / 2
l=pow(low,2) / 2

o=pow(open,2) /2
c=pow(close,2) /2


x=(h+l+o+c) / 4
y= sqrt(x)

source = y
useTrueRange = false
length = input(27, minval=1)
mult = input(0, step=0.1)
ma = sma(source, length)
range = useTrueRange ? tr : high - low
rangema = sma(range, length)
upper = ma + rangema * mult
lower = ma - rangema * mult
crossUpper = crossover(source, upper)
crossLower = crossunder(source, lower)
bprice = 0.0
bprice := crossUpper ? high+syminfo.mintick : nz(bprice[1])
sprice = 0.0
sprice := crossLower ? low -syminfo.mintick : nz(sprice[1])
crossBcond = false
crossBcond := crossUpper ? true
     : na(crossBcond[1]) ? false : crossBcond[1]
crossScond = false
crossScond := crossLower ? true
     : na(crossScond[1]) ? false : crossScond[1]
cancelBcond = crossBcond and (source < ma or high >= bprice )
cancelScond = crossScond and (source > ma or low <= sprice )

longOnly = true

fromDay = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
fromMonth = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
fromYear = input(defval = 2000, title = "From Year", minval = 1970)
 //monday and session
// To Date Inputs
toDay = input(defval = 31, title = "To Day", minval = 1, maxval = 31)
toMonth = input(defval = 12, title = "To Month", minval = 1, maxval = 12)
toYear = input(defval = 2021, title = "To Year", minval = 1970)

startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)
time_cond = true

srcX = input(ohlc4)
t = time("W")
start = na(t[1]) or t > t[1]

sumSrc = srcX * volume
sumVol = volume
sumSrc := start ? sumSrc : sumSrc + sumSrc[1]
sumVol := start ? sumVol : sumVol + sumVol[1]

vwapW= sumSrc / sumVol


//crossUpper = crossover(source, upper)
//crossLower = crossunder(source, lower)
shortCondition = close < vwap and time_cond and (close < vwapW)
longCondition = close > vwap and time_cond and (close > vwapW)


if(longOnly and time_cond)
    if (crossLower and close < vwapW )
        strategy.close("long")
    if (crossUpper and close>vwapW)
        strategy.entry("long", strategy.long, stop=bprice)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Volatility-Bands-and-VWAP-Multi-Timeframe-Stock-Trend-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Trend Following Strategy Based on Moving Average 439858Pine Script · Trend following · 1d
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- WaveTrend Oscillator Divergence StrategyPine Script · Trend following · 1d
- An Optimization of Dual Moving Average Trend Following Strategy Based on Indicators CombinationPine Script · Trend following · 4h
- Multi Timeframe Volume and Trend Confluence Trading StrategyPine Script · Trend following · 1d