Volatility Finite Volume Elements Strategy
This strategy is an improvement based on the Finite Volume Elements (FVE) indicator. FVE is a pure volume indicator that does not consider price changes, but only focuses on fund inflows and outflows. This strategy…
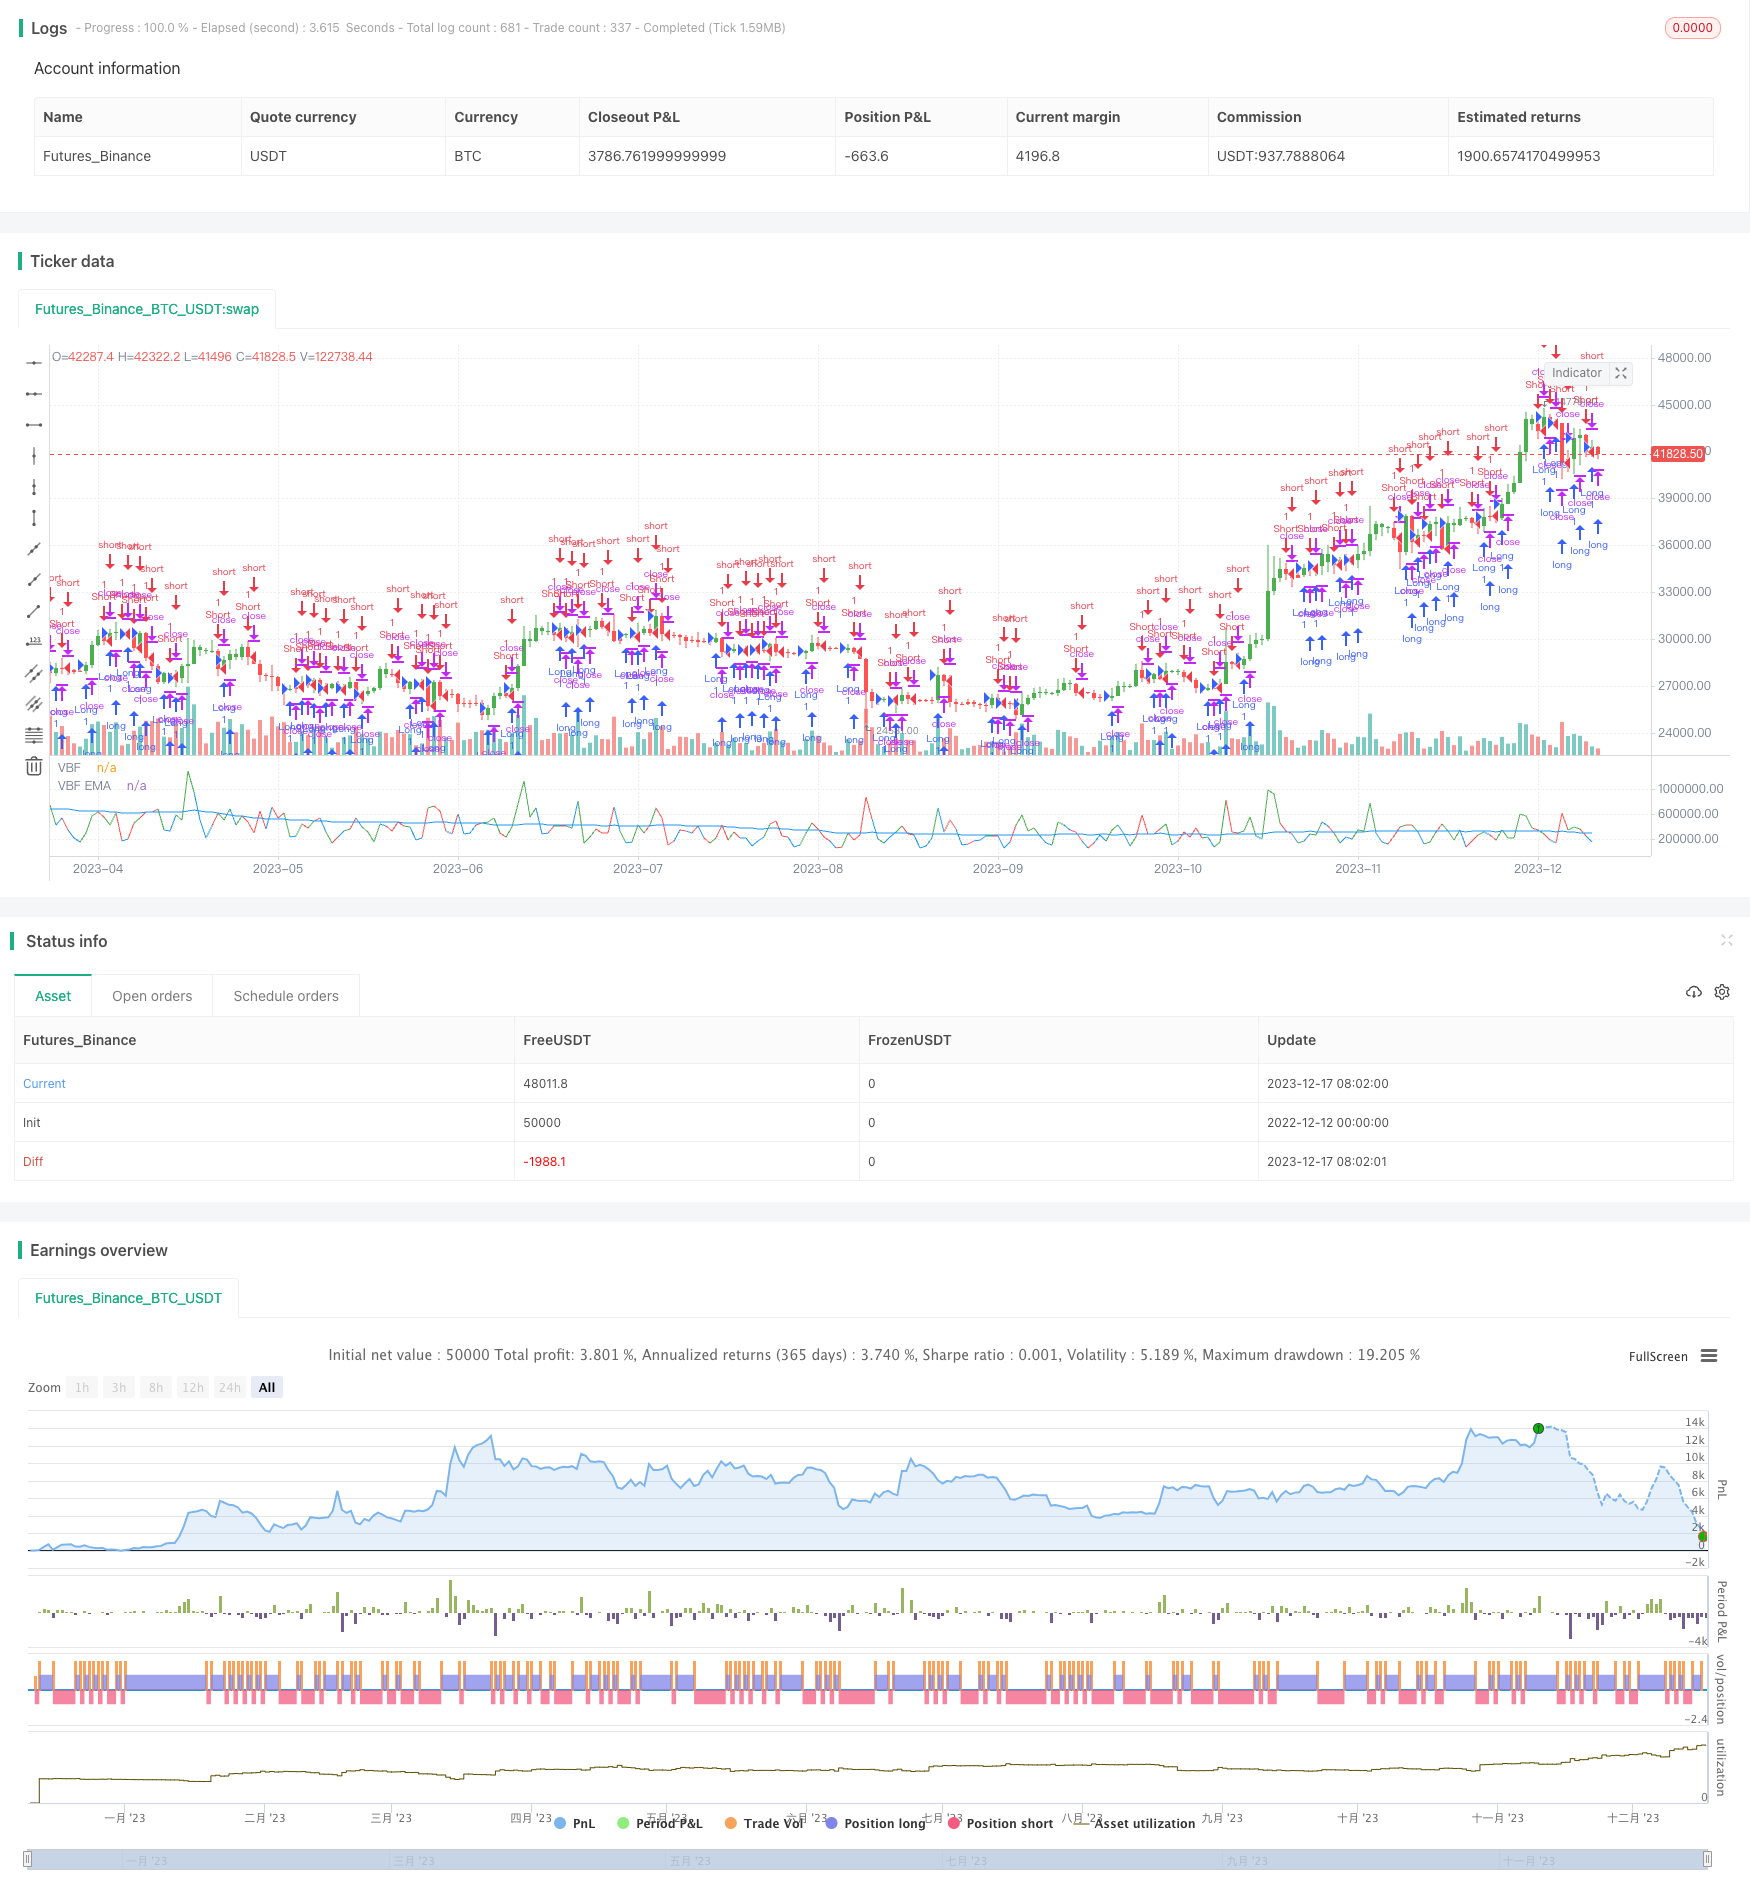
Overview
This strategy is an improvement based on the Finite Volume Elements (FVE) indicator. FVE is a pure volume indicator that does not consider price changes, but only focuses on fund inflows and outflows. This strategy colors trading volume based on volatility on the basis of FVE to judge market sentiment and fund flows.
Strategy Principle
The strategy calculates intraday volatility Intra and interday volatility Inter, combined with their standard deviations Vintra and Vinter, to obtain the volatility threshold CutOff. Then it calculates the difference MF between median price, previous median price and volume to judge fund inflow (positive) or outflow (negative). If MF exceeds CutOff, it means trading volume and volatility are in the same direction and there is obvious enthusiasm in the market, the color is set to green; if MF is below negative CutOff, it means trading volume and volatility are in the same direction and there is obvious pessimism in the market, the color is set to red; otherwise the color is blue. Finally, determine the long/short direction based on color.
Advantage Analysis
The strategy combines trading volume and volatility indicators to judge market sentiment more accurately. Compared with single indicators, it has the advantages of stability and reliability in judgment. In addition, the judgment criteria of this strategy are specially designed for volatility and can adapt well to changes in different market conditions.
Risk Analysis
The strategy relies on trading volume and volatility indicators. Discrepancies between the two will affect judgment. In addition, parameter settings have a greater impact on results, with large differences in results from different varieties and parameter combinations, requiring targeted optimization.
Optimization Directions
Consider combining other indicators to assist in judgment, such as MACD, OBV, etc., to avoid noise from trading volume and volatility. It is also possible to design an adaptive parameter mechanism to dynamically adjust parameters according to different market conditions to improve stability. Or we can backtest and optimize parameters to find the best parameter portfolio for specific varieties.
Summary
The strategy integrates the advantages of trading volume and volatility indicators to judge the level of market enthusiasm. Compared with single indicators, it has higher judgment accuracy and stability. However, parameter settings and variety differences have significant effects on the results, and further optimization and adjustment are still needed to adapt to various trading environments. Overall, the strategy has a reasonable theoretical basis and great potential for improvement.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 22 | Samples |
| v_input_2 | 50 | AvgLength |
| v_input_3 | 70 | AlertPct |
| v_input_4 | 0.1 | Cintra |
| v_input_5 | 0.1 | Cinter |
| v_input_6 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2022-12-12 00:00:00
end: 2023-12-18 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 22/08/2017
// The FVE is a pure volume indicator. Unlike most of the other indicators
// (except OBV), price change doesn?t come into the equation for the FVE
// (price is not multiplied by volume), but is only used to determine whether
// money is flowing in or out of the stock. This is contrary to the current trend
// in the design of modern money flow indicators. The author decided against a
// price-volume indicator for the following reasons:
// - A pure volume indicator has more power to contradict.
// - The number of buyers or sellers (which is assessed by volume) will be the same,
// regardless of the price fluctuation.
// - Price-volume indicators tend to spike excessively at breakouts or breakdowns.
// This study is an addition to FVE indicator. Indicator plots different-coloured volume
// bars depending on volatility.
//
// You can change long to short in the Input Settings
// Please, use it only for learning or paper trading. Do not for real trading.
////////////////////////////////////////////////////////////
strategy(title="Volatility Finite Volume Elements Strategy", shorttitle="FVI")
Samples = input(22, minval=1)
AvgLength = input(50, minval=1)
AlertPct = input(70, minval=1)
Cintra = input(0.1, step = 0.1)
Cinter = input(0.1, step = 0.1)
reverse = input(false, title="Trade reverse")
xVolume = volume
xClose = close
xhl2 = hl2
xhlc3 = hlc3
xMA = sma(xVolume, AvgLength)
xIntra = log(high) - log(low)
xInter = log(xhlc3) - log(xhlc3[1])
xStDevIntra = stdev(xIntra, Samples)
xStDevInter = stdev(xInter, Samples)
TP = xhlc3
TP1 = xhlc3[1]
Intra = xIntra
Vintra = xStDevIntra
Inter = xInter
Vinter = xStDevInter
CutOff = Cintra * Vintra + Cinter * Vinter
MF = xClose - xhl2 + TP - TP1
clr = iff(MF > CutOff * xClose, green,
             iff(MF < -1 * CutOff * xClose, red,  blue))
pos = iff(MF > CutOff * xClose, 1,
	   iff(MF < -1 * CutOff * xClose, -1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(xVolume, color=clr, title="VBF")
plot(xMA, color=blue, title="VBF EMA")Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Volatility-Finite-Volume-Elements-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Dynamic Position Size Volatility Adaptive Quantitative Trading StrategyPine Script · Volatility · 1d
- Profit rate theory volatility index quantification strategyPine Script · Volatility · 3h
- Adaptive Volatility Finite Volume Elements StrategyPine Script · Volatility · 1d
- DEMA Volatility Index StrategyPine Script · Volatility · 1d
- Dual Moving Average Volatility Tracking StrategyPine Script · Volatility · 1h
- Multi Indicator Dynamic Volatility Alert Trading SystemPine Script · Volatility · 1m