Volume Spike and RSI Enhanced Trading Strategy
This strategy is a trading system based on volume anomalies and RSI indicators. It identifies potential trading opportunities by monitoring volume breakouts and RSI overbought/oversold levels, combined with price…
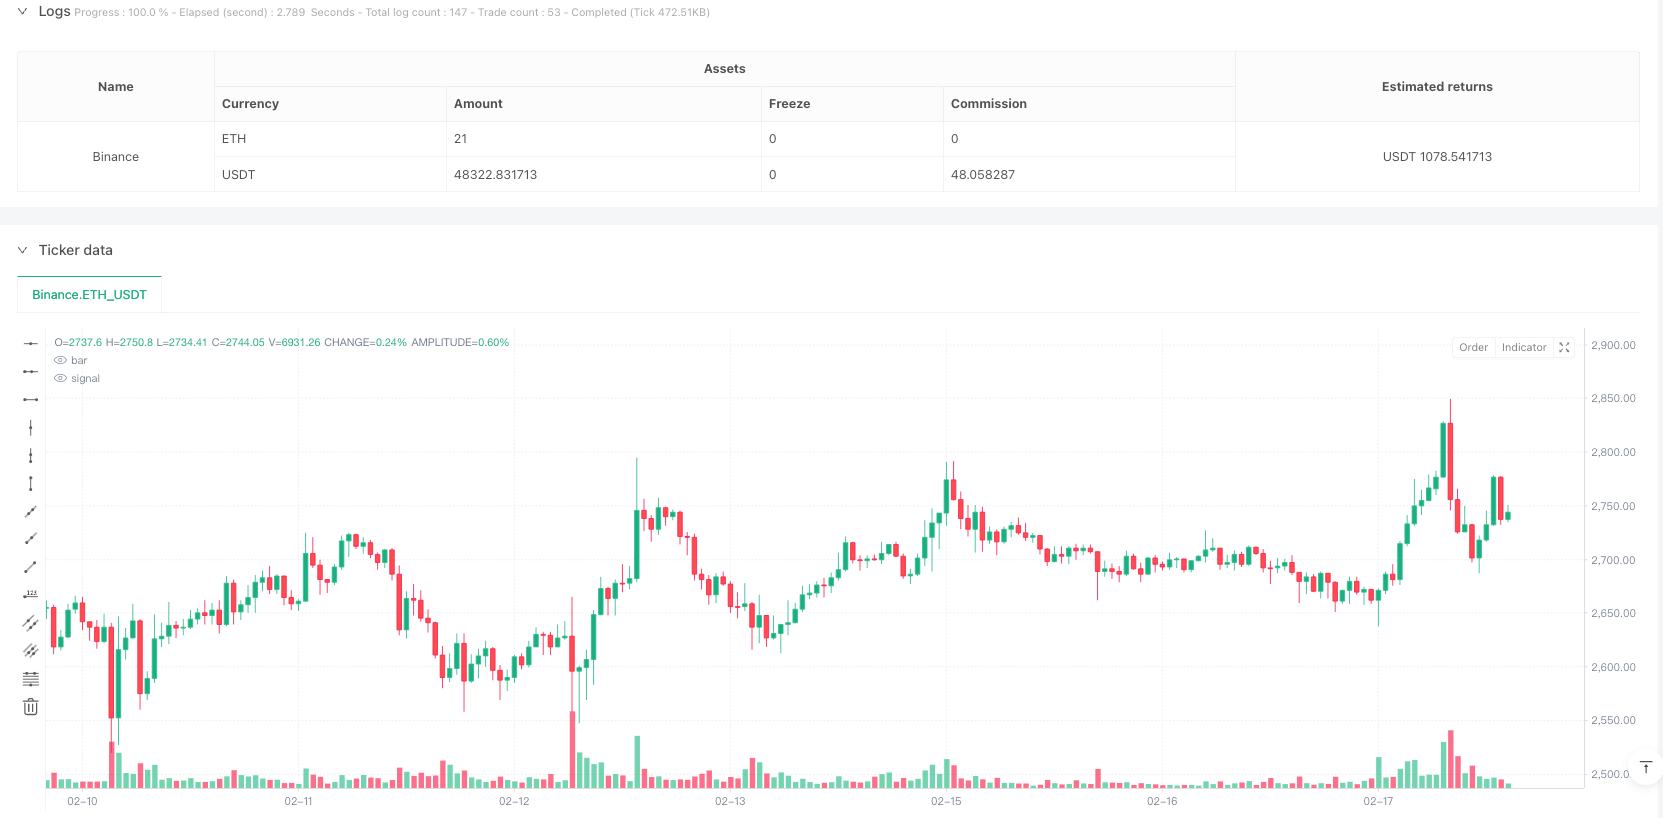
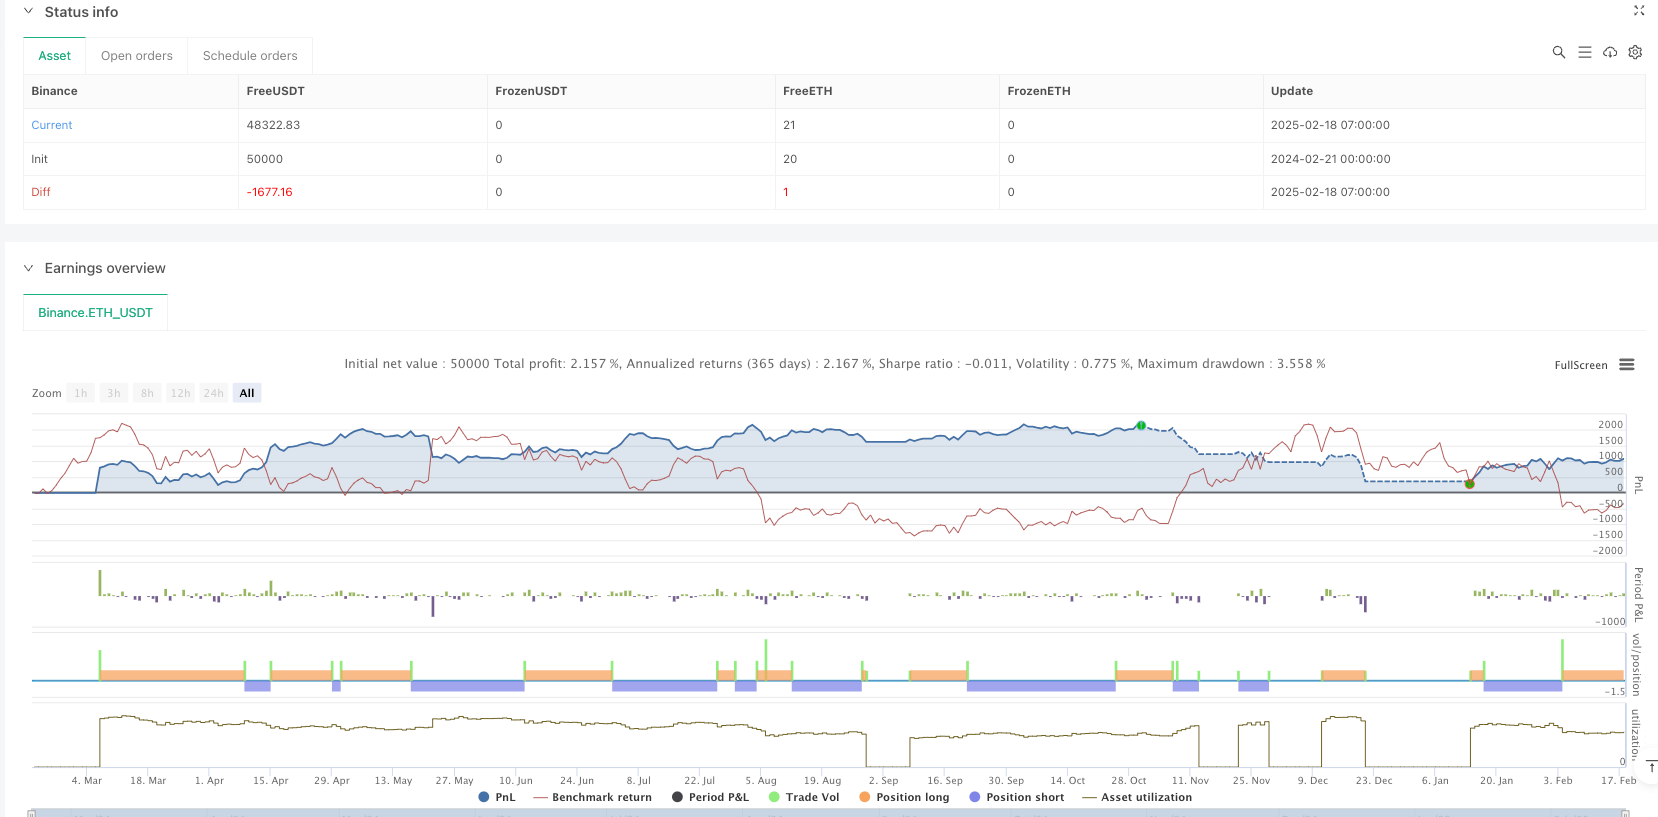
Overview
This strategy is a trading system based on volume anomalies and RSI indicators. It identifies potential trading opportunities by monitoring volume breakouts and RSI overbought/oversold levels, combined with price action confirmation. The strategy employs dynamic stop-loss and take-profit targets to optimize risk-reward configuration.
Strategy Principles
The core logic includes several key elements:
- Volume Verification: Uses 20-period SMA to calculate average volume, triggering volume spike signals when real-time volume exceeds 1.5 times the average
- RSI Indicator: Employs 14-period RSI for overbought/oversold detection, with RSI<30 considered oversold and RSI>70 overbought
- Entry Conditions:
- Long: Volume spike + RSI oversold + closing price above opening price
- Short: Volume spike + RSI overbought + closing price below opening price
- Risk Management: Uses ATR for dynamic stop-loss calculation and automatically determines profit targets based on set risk-reward ratio (1:2)
Strategy Advantages
- Multiple Confirmation Mechanism: Combines volume, RSI, and price action dimensions for trade confirmation, improving signal reliability
- Dynamic Risk Management: Adjusts stop-loss positions through ATR, better adapting to market volatility changes
- All-Session Applicability: Not restricted by time, capable of capturing trading opportunities around the clock
- High Customizability: Key parameters like RSI thresholds, volume multiplier, risk-reward ratio can be adjusted according to specific needs
- Clear Visualization: Marks trading signals with background colors, facilitating strategy monitoring and backtesting analysis
Strategy Risks
- False Breakout Risk: Volume spikes may arise from market noise, requiring optimization through volume multiplier parameter adjustment
- Off-Hours Risk: During periods of low market liquidity, slippage or execution difficulties may occur
- Market Environment Dependency: Strategy may perform better in trending markets than ranging markets
- Parameter Sensitivity: Multiple key parameter settings significantly affect strategy performance, requiring thorough testing
Strategy Optimization Directions
- Market State Recognition: Add market condition assessment mechanism to use different parameter settings under different market conditions
- Signal Filtering: Add trend filters, such as moving average systems, to improve trade direction accuracy
- Position Management: Introduce dynamic position sizing mechanism, adjusting position size based on market volatility
- Volume Analysis Enhancement: Incorporate volume pattern analysis, such as volume up/down ratio indicators, to improve volume anomaly detection accuracy
- Liquidity Assessment: Add liquidity evaluation indicators to adjust or pause trading during periods of insufficient liquidity
Summary
The strategy integrates multiple classic technical indicators to build a logically rigorous trading system. Its strengths lie in multiple confirmation mechanisms and comprehensive risk management system, while attention needs to be paid to false breakouts and off-hours risks. Through continuous optimization and improvement, the strategy shows promise for stable performance in actual trading.
Source Pine Script
/*backtest
start: 2024-02-21 00:00:00
end: 2025-02-18 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
*/

//@version=6
strategy("Volume Spike & RSI Scalping (Session Restricted)", overlay=true)

// Inputs
rsi_length = input(14, title="RSI Length")
overSold = input(30, title="RSI Oversold Level")
overBought = input(70, title="RSI Overbought Level")
volume_threshold = input(1.5, title="Volume Spike Multiplier (e.g., 1.5x avg volume)")
risk_reward_ratio = input(2.0, title="Risk-Reward Ratio (1:X)")
atr_length = input(14, title="ATR Length")


// RSI Calculation
vrsi = ta.rsi(close, rsi_length)

// Volume Spike Detection
avg_volume = ta.sma(volume, 20)
volume_spike = volume > avg_volume * volume_threshold

// Entry Signals Based on RSI and Volume
long_condition = volume_spike and vrsi < overSold and close > open // Bullish price action
short_condition = volume_spike and vrsi > overBought and close < open // Bearish price action

// Execute Trades
if (long_condition)
    stop_loss = low - ta.atr(atr_length)
    take_profit = close + (close - stop_loss) * risk_reward_ratio
    strategy.entry("Buy", strategy.long, comment="Buy Signal")
    strategy.exit("Take Profit/Stop Loss", "Buy", stop=stop_loss, limit=take_profit)

if (short_condition)
    stop_loss = high + ta.atr(atr_length)
    take_profit = close - (stop_loss - close) * risk_reward_ratio
    strategy.entry("Sell", strategy.short, comment="Sell Signal")
    strategy.exit("Take Profit/Stop Loss", "Sell", stop=stop_loss, limit=take_profit)

// Background Highlighting for Signals
bgcolor(long_condition ? color.new(color.green, 85) : na, title="Long Signal Background")
bgcolor(short_condition ? color.new(color.red, 85) : na, title="Short Signal Background")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Volume-Spike-and-RSI-Enhanced-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Multi Indicator Trend Breakout Strategy with Dynamic Stop LossPine Script · Breakout · 1d
- Advanced Long Only Dynamic Trendline Breakout StrategyPine Script · Breakout · 1d
- Dynamic Trend Momentum Breakout StrategyPine Script · Breakout · 1d
- Enhanced Bollinger Breakout Quantitative Strategy with Momentum Filter Integration SystemPine Script · Breakout · 2d
- High Precision RSI and Bollinger Bands Breakout Strategy with Optimized Risk Reward RatioPine Script · Breakout · 1h