Strategy vault / Trend following
VWAP Crossover Dynamic Profit Target Trading Strategy
The VWAP Crossover Dynamic Profit Target Trading Strategy is a quantitative trading approach that combines Volume Weighted Average Price (VWAP) crossover signals with a fixed percentage profit target. This strategy…
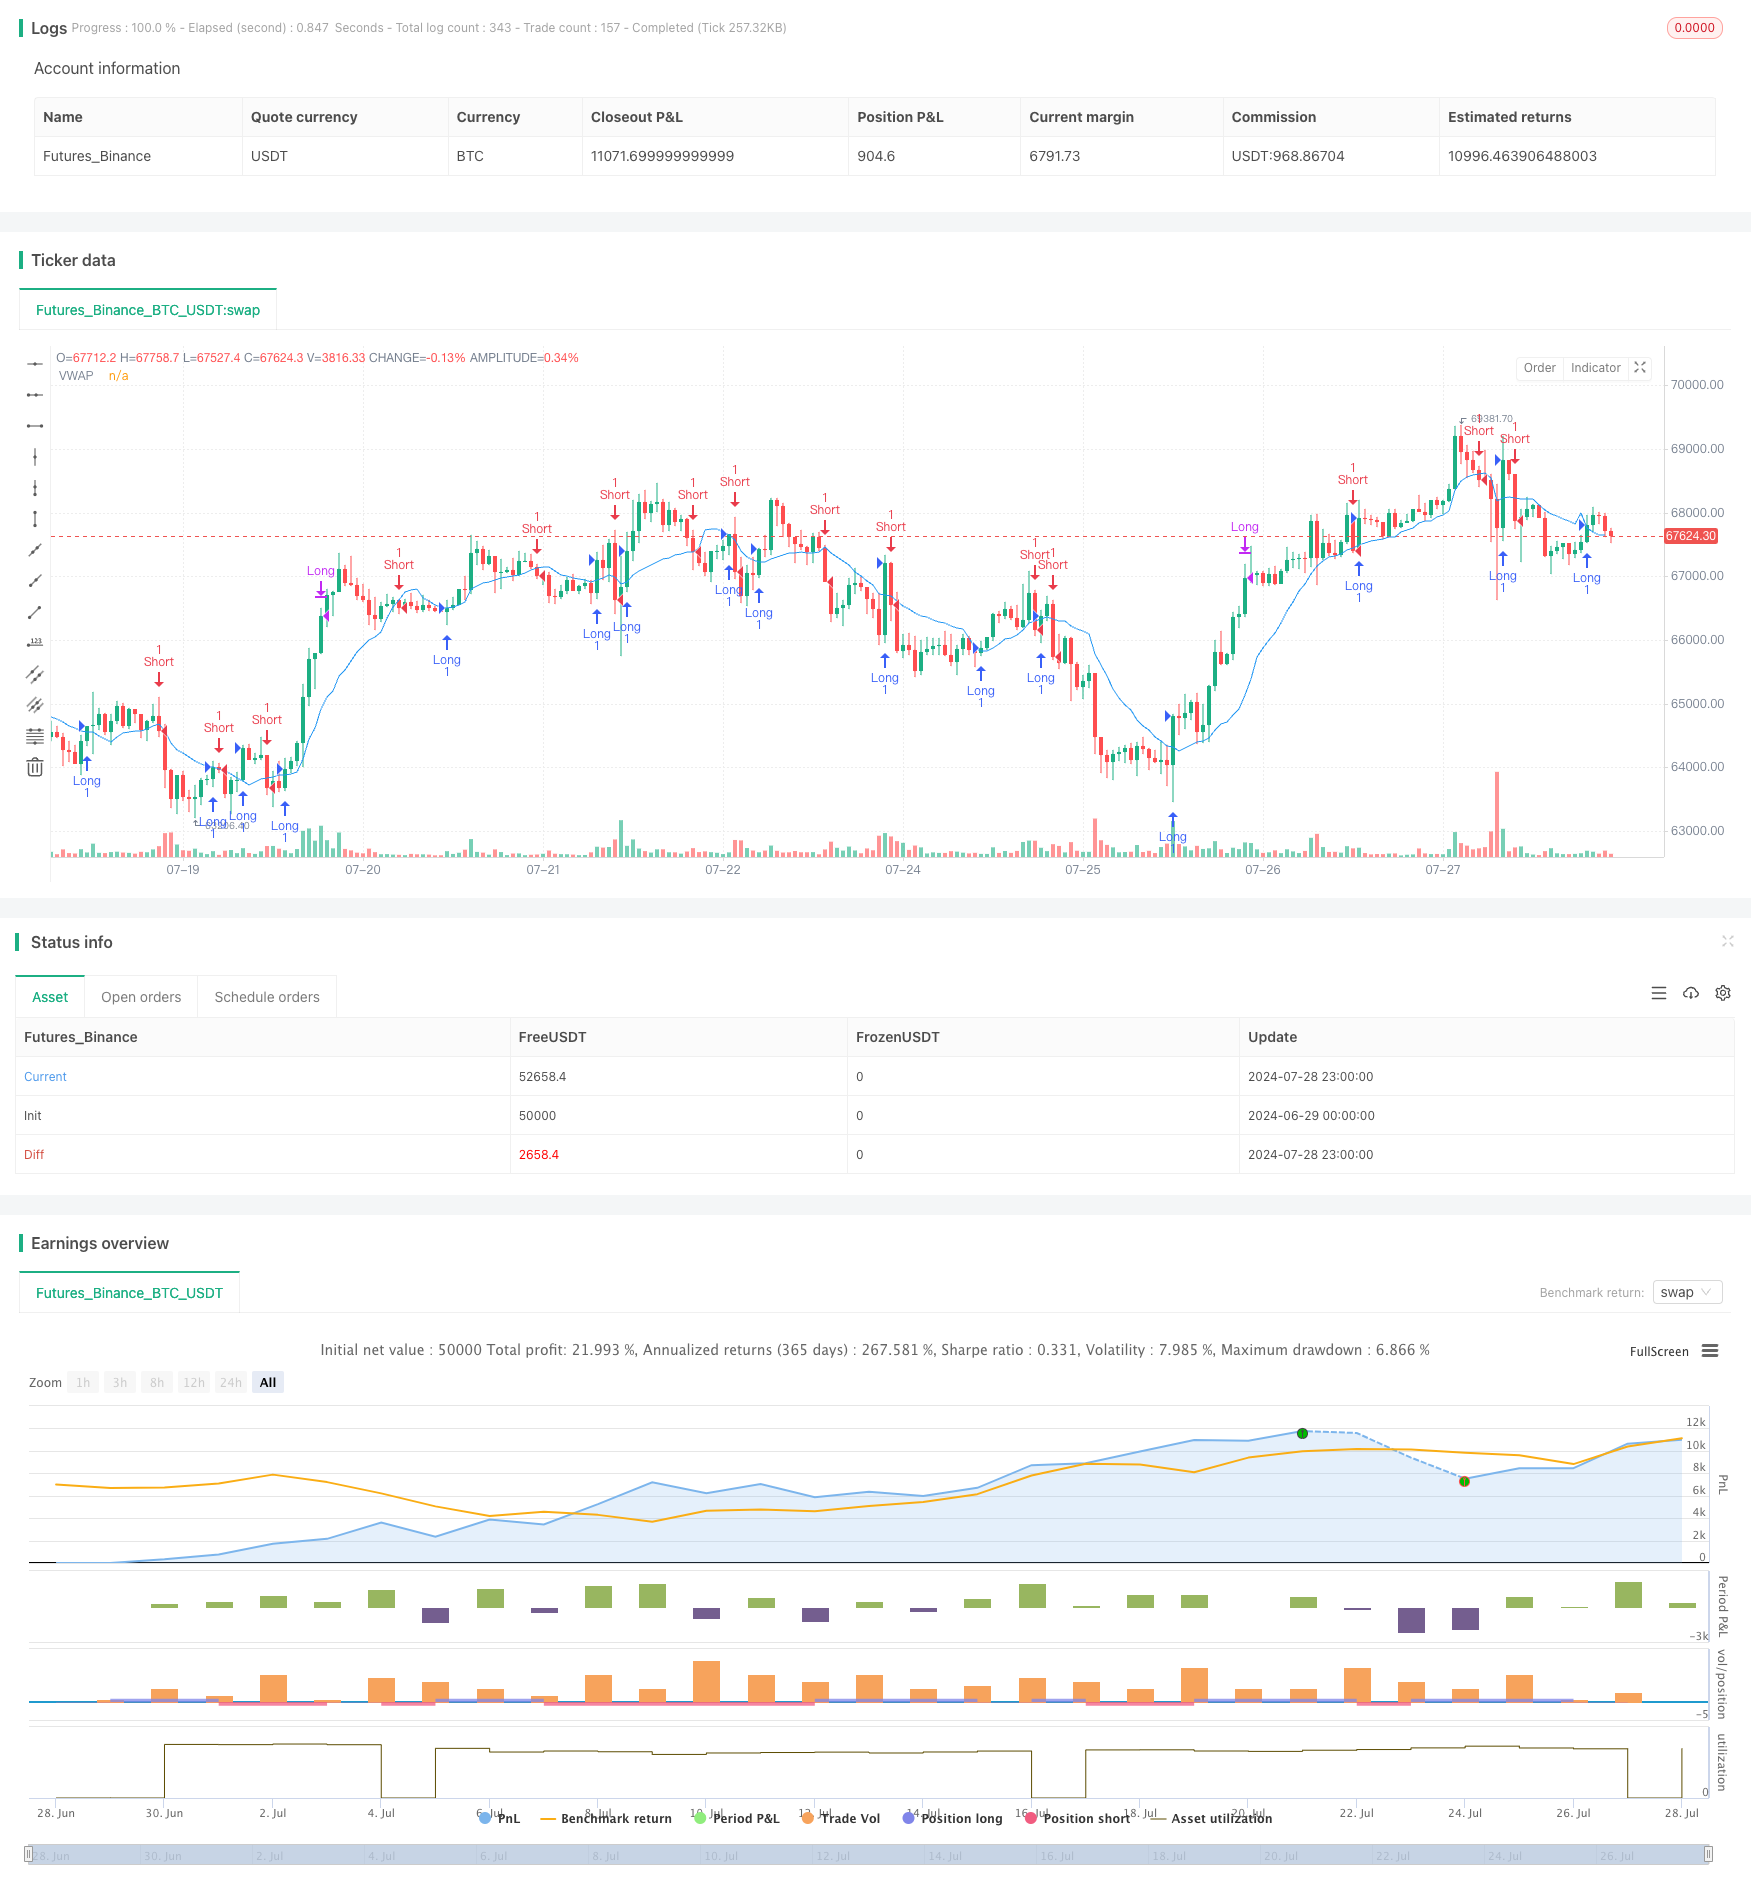
Overview
The VWAP Crossover Dynamic Profit Target Trading Strategy is a quantitative trading approach that combines Volume Weighted Average Price (VWAP) crossover signals with a fixed percentage profit target. This strategy utilizes VWAP as a dynamic support and resistance line, entering trades when price crosses the VWAP, and automatically closing positions when a predefined 3% profit target is reached. By integrating trend-following with profit-locking mechanisms, this method aims to capture short-term price movements while securing gains in a timely manner.
Strategy Principles
The core principles of this strategy include the following key elements:
VWAP Calculation: The strategy begins by calculating the 14-period VWAP, which serves as a dynamic benchmark for assessing price trends. VWAP calculation incorporates both price and volume, providing a more accurate reflection of market supply and demand balance.
Entry Signals:
- Long Entry: A buy signal is triggered when the closing price crosses above the VWAP.
- Short Entry: A sell signal is triggered when the closing price crosses below the VWAP.
Profit Targets:
- Long Position Exit: Automatically closes the position when the price reaches 103% of the entry price (3% increase).
- Short Position Exit: Automatically closes the position when the price reaches 97% of the entry price (3% decrease).
Position Management: The strategy allows for multiple positions in different directions, opening new trades with each crossover signal.
Strategy Advantages
Dynamic Support and Resistance: VWAP acts as a dynamic support and resistance line, adapting to market changes and providing more accurate trading signals.
Price-Volume Integration: VWAP incorporates both price and volume information, providing a more comprehensive view of market dynamics.
Automatic Profit Locking: The preset 3% profit target secures gains promptly, preventing profit erosion and enhancing the strategy's profitability stability.
Bidirectional Trading: The strategy captures both upward and downward market movements, increasing profit opportunities.
Simplicity: The strategy logic is clear and easy to understand, making it suitable for both novice and experienced traders.
Objectivity: Based on well-defined mathematical calculations and rules, the strategy reduces biases introduced by subjective judgment.
Strategy Risks
Frequent Trading: In highly volatile markets, the strategy may generate excessive trading signals, increasing transaction costs.
Limitations of Fixed Profit Targets: The 3% fixed profit target may perform inconsistently across different market environments, sometimes closing positions too early and missing larger trends.
Lack of Stop-Loss Mechanism: The strategy does not incorporate a stop-loss, potentially exposing trades to significant losses in extreme market conditions.
Slippage Impact: In less liquid markets, the strategy may face severe slippage, affecting its actual performance.
Market Condition Dependency: While potentially performing well in trending markets, the strategy may generate frequent false signals in range-bound markets.
Parameter Sensitivity: The VWAP period setting and profit target percentage significantly impact strategy performance, requiring careful optimization.
Strategy Optimization Directions
Dynamic Profit Targets: Consider adjusting profit targets dynamically based on market volatility, for example, using the Average True Range (ATR) to set profit objectives.
Adding Filters: Introduce additional technical indicators such as RSI or MACD as filters to reduce false signals.
Implementing Stop-Loss: Add stop-loss functionality, such as fixed amount, percentage-based, or indicator-based stop-losses, to limit potential losses.
Optimizing VWAP Period: Optimize the VWAP calculation period, possibly considering adaptive periods.
Position Sizing: Implement dynamic position sizing, adjusting trade sizes based on market volatility and account risk.
Time Filtering: Add trading time filters to avoid highly volatile or low liquidity periods.
Multi-Timeframe Analysis: Incorporate longer-term timeframe analysis to improve entry signal reliability.
Drawdown Control: Introduce maximum drawdown control mechanisms, pausing trading when a certain drawdown level is reached.
Conclusion
The VWAP Crossover Dynamic Profit Target Trading Strategy is a quantitative trading method that combines trend following with profit management. By utilizing VWAP as a dynamic reference line and setting fixed profit targets, the strategy aims to capture short-term price movements while securing gains promptly. Although the strategy logic is simple and intuitive, it still faces challenges such as overtrading and limitations of fixed profit targets in practical application. To enhance the strategy's robustness and adaptability, traders are advised to focus on dynamic parameter adjustment, adding filters, implementing stop-loss mechanisms, and other optimization directions. Simultaneously, thorough backtesting and parameter optimization are crucial for successful strategy implementation. Traders should continuously adjust and optimize strategy parameters based on specific trading instruments and market environments to achieve optimal trading results.
Source Pine Script
/*backtest
start: 2024-06-29 00:00:00
end: 2024-07-29 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("VWAP Crossover Strategy with Profit Targets", overlay=true)

// Define the period for calculating VWAP
cumulativePeriod = input(14, "VWAP Calculation Period")

// Calculate the Typical Price for the period
typicalPrice = (high + low + close) / 3

// Calculate Typical Price multiplied by volume
typicalPriceVolume = typicalPrice * volume

// Cumulative sum of Typical Price * Volume
cumulativeTypicalPriceVolume = sum(typicalPriceVolume, cumulativePeriod)

// Cumulative sum of Volume
cumulativeVolume = sum(volume, cumulativePeriod)

// Calculate VWAP
vwapValue = cumulativeTypicalPriceVolume / cumulativeVolume

// Plotting the VWAP on the chart
plot(vwapValue, color=color.blue, title="VWAP")

// Conditions for entering a long position (buy when price crosses above VWAP)
longCondition = crossover(close, vwapValue)
if (longCondition)
    strategy.entry("Long", strategy.long)

// Conditions for entering a short position (short when price crosses below VWAP)
shortCondition = crossunder(close, vwapValue)
if (shortCondition)
    strategy.entry("Short", strategy.short)

// Setting up a profit target to close the long position
longProfitTarget = strategy.position_avg_price * 1.03
if (strategy.position_size > 0 and close >= longProfitTarget)
    strategy.close("Long", comment="Long Profit Target Reached")

// Setting up a profit target to close the short position
shortProfitTarget = strategy.position_avg_price * 0.97
if (strategy.position_size < 0 and close <= shortProfitTarget)
    strategy.close("Short", comment="Short Profit Target Reached")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-07-30. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/VWAP-Crossover-Dynamic-Profit-Target-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- MOST Indicator Dual Position Adaptive StrategyPine Script · Trend following · 4h
- VWAP Moving Average Crossover with Dynamic ATR Stop Loss and Take Profit StrategyPine Script · Trend following · 1d
- TrendSync Pro SMC Multi Timeframe Trend Following StrategyPine Script · Trend following · 1h
- Multi Dimensional Technical Indicator Composite Trend Tracking Quantitative Trading StrategyPine Script · Trend following · 5m