Strategy vault / Mean reversion
VWAP RSI Oversold Crossunder BTC Short Strategy
This is a BTC short strategy across timeframes based on the RSI indicator of VWAP. It calculates the Volume Weighted Average Price (VWAP) of each candlestick to get a VWAP curve, and then applies the RSI indicator to…
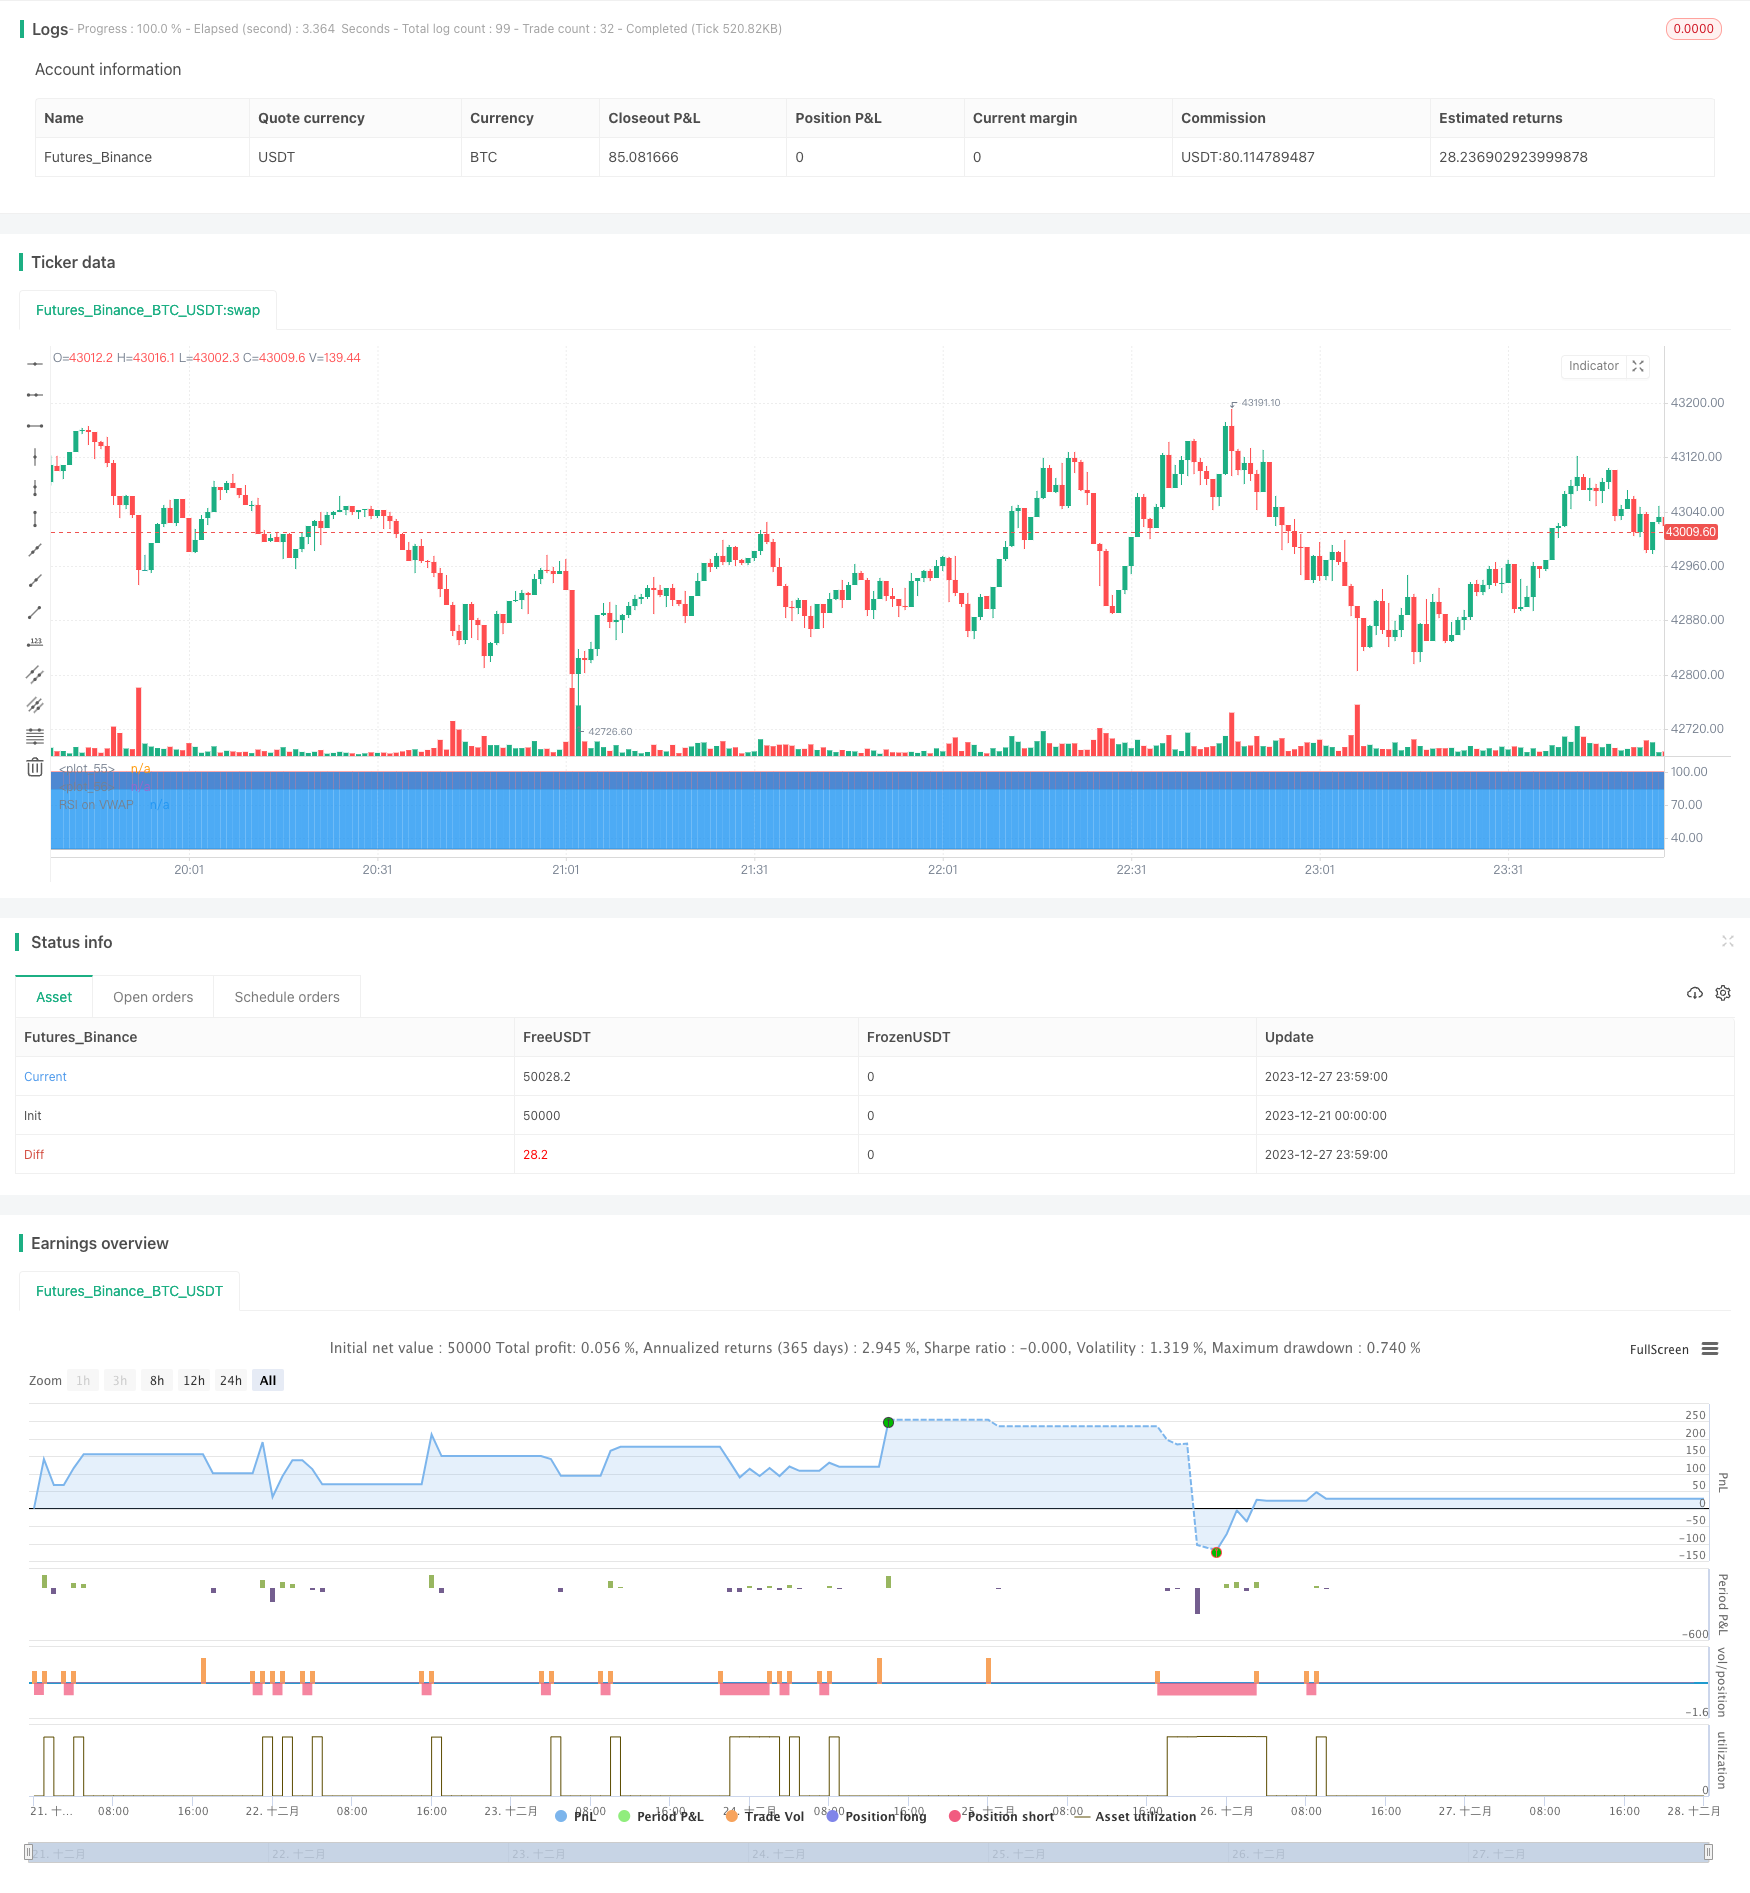
Overview
This is a BTC short strategy across timeframes based on the RSI indicator of VWAP. It calculates the Volume Weighted Average Price (VWAP) of each candlestick to get a VWAP curve, and then applies the RSI indicator to the curve. When the RSI indicator crosses down from the overbought zone, it goes short on BTC.
Strategy Logic
- Calculate VWAP of each candlestick to get a VWAP curve
- Apply RSI indicator to VWAP curve, with length of 20 days, overbought level at 85 and oversold level at 30
- When RSI crosses down from overbought zone (85) to oversold zone (30), open short position
- Close position after holding for 28 candlesticks, or if RSI crosses oversold line (30) again
Advantage Analysis
- Use VWAP instead of simple close price to reflect actual trading price
- Identify overbought/oversold status with RSI to avoid buying high and selling low
- Trade across timeframes to avoid being trapped
- Controllable risk with 28 candlesticks stop loss
Risks & Solutions
- Price surges rapidly due to black swan events, unable to stop loss
- Adopt across timeframes trading to reduce risks of being trapped
- Inappropriate parameter settings, easily miss opportunities
- Test and optimize RSI parameters and overbought/oversold levels
- RSI unable to cross into oversold zone
- Combine with other indicators to determine trend, adjust parameters flexibly
Optimization Directions
- Test more parameter combinations to find optimum
- Combine with MACD, KD etc to judge overbought/oversold status
- Test parameter settings separately for different assets
- Optimize stop loss mechanism, set stop loss range based on volatility
Summary
This strategy identifies BTC overbought/oversold status with the combination of VWAP and RSI. By trading across timeframes, it can effectively control risks. The strategy logic is clear and easy to understand, worth further testing and optimizing for live trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | Resolution | |
| v_input_2 | 20 | RSI Length |
| v_input_3 | 30 | RSI Oversold level |
| v_input_4 | 85 | RSI Overbought level |
| v_input_5 | 28 | Number of candles |
| v_input_6 | true | Enter longs ? |
| v_input_7 | true | Enter shorts ? |
| v_input_8 | 2020 | Strategy Start Year |
| v_input_9 | true | Strategy Start Month |
| v_input_10 | true | Strategy Start Day |
| v_input_11 | false | Use Laguerre on RSI ? |
| v_input_12 | 0.06 | Laguerre Gamma |
Source Pine Script
/*backtest
start: 2023-12-21 00:00:00
end: 2023-12-28 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/


//@version=4

strategy("Soran Strategy 2 - SHORT SIGNALS", pyramiding=1, initial_capital=1000, default_qty_type=strategy.percent_of_equity, default_qty_value=50, overlay=false)


// ----------------- Inputs ----------------- //

reso = input(title="Resolution", type=input.resolution, defval="")
length = input(20, title="RSI Length", type=input.integer)
ovrsld = input(30, "RSI Oversold level", type=input.float)
ovrbgt = input(85, "RSI Overbought level", type=input.float)
lateleave = input(28, "Number of candles", type=input.integer)
// lateleave : numbers of bars in overbought/oversold zones where the position is closed. The position is closed when this number is reached or when the zone is left (the first condition).

// best parameters BTCUSDTPERP M15 : 20 / 30 / 85 / 28


stratbull = input(title="Enter longs ?", type = input.bool, defval=true)
stratbear = input(title="Enter shorts ?", type = input.bool, defval=true)

stratyear = input(2020, title = "Strategy Start Year")
stratmonth = input(1, title = "Strategy Start Month")
stratday = input(1, title = "Strategy Start Day")
stratstart = timestamp(stratyear,stratmonth,stratday,0,0)


// --------------- Laguerre ----------------- //

laguerre = input(title="Use Laguerre on RSI ?", type=input.bool, defval=false)
gamma = input(0.06, title="Laguerre Gamma")

laguerre_cal(s,g) =>
    l0 = 0.0
    l1 = 0.0
    l2 = 0.0
    l3 = 0.0
    l0 := (1 - g)*s+g*nz(l0[1])
    l1 := -g*l0+nz(l0[1])+g*nz(l1[1])
    l2 := -g*l1+nz(l1[1])+g*nz(l2[1])
    l3 := -g*l2+nz(l2[1])+g*nz(l3[1])
    (l0 + 2*l1 + 2*l2 + l3)/6


// ---------------- Rsi VWAP ---------------- //

rsiV = security(syminfo.tickerid, reso, rsi(vwap(close), length))

rsiVWAP = laguerre ? laguerre_cal(rsiV,gamma) : rsiV


// ------------------ Plots ----------------- //

prsi = plot(rsiVWAP, color = rsiVWAP>ovrbgt ? color.red : rsiVWAP<ovrsld ? color.green : color.white, title="RSI on VWAP", linewidth=1, style=plot.style_line)
hline = plot(ovrbgt, color = color.gray, style=plot.style_line)
lline = plot(ovrsld, color = color.gray, style=plot.style_line)
fill(prsi,hline, color = rsiVWAP > ovrbgt ? color.red : na, transp = 30)
fill(prsi,lline, color = rsiVWAP < ovrsld ? color.green : na, transp = 30)


// ---------------- Positions: only shows the Short and close shoret positions --------------- //

timebull = stratbull and time > stratstart
timebear = stratbear and time > stratstart


strategy.entry("Short", false, when = timebear and crossunder(rsiVWAP, ovrbgt), comment="")
strategy.close("Short", when = timebear and crossunder(rsiVWAP, ovrsld)[lateleave] or crossover(rsiVWAP, ovrsld), comment="")Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/VWAP-RSI-Oversold-Crossunder-BTC-Short-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Market Cypher Wave B Automated Trading StrategyPine Script · Mean reversion · 1h
- Bollinger Bands and VWAP based Quantitative Trading StrategyPine Script · Mean reversion · 1h
- Reversal Catcher StrategyPine Script · Mean reversion · 1h
- A Momentum Tracking Mean Reversion StrategyPine Script · Mean reversion · 1h
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h