Strategy vault / Mean reversion
VWAP Standard Deviation Mean Reversion Trading Strategy
This is a mean reversion trading strategy based on Volume Weighted Average Price (VWAP) and standard deviation channels. The strategy identifies trading opportunities by measuring price deviations from VWAP, entering…
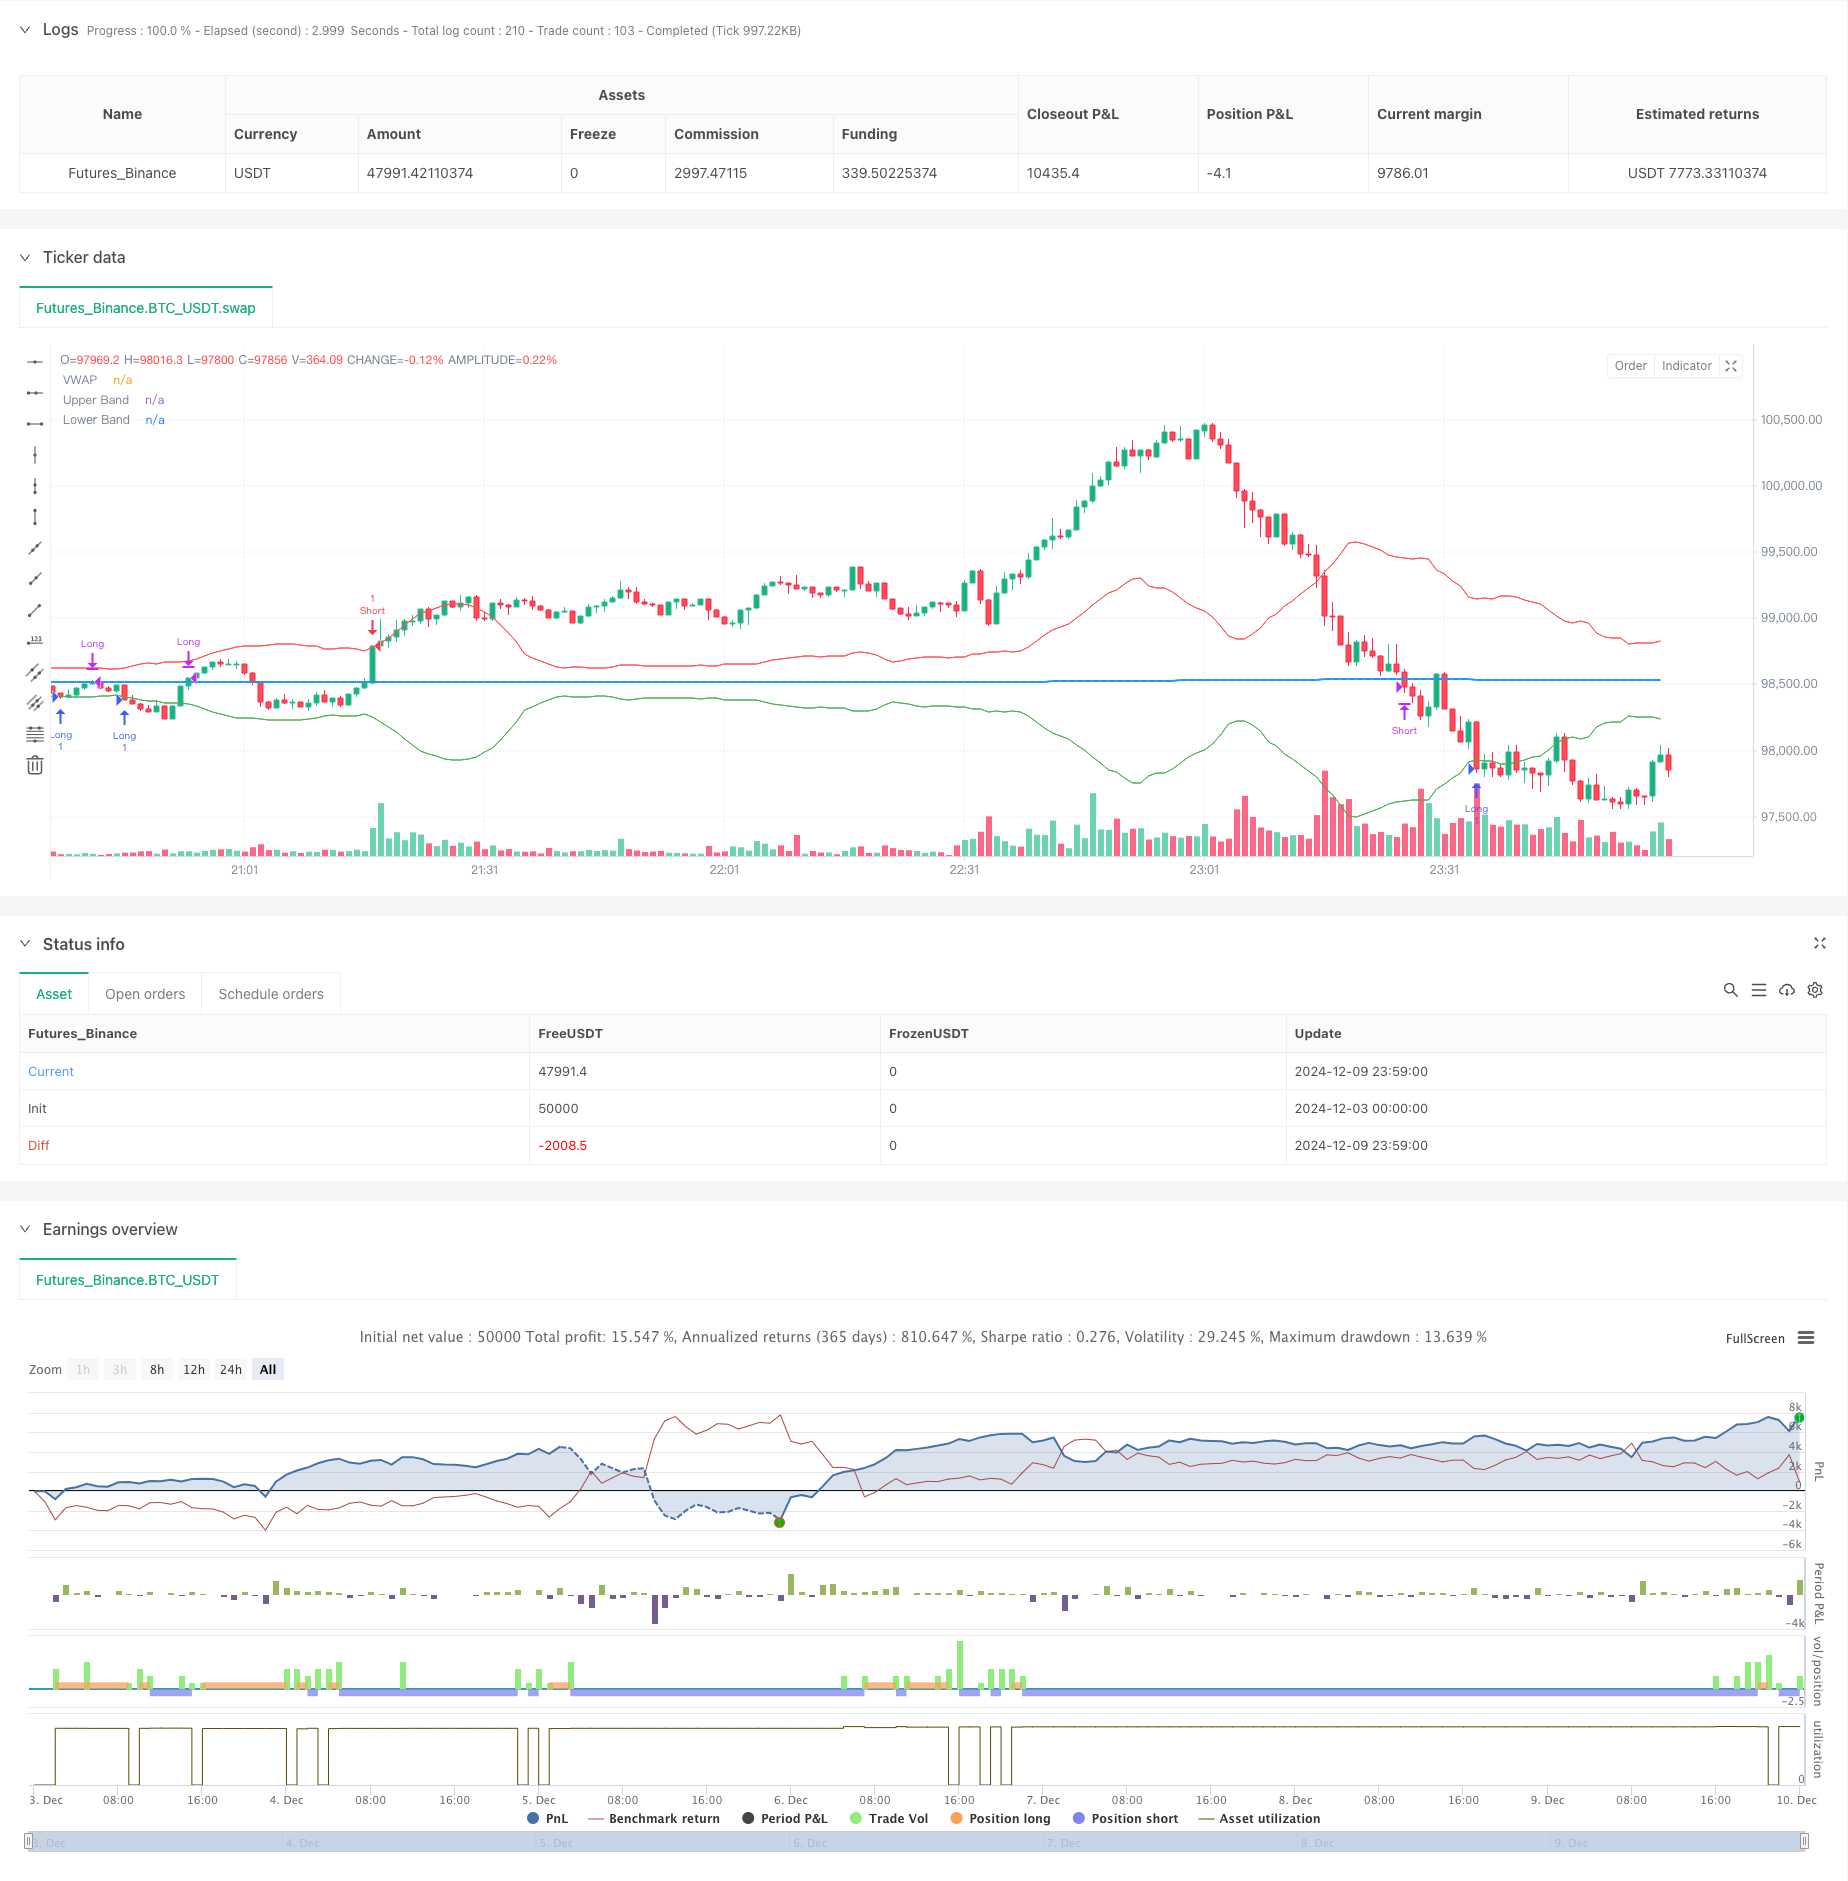
Overview
This is a mean reversion trading strategy based on Volume Weighted Average Price (VWAP) and standard deviation channels. The strategy identifies trading opportunities by measuring price deviations from VWAP, entering counter-trend positions when price breaks through standard deviation bands, and closing positions when price reverts to VWAP. This approach leverages market mean reversion characteristics, combining technical analysis and statistical principles.
Strategy Principles
The core mechanism relies on calculating VWAP and price volatility standard deviations to establish trading ranges. Specific implementation includes:
- Calculating cumulative VWAP: Using the cumulative product of price and volume divided by cumulative volume
- Computing standard deviation: Based on 20-period standard deviation of closing prices
- Constructing channels: Adding and subtracting 2 standard deviations from VWAP
- Trading signals:
- Long entry: Price crosses below lower band
- Short entry: Price crosses above upper band
- Exit conditions: Price reverts to VWAP level
Strategy Advantages
- Statistical foundation: Strategy built on reliable mean reversion statistical principles
- Objective trading signals: Uses clear mathematical indicators, avoiding subjective judgment
- Robust risk control: Limits entry points through standard deviation channels, uses VWAP reversion for profit-taking
- High adaptability: Standard deviation multiplier can be adjusted for different market conditions
- Liquidity consideration: VWAP is a key reference for institutional traders, trading in high liquidity zones
Strategy Risks
- Trend market risk: Mean reversion assumption may fail in strong trending markets
- Volatility change risk: Market volatility shifts can lead to wide stop losses
- Money management risk: Requires proper position sizing for each trade
- Slippage risk: May face significant slippage during high volatility Mitigation measures:
- Add trend filters
- Dynamically adjust standard deviation multiplier
- Set maximum holding time
- Implement percentage-based stops
Optimization Directions
- Add trend identification:
- Incorporate moving average combinations for trend detection
- Pause counter-trend trading during strong trends
- Optimize parameters:
- Implement adaptive standard deviation multiplier
- Adjust stop losses based on volatility
- Enhance risk management:
- Add maximum holding time limits
- Introduce volatility filters
- Improve accuracy:
- Combine with other technical indicators for signal confirmation
- Consider volume changes
Summary
This is a market-neutral strategy based on statistical principles, capturing price deviation and reversion using VWAP and standard deviation channels. The strategy features objective and systematic characteristics but requires attention to risk control and parameter optimization in practical application. Strategy stability and reliability can be further enhanced through the addition of trend filters and improved risk management mechanisms.
Source Pine Script
/*backtest
start: 2024-12-03 00:00:00
end: 2024-12-10 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © jklonoskitrader

//@version=5
strategy("ETHUSD VWAP Fade Strategy", overlay=true)

// Input for standard deviation multiplier
std_multiplier = input.float(2.0, title="Standard Deviation Multiplier")

// Calculate cumulative VWAP
cumulative_pv = ta.cum(close * volume) // Cumulative price * volume
cumulative_vol = ta.cum(volume)        // Cumulative volume
vwap = cumulative_pv / cumulative_vol  // VWAP calculation

// Calculate standard deviation of the closing price
length = input.int(20, title="Standard Deviation Length")
std_dev = ta.stdev(close, length)
upper_band = vwap + std_multiplier * std_dev
lower_band = vwap - std_multiplier * std_dev

// Plot VWAP and its bands
plot(vwap, color=color.blue, linewidth=2, title="VWAP")
plot(upper_band, color=color.red, linewidth=1, title="Upper Band")
plot(lower_band, color=color.green, linewidth=1, title="Lower Band")

// Strategy conditions
go_long = ta.crossunder(close, lower_band)
go_short = ta.crossover(close, upper_band)

// Execute trades
if (go_long)
    strategy.entry("Long", strategy.long)
if (go_short)
    strategy.entry("Short", strategy.short)

// Exit strategy
if (strategy.position_size > 0 and close > vwap)
    strategy.close("Long")
if (strategy.position_size < 0 and close < vwap)
    strategy.close("Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/VWAP-Standard-Deviation-Mean-Reversion-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Multi Indicator Dynamic Reversal Trading System RSI and VWAP Synergistic Reversal StrategyPine Script · Mean reversion · 1h
- Anchored Rolling CVDVWAP Signal StrategyPine Script · Mean reversion · 1d
- BabyShark VWAP Trading Strategy Based on VWAP and OBV RSI IndicatorsPine Script · Mean reversion · 2h
- EMA VWAP Synergy CBC Reversal Trend Following Quantitative Trading StrategyPine Script · Mean reversion · 1h
- Market Cypher Wave B Automated Trading StrategyPine Script · Mean reversion · 1h